

The Short Version
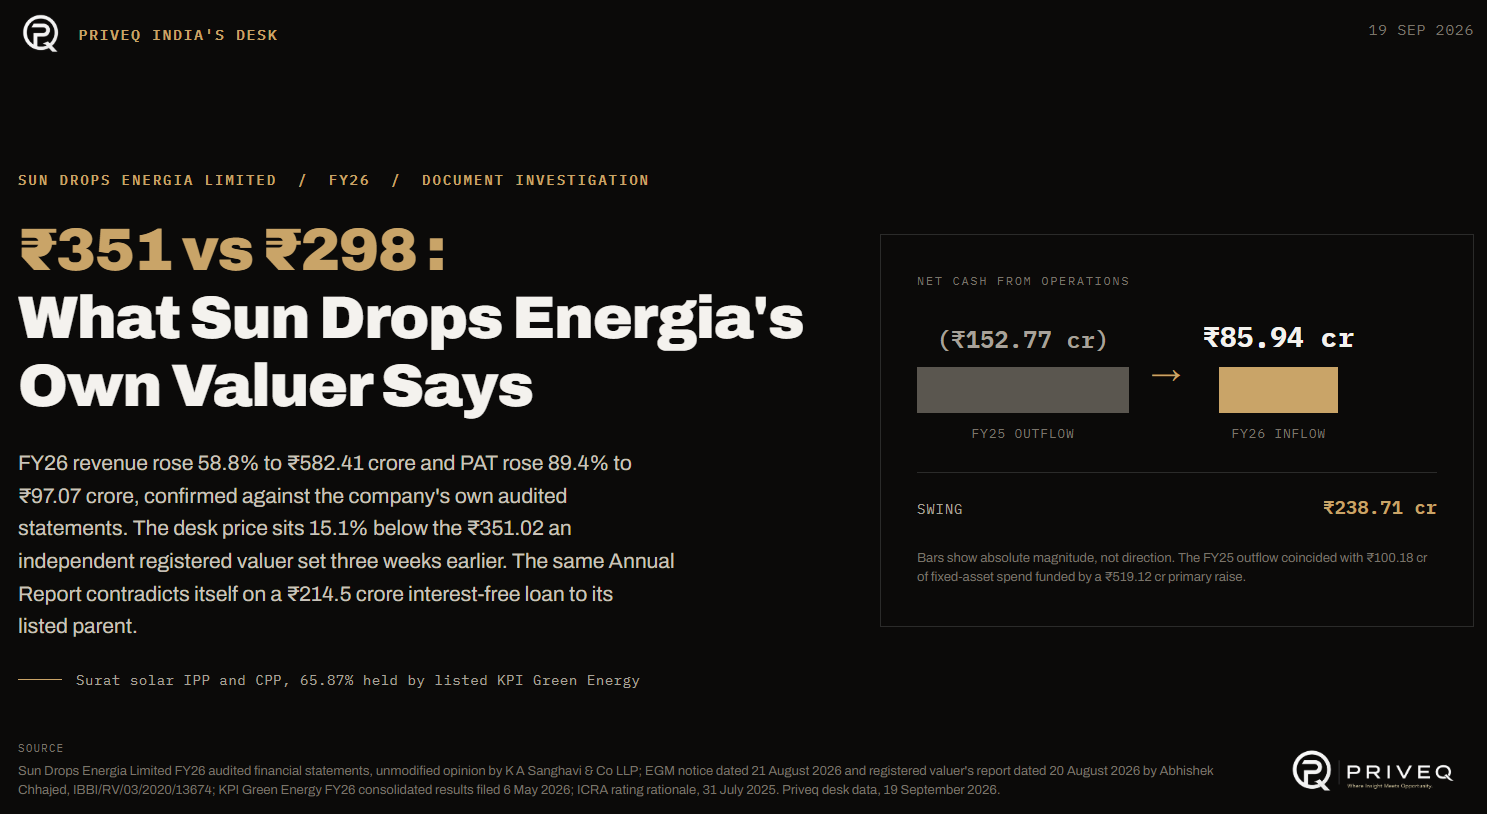
Sun Drops Energia Limited, a Surat-headquartered solar Independent Power Producer and Captive Power Producer that is 65.87%-owned by listed KPI Green Energy Limited, had a genuinely strong FY26: revenue up 58.8% to ₹582.4 crore and PAT up 89.4% to ₹97.1 crore, both independently confirmed against the company's own audited financial statements. Three weeks before this piece, an independent registered valuer priced the company's new shares at ₹351.02 for an in-progress acquisition, a real, dated, professional valuation that sits above Priveq's current desk price of ₹298, itself already a discount of roughly 15%. Separately, at ₹298, Sun Drops trades at roughly 2.25 times the price-earnings multiple its own listed parent commands on the open market, a comparison no unlisted peer set could offer. That parent relationship cuts both ways: KPI Green Energy's unconditional corporate guarantee is the entire basis for Sun Drops' own credit rating, a real strength, but the same FY26 Annual Report that reports this growth also contains a direct, internal contradiction over a ₹214.5 crore, interest-free, no-fixed-term loan Sun Drops has made to that same parent. The desk is treating both facts as real and stating them together.
The Desk Snapshot
Sun Drops Energia Limited (CIN: U40107GJ2019PLC108373), unlisted solar IPP/CPP, 65.87%-held subsidiary of listed KPI Green Energy Limited (NSE: KPIGREEN, BSE: 542323). Figures cross-checked across the company's own FY26 audited financial statements, its 21 August 2026 EGM notice, and KPI Green Energy's own FY26 filings.
Metric | Detail |
|---|---|
Priveq desk price | ₹298 per share |
Implied valuation | ~₹2,584.6 crore (8,67,31,372 shares outstanding) |
FY26 revenue | ₹582.41 crore, up 58.8% YoY |
FY26 PAT | ₹97.07 crore, up 89.4% YoY |
Implied P/E (FY26 basis) | 26.63x |
vs. registered valuer's Aug 2026 price | 15.1% below the ₹351.02/share valuer mark |
vs. parent KPI Green Energy's own P/E | ~2.25x the parent's listed multiple (11.86x) |
Biggest positive | Real, accelerating growth; priced below a three-week-old professional valuation; parent's unconditional corporate guarantee underwrites Sun Drops' own credit rating |
Biggest risk | FY26 Annual Report directly contradicts itself on a ₹214.5 crore, interest-free, no-term related-party loan to the listed parent |
Key monitor | Whether FY27 disclosures resolve the CARO-vs-Note-49(iv) contradiction, and whether the parent-multiple gap narrows |
Share count and face value (₹5, post 1:2 split executed in FY26) confirmed from the Statement of Changes in Equity in the company's own FY26 audited financial statements, matching the pre-issue share count in the 21 August 2026 EGM notice exactly.
The Business : Products, Capacity, and Revenue Streams
Sun Drops Energia Limited (formerly Sun Drops Energia Private Limited, CIN U40107GJ2019PLC108373) is headquartered in Surat, Gujarat, and operates as both an Independent Power Producer (IPP) and a Captive Power Producer (CPP) of solar power. The company develops, builds, and maintains solar power plants, selling generated power under long-term Power Purchase Agreements (PPAs) as an IPP, and building and maintaining CPP plants for industrial and commercial clients under a separate commercial model.
Per an independent ICRA credit rating dated 31 July 2025, the company's rated project capacity is:
IPP solar capacity : approximately 8 MWAc
Hybrid capacity (solar and wind) : approximately 13.5 MW
This cross-checks closely against the company's own FY26 Annual Report, which separately identifies an "8 MW solar plant situated at Ranada" and a "13.6 MW hybrid solar plant situated at Vagra" as collateral behind its State Bank of India term loans, two independent sources landing on essentially the same figures, a genuine cross-check rather than a single unverified claim. ICRA separately reports a CPP/EPC order book of approximately ₹560 crore as of March 2025, sourced from a credit rating agency rather than the company's own investor materials, which clears a meaningfully higher verification bar than an unaudited order-book claim usually would.
The company operates in a single reportable segment under Ind AS 108, "the development of solar parks for generation and distribution of green electricity," per its own FY26 financial statements; no further product- or plant-level revenue split is disclosed or required.
Net read : The capacity figures check out across two independent sources, and the CPP/EPC order book comes with a rating agency's name behind it rather than a company slide deck's. This is a real, operating solar business with a specific, verifiable footprint in Gujarat, not merely a paper subsidiary of its listed parent.
Corporate History, Capital Structure, and the KPI Green Energy Relationship
Sun Drops Energia was incorporated in 2019 and converted to a public limited company during FY26. As at 31 March 2026, the company's paid-up equity share capital stood at ₹43.37 crore across 8,67,31,372 equity shares of ₹5 face value each, following a 1:2 stock split (from ₹10 to ₹5 face value) executed during the year; the share count was 4,33,65,686 pre-split.
The company is not standalone. Per its own Related Party Transactions note and shareholding schedule:
KPI Green Energy Limited (listed on BSE, scrip code 542323, and NSE, symbol KPIGREEN) holds 65.87% of Sun Drops Energia, unchanged in percentage terms year-over-year.
Dr. Faruk Gulam Patel, Chairman and Non-Executive Director, personally holds a further 13.13%.
Combined promoter holding : 79.00% pre-issue (as of the most recent EGM notice).
The Related Party Transactions note lists more than 60 entities under common key-managerial-personnel control, consistent with Sun Drops sitting inside a much larger "KP Group" of renewable-energy entities.
The parent relationship is not just an equity holding; it is embedded in Sun Drops' own debt security package. The company's State Bank of India term loans are secured by, among other things, a personal guarantee from Dr. Faruk Gulam Patel and Mr. Mohmed Sohil Y. Dabhoya, a corporate guarantee from KPI Green Energy Limited, and a pledge of 16,05,000 of Sun Drops' own shares held by KPI Green Energy Limited. Separately, ICRA's credit rating on Sun Drops' debt is explicitly a Credit-Enhanced rating, [ICRA]A(CE) (Positive), which ICRA states depends on "the strength of the corporate guarantee provided by KPI Green Energy Limited," described as "legally enforceable, irrevocable, unconditional." Without that guarantee, ICRA's own standalone assessment of Sun Drops would be one full rating category lower, at [ICRA]A-.
A live corporate action worth flagging plainly : on 21 August 2026, Sun Drops' Board approved acquiring up to 100% of a company called DEK and Mavericks Green Energy Limited, entirely through a share swap, no cash involved. The consideration takes the form of up to 15,89,781 Compulsorily Convertible Preference Shares (CCPS) at ₹351.02 each (₹5 face value plus ₹346.02 premium), aggregating up to ₹55.80 crore, per an EGM notice dated 21 August 2026. That price was set using an independent registered valuer's report (Mr. Abhishek Chhajed, IBBI Registered Valuer, Registration No. IBBI/RV/03/2020/13674, dated 20 August 2026, relevant date 31 March 2026). Two details are worth stating precisely rather than glossing over: Dr. Faruk G. Patel, Sun Drops' own promoter, personally holds shares in the target company and is subscribing 1,42,202 of the CCPS himself, and the CCPS conversion terms state the shares convert to equity "within 12 months of allotment of CCPS or filing of Red Herring Prospectus (RHP) with Securities and Exchange Board of India (SEBI), whichever is earlier." A company does not write an RHP-filing trigger into a securities instrument unless an IPO is a live, board-contemplated possibility, not distant speculation. The EGM notice itself states there will be no change of control from this transaction; promoter group holding moves from 79.00% to 77.73% post-conversion.
Net read : Sun Drops Energia is best understood as a structured, credit-supported subsidiary inside a larger, listed renewable-energy group, currently in the middle of a related-party consolidation that looks like pre-IPO cap-table cleanup. The parent guarantee is real and rated. The promoter's personal stake in the transaction, and the RHP-linked conversion trigger, are both facts a reader should have plainly, not buried.
FY25-FY26 Financial Performance
FY26 revenue rose 58.8% to ₹582.41 crore from ₹366.67 crore in FY25. PAT rose 89.4% to ₹97.07 crore from ₹51.25 crore, comfortably outpacing revenue growth in percentage terms. EPS, on a split-adjusted basis per the company's own financial statements, rose from ₹7.40 (FY25) to ₹11.19 (FY26). Net Profit Ratio (per the company's own Note 45 Ratio Analysis) improved from 13.98% to 16.67%.
Operating cash flow swung decisively: net cash used in operating activities was ₹152.77 crore in FY25, turning to net cash generated of ₹85.94 crore in FY26, a genuine, large improvement, not a marginal one. The FY25 outflow coincides with a year of heavy capital deployment (₹100.18 crore in fixed-asset and CWIP payments, plus a ₹519.12 crore primary equity raise that funded it), while FY26 shows the business converting its now-larger asset base into positive operating cash generation.
The company's own Note 45 Ratio Analysis, independently checked by the desk against the underlying Balance Sheet and P&L figures, shows a business with low leverage and comfortable coverage:
Debt-Equity Ratio : 0.11x (FY26) vs. 0.08x (FY25); still very low in absolute terms, though the percentage increase (35.4%) reflects a real rise in non-current borrowings
Debt Service Coverage Ratio : 6.42x (FY26) vs. 9.19x (FY25); comfortably above typical lender covenants in both years
Return on Equity : 14.87% (FY26) vs. 15.10% (FY25), computed on average equity, a calculation the desk independently reproduced and confirmed against the company's own stated figures
Return on Capital Employed : 19.47% (FY26) vs. 19.44% (FY25); essentially flat and strong
Current Ratio : fell sharply from 7.70x to 2.90x, driven by a large jump in current liabilities; still a healthy ratio in absolute terms, but the direction of change is worth watching given the pace of the company's capital deployment
FY25-FY26, from the company's own audited filings
Source: Sun Drops Energia Limited's FY26 audited Balance Sheet, Profit & Loss, Cash Flow Statement, and Note 45 Ratio Analysis. All figures reconcile to the rupee against the underlying statements.
Metric | FY25 | FY26 |
|---|---|---|
Revenue | ₹366.67 Cr | ₹582.41 Cr |
PAT | ₹51.25 Cr | ₹97.07 Cr |
EPS (split-adjusted) | ₹7.40 | ₹11.19 |
Net Profit Ratio | 13.98% | 16.67% |
Net Cash from Operating Activities | (₹152.77 Cr) | ₹85.94 Cr |
Debt-Equity Ratio | 0.08x | 0.11x |
Debt Service Coverage Ratio | 9.19x | 6.42x |
Return on Equity (average-equity basis) | 15.10% | 14.87% |
Return on Capital Employed | 19.44% | 19.47% |
Current Ratio | 7.70x | 2.90x |
ROE and ROCE computed by the company on average and average-capital-employed bases respectively, independently reproduced and confirmed by the desk against the underlying Balance Sheet figures. Only FY25-FY26 shown
Net read : This is real, accelerating, profitable growth, not a story that needs qualification to hold up. Leverage remains genuinely low even after rising, and coverage ratios stay comfortable in both years. The one line worth watching going forward is the current ratio's sharp compression, ordinary for a business scaling this fast, but worth tracking into FY27 rather than assuming it stabilizes on its own.
The Registered Valuer's Price, and What It Means for the Desk Quote
On 20 August 2026, an independent IBBI-registered valuer priced new Sun Drops Energia shares at ₹351.02 each, for the purpose of the DEK and Mavericks Green Energy Limited share-swap acquisition described above. That price is not a company estimate or a platform figure; it is a professional valuation report, dated three weeks before this piece, prepared for a specific, board-approved, regulator-facing corporate action.
Priveq's current desk price is ₹298, a discount of approximately 15.1% to that registered-valuer price. The arithmetic:
₹351.02 − ₹298.00 = ₹53.02 discount, or 53.02 ÷ 351.02 = 15.10%
Sun Drops Energia: Desk Price vs. Registered Valuer's Price (Aug 2026)
The registered valuer's price was set for a related-party, non-cash share-swap acquisition, not an arm's-length primary raise; shown here as a dated, professional reference point, not a target price.
Item | Value |
|---|---|
Registered valuer's price (IBBI Reg. No. IBBI/RV/03/2020/13674, 20 Aug 2026, relevant date 31 Mar 2026) | ₹351.02 |
Priveq desk price (current) | ₹298.00 |
Discount to valuer's price | 15.1% |
₹351.02 − ₹298.00 = ₹53.02
₹53.02 ÷ ₹351.02 = 15.10% discountValuer: Mr. Abhishek Chhajed, IBBI Registered Valuer, Registration No. IBBI/RV/03/2020/13674, report dated 20 August 2026. Price set for the proposed acquisition of DEK and Mavericks Green Energy Limited via CCPS issuance, per Sun Drops Energia's EGM notice dated 21 August 2026.
This is the mirror image of the more familiar "unlisted stock trading above its last funding round" story: here, a professional, dated, primary-sourced valuation sits above where the stock is currently quoted. The desk is not treating a single valuer's report as gospel: valuations are opinions, not facts, and this one was prepared for a related-party, non-cash transaction, which is a different context than an arm's-length primary raise. Still, it is a real, current, well-documented data point that argues the current desk price is not stretched.
Net read : Whatever view a reader takes on Sun Drops' underlying growth, they are not being asked to pay a premium over the company's own most recent professional valuation. That is a genuinely favorable starting point, stated plainly rather than buried under caveats.
Benchmarking Against a Listed Parent
Because Sun Drops Energia is a 65.87%-held subsidiary of a listed company, it offers something no purely unlisted peer comparison can: a real, continuously-updating market multiple to benchmark against, from its own parent's audited results and live share price.
The comparison, computed directly by the desk:
Sun Drops Energia at Priveq's ₹298 desk price, on FY26 EPS of ₹11.19: implied P/E of 26.63x
KPI Green Energy Limited (parent), on its own FY26 audited consolidated diluted EPS of ₹24.04 and a share price of ₹285 (as of 18 September 2026): implied P/E of 11.86x
Sun Drops therefore trades at roughly 2.25 times its own listed parent's earnings multiple
Sun Drops Energia P/E Ratio vs. KPI Green Energy Benchmark
Sun Drops Energia (unlisted) figures per Priveq's desk price and the company's own FY26 audited EPS; KPI Green Energy Limited (NSE: KPIGREEN, BSE: 542323) figures per its own FY26 audited consolidated results (filed with BSE/NSE, 6 May 2026) and live share price (18 September 2026).
Metric | Sun Drops Energia (unlisted) | KPI Green Energy Ltd. (listed) |
|---|---|---|
Price | ₹298 (Priveq desk) | ₹285 (NSE/BSE, 18 Sep 2026) |
FY26 EPS (diluted where available) | ₹11.19 | ₹24.04 |
Implied P/E | 26.63x | 11.86x |
FY26 Revenue | ₹582.41 Cr | ₹2,695.91 Cr (consolidated) |
FY26 PAT | ₹97.07 Cr | ₹509.24 Cr (consolidated) |
FY26 Revenue growth YoY | 58.8% | 55.3% |
26.63x ÷ 11.86x = 2.25x
Sun Drops trades at ~2.25 times the parent's own listed P/EKPI Green Energy's FY26 audited consolidated results explicitly include Sun Drops Energia Limited within their consolidation scope, confirmed directly in the auditor's report accompanying those results. Screener.in independently reports KPI Green Energy's P/E at 12.4x on a TTM-EPS basis (₹23.19); the desk uses the parent's own FY26 audited diluted EPS (₹24.04) for this table's calculation, a small difference in method, not a discrepancy in the underlying fact.
KPI Green Energy's own FY26 consolidated results, filed with BSE and NSE under Regulation 33/52, explicitly name Sun Drops Energia as one of "3 subsidiaries and 6 wholly owned SPVs" within the audited consolidation scope, removing any ambiguity about the group structure. The parent's FY26 consolidated revenue was ₹2,695.91 crore (up from ₹1,735.45 crore in FY25) and consolidated PAT was ₹509.24 crore (up from ₹325.28 crore), a group growing quickly in its own right, and the board recommended a special dividend of ₹0.15 per share "for Successful Energization of 1 GW IPP Project," a real, dated, group-level milestone.
A governance data point worth stating alongside this, from the parent's own NSE shareholding pattern disclosure (most recent quarter on record, reviewed 18 September 2026) : KPI Green Energy's promoter group holds 49.40% of the company, of which 44.74% of the promoter's own holding (22.10% of total shares outstanding, valued at approximately ₹1,739.29 crore) is pledged or otherwise encumbered. This sits at the parent level, not inside Sun Drops' own capital structure, and does not by itself affect the corporate guarantee ICRA describes as unconditional, but it is a real fact about the group's financial position that a reader benchmarking against the parent's multiple should have.
Net read : A subsidiary trading at more than double its own listed parent's earnings multiple is a real gap worth sitting with, not explaining away. Some premium is defensible, Sun Drops' own growth rate outpaces the parent's, but a 2.25x multiple gap is large enough that the desk is not calling it fully justified by growth alone; it is presented here as the clearest, most concrete valuation tension in this piece.
The Related-Party Loan Contradiction
This is the most serious finding in this piece, and the desk is stating it precisely rather than softening it.
Governance Finding: Sun Drops Energia's FY26 Annual Report contains an unresolved disclosure contradiction. CARO Annexure A, Clause III reports ₹214.49 crore in interest-free loans to parent KPI Green Energy Limited with no stipulated repayment terms, while Note 49(iv) of the same financial statements states the Company has not granted any loan or advance to related parties without specifying repayment terms. Both cannot be true; this is an open, unresolved item in the company's own disclosures, not a resolved allegation.
Two passages in Sun Drops Energia's own FY26 Annual Report directly contradict each other :
CARO Annexure A, Clause III (the statutory auditor's own report, forming part of the same Annual Report) discloses that the company has ₹220.68 crore in loans outstanding to "Group companies/entities" as at 31 March 2026, of which ₹220.68 crore, 98.22% of all such loans, has, in the auditor's own words, "no stipulated repayment schedule." Note 44 (Related Party Transactions) separately confirms ₹214.49 crore of this is owed specifically by KPI Green Energy Limited, the listed parent, up from ₹174.41 crore the year before. No interest has been booked on these loans.
Note 49(iv), a few pages later in the same set of financial statements, states flatly: "The Company has not granted any loan or advance in nature of loan to promoters, directors, key managerial personnel and related parties... that is (a) repayable on demand; or (b) without specifying any terms or period of repayment."
Sun Drops Energia FY26 Annual Report : A Direct Internal Contradiction
Two passages in the same audited financial statements, on the same subject, cannot both be accurate.
Source (same FY26 Annual Report) | What it states |
|---|---|
CARO Annexure A, Clause III (CARO 2020, Paragraph 3, Clause (iii); statutory auditor's own report) | ₹220.68 Cr owed by "Group companies/entities," of which ₹220.68 Cr (98.22%) has "no stipulated repayment schedule." Note 44 confirms ₹214.49 Cr of this is owed by KPI Green Energy Limited (the parent). |
Note 49(iv) (Additional Regulatory Information, related parties as defined under the Companies Act, 2013) | "The Company has not granted any loan or advance in nature of loan to promoters, directors, key managerial personnel and related parties... that is (a) repayable on demand; or (b) without specifying any terms or period of repayment." |
Both passages are read directly from Sun Drops Energia Limited's FY26 audited financial statements. The desk is not resolving this contradiction or asserting which statement is correct; it is presented here as an open, unresolved item in the company's own disclosures.
Both statements cannot be true. The desk is not resolving this discrepancy or guessing at which one is the error; it is stated here as a direct, internal contradiction in the company's own audited disclosures, and readers should treat it as an open item pending clarification, not a settled fact in either direction.
Context worth adding, not as an excuse but as a plausible explanation : KPI Green Energy's own consolidated Debt-Equity ratio rose sharply, from 0.46x to 1.49x, over the same year, alongside a large capital-expenditure ramp (Capital work-in-progress rising from ₹163.47 crore to ₹918.04 crore at the consolidated level). It is plausible that capital is being routed within the group to fund this expansion, with Sun Drops functioning as an internal lender to its own parent. That would explain the scale and direction of the loan. It does not explain, and does not excuse, the direct contradiction between what the auditor discloses and what Note 49(iv) states.
Net read : This is a disclosure-quality finding, not evidence of fraud or diversion, no cash appears to be missing, and the loan is fully disclosed in at least one place in the same document. But an Annual Report that contradicts itself on whether a ₹214.5 crore related-party loan without repayment terms exists is a real governance flag, and it sits in the same document as genuinely strong growth. Both are true.
Litigation and Other Disclosures
Per Note 48 (Contingent Liabilities), WRIT petitions have been filed against orders of the District Collector, Bharuch, which had approved the company's application to develop a transmission line through petitioners' lands under the Indian Telegraph Act, 1885, the Electricity Act, 2003, and the Works of Licensee's Rules, 2006. Per the company's own legal counsel's opinion, cited in the same note, these petitions "are not tenable in the eyes of law," and because the financial impact is not quantifiable, no provision has been made. The desk has no independent view on the merits of this litigation beyond what the company's own filing states.
Separately, the same Annual Report's CARO Annexure discloses a reconciliation gap between the company's own books and the stock/book-debt statements it submitted to its working-capital lenders: book debts as at 31 March 2026 were ₹89.63 crore per the company's books versus ₹82.21 crore per the statement submitted to the bank, a difference of ₹7.42 crore, with larger gaps in earlier quarters of the same year (a ₹31.35 crore difference as at 30 September 2025). The auditor notes this reconciliation is disclosed in Note 49(v) of the financial statements. The desk is not characterizing this as an irregularity on its own, quarterly stock-statement reconciliation gaps are common in working-capital-linked lending, but it is disclosed here for completeness alongside the more serious related-party finding above.
Net read : Neither item here rises to the seriousness of the related-party loan contradiction. The litigation looks procedurally routine and non-quantifiable by the company's own account; the stock-statement gap is a common feature of bank-linked working capital facilities. Both are included because a reader piecing together the full picture deserves them, not because either changes the desk's overall view on its own.
The Desk View
Priveq's desk price for Sun Drops Energia Limited is ₹298 per share, implying a valuation of approximately ₹2,584.6 crore, 26.6 times FY26 PAT of ₹97.07 crore. Four things drive that view, stated as a set:
The growth is real, and it does not need softening. Revenue up 58.8%, PAT up 89.4%, operating cash flow swinging from a ₹152.8 crore outflow to an ₹85.9 crore inflow within one year. This is a business converting a large capital raise into real, cash-generative operating performance, not a story propped up by one favorable line item.
The price sits below a three-week-old professional valuation. At ₹298, the desk price is roughly 15.1% below the ₹351.02 an independent registered valuer set for Sun Drops' own new shares on 20 August 2026. That is a genuinely favorable starting point for anyone evaluating an entry.
The parent relationship is a real, rated strength, and also the source of this piece's most serious open question. KPI Green Energy Limited's unconditional corporate guarantee is the entire basis for Sun Drops' own credit rating; that same relationship is also where a ₹214.5 crore, interest-free, no-term related-party loan sits, undisclosed in one part of the same Annual Report that discloses it clearly in another. The desk is not treating this as a reason to discount the company's growth, but it is not nothing either.
The valuation gap against the parent's own multiple is real and unexplained by growth alone. A 2.25x P/E premium over a listed, audited, continuously-priced parent is the sharpest number in this piece, and the desk is naming it rather than letting the growth story crowd it out.
The desk's position : the growth and the valuer's price argue for a fair-to-attractive entry point in isolation; the related-party contradiction and the parent-multiple gap argue for real caution before sizing a position aggressively. The one variable that would most improve this view: a corrected, consistent related-party disclosure in the FY27 Annual Report, resolving the CARO-versus-Note-49(iv) contradiction one way or the other. The one variable that would most concern the desk: if FY27 disclosures show the related-party loan balance growing further without a stated repayment plan, or the parent's own promoter pledge percentage rising materially from the 44.74% currently on record.
What This Means, By Situation
If you already hold this position : Watch the FY27 Annual Report specifically for how the related-party loan to KPI Green Energy Limited is disclosed, whether the CARO-versus-Note-49(iv) contradiction resolves, whether the balance grows or shrinks, and whether repayment terms are finally specified. Also worth tracking: the DEK and Mavericks Green Energy Limited acquisition's completion, and any RHP filing that would trigger the CCPS conversion.
If you're evaluating a first position : The entry question is not whether the growth is real, the primary filings support that clearly, and the registered valuer's price gives you a real, dated benchmark to weigh the current desk price against. The harder question is whether the 2.25x multiple premium over the parent's own listed P/E, and the unresolved related-party disclosure contradiction, change your sizing or timing.
If you're advising a client on this : The single fact most worth surfacing unprompted is the CARO-versus-Note-49(iv) contradiction on the ₹214.5 crore related-party loan, since it is the kind of finding a client is unlikely to encounter without reading both the auditor's CARO annexure and the notes to the financial statements side by side, unlike the headline growth numbers or the parent-company relationship, which are visible in any summary.
FAQs
What is the Sun Drops Energia Limited unlisted share price today?
As of this piece's 19 September 2026 publish date, the Sun Drops Energia unlisted share price is quoted at ₹298 per share on Priveq's desk, a 15.1% discount to the ₹351.02 registered-valuer benchmark set in August 2026. Desk prices move; talk to the desk for the current quote before any transaction.
Why is Sun Drops Energia trading at a premium to KPI Green Energy?
At ₹298, Sun Drops Energia trades at an implied P/E of 26.63x FY26 earnings, roughly 2.25 times the 11.86x multiple its listed parent, KPI Green Energy, commands on the open market. Sun Drops grew revenue 58.8% and PAT 89.4% in FY26, faster than the parent's own growth, but the desk is not calling the full 2.25x gap justified by growth alone; it remains an open, unexplained valuation premium.
Is Sun Drops Energia a subsidiary of KPI Green Energy?
Yes. KPI Green Energy Limited (BSE: 542323, NSE: KPIGREEN) holds 65.87% of Sun Drops Energia Limited, confirmed directly in both companies' own FY26 filings. KPI Green Energy's own FY26 consolidated results explicitly name Sun Drops as one of its "3 subsidiaries and 6 wholly owned SPVs."
Is Sun Drops Energia planning an IPO?
No DRHP filing has been found for Sun Drops Energia Limited as of this piece's publish date. However, an August 2026 EGM notice discloses that Compulsorily Convertible Preference Shares issued as part of a related-party acquisition convert to equity "within 12 months of allotment... or filing of Red Herring Prospectus (RHP) with SEBI, whichever is earlier," language that indicates an IPO is a live, board-contemplated possibility, not confirmation that one is imminent.
How does Sun Drops Energia's valuation compare to KPI Green Energy?
At Priveq's ₹298 desk price, Sun Drops trades at approximately 26.6 times FY26 earnings, versus KPI Green Energy's own listed multiple of approximately 11.9 times its FY26 consolidated earnings, a gap of roughly 2.25 times. This is a real, currently-unexplained valuation premium the desk states plainly rather than smoothing over.
Does Sun Drops Energia have any pending legal matters?
WRIT petitions are pending against District Collector orders approving a transmission-line right-of-way through petitioners' land in Bharuch, Gujarat. Per the company's own legal counsel, cited in its FY26 Annual Report, these petitions are not considered legally tenable, and the financial impact is not quantifiable.
What is the related-party loan contradiction in Sun Drops Energia's Annual Report?
The FY26 Annual Report's CARO Annexure discloses ₹220.68 crore in loans to group companies with no stipulated repayment schedule, including ₹214.49 crore owed by parent KPI Green Energy Limited. Note 49(iv) of the same financial statements states the company has made no such loans. Both cannot be true; the desk treats this as an open, unresolved discrepancy in the company's own disclosures.
What We Can And Cannot Stand Behind
Primary-sourced and verified directly, cross-checked across multiple independent points:
All FY25-FY26 financial figures (Balance Sheet, P&L, Cash Flow Statement, Statement of Changes in Equity, and Notes, including the full Note 45 Ratio Analysis), from the company's own FY26 audited financial statements, with the auditor (K A Sanghavi & Co LLP) issuing an unmodified opinion
The company's shareholding structure, including KPI Green Energy Limited's 65.87% holding and Dr. Faruk G. Patel's 13.13% holding, from Note 44 (Related Party Transactions) and the shareholding schedule of the FY26 financial statements, plus the pre/post-issue shareholding tables in the 21 August 2026 EGM notice
KPI Green Energy Limited's identification of Sun Drops Energia as a consolidated subsidiary, its own FY26 consolidated and standalone financial results (revenue, PAT, EPS, Debt-Equity ratio, CWIP), and its FY26 dividend recommendation, from KPI Green Energy's own audited results filed with BSE and NSE under Regulation 33/52, dated 6 May 2026
KPI Green Energy's live share price (₹285) and the resulting parent-multiple comparison, cross-checked between the company's own FY26 audited diluted EPS (₹24.04) and an independent aggregator (Screener), both converging on the same order of magnitude, as of 18 September 2026
KPI Green Energy's promoter shareholding (49.40%) and pledge percentage (44.74% of promoter holding, 22.10% of total shares, ≈₹1,739.29 crore), from KPI Green Energy's own NSE shareholding-pattern disclosure, most recent quarter on record as reviewed 18 September 2026
The registered valuer's ₹351.02 per-share price for the DEK and Mavericks Green Energy Limited acquisition, the CCPS terms including the RHP-linked conversion trigger, and Dr. Faruk G. Patel's personal subscription to the CCPS, from the company's own EGM notice dated 21 August 2026
Sun Drops Energia's ICRA credit rating ([ICRA]A(CE) (Positive), dependent on KPI Green Energy's corporate guarantee; [ICRA]A- without it), rated capacity (~8 MWAc IPP, ~13.5 MW hybrid), and CPP/EPC order book (~₹560 crore as of March 2025), from ICRA's own rating rationale dated 31 July 2025
The direct contradiction between CARO Annexure A Clause III (₹220.68 crore in related-party loans with no stipulated repayment terms, ₹214.49 crore of it owed by KPI Green Energy Limited) and Note 49(iv) (stating no such loans exist), both read directly from the same FY26 Annual Report
The pending WRIT petition litigation and the bank stock-statement reconciliation gaps, from Note 48 and the CARO Annexure of the FY26 Annual Report respectively
Indicative or derived, labeled as such : The ₹2,584.6 crore implied valuation and the 26.6x/26.63x P/E at Priveq's desk price are the desk's own arithmetic on the stated desk price and the company's audited EPS. The 2.25x parent-multiple comparison and the 15.1% discount-to-valuer-price figure are the desk's own derived calculations from the underlying primary-sourced figures, not company- or valuer-stated comparisons.
Could not be confirmed, flagged as open :
Which of the two contradictory statements in the FY26 Annual Report, CARO's disclosure of the related-party loan or Note 49(iv)'s denial of it, reflects the company's actual position; the desk has no basis to resolve this and is not speculating
The capacity and order-book figures are dated to ICRA's 31 July 2025 rating action; the desk has not independently confirmed whether capacity or order book have changed materially since
A current (post-June 2025) figure for KPI Green Energy's promoter pledge could not be independently confirmed beyond the NSE-sourced figure cited above; the company's own June 2026 shareholding-pattern PDF was not accessible to the desk due to access restrictions
The Board's Report and MD&A sections of Sun Drops Energia's own Annual Report were not available to the desk; this piece is built from the audited financial statements, notes, auditor's report, and the company's own EGM notice, not from Board's Report narrative disclosures
The specific reasons behind the quarterly bank stock-statement reconciliation gaps disclosed in the CARO Annexure, beyond the company's own note reference (Note 49(v))
The full mechanics and timeline of the DEK and Mavericks Green Energy Limited acquisition's completion, which was still pending as of the EGM notice date
Talk to the desk : WhatsApp +91 82874 66698 | support@priveq.in | View Sun Drops Energia Limited on the Priveq Marketplace
Disclaimer : This piece reflects Priveq India's (Priveq Investech Private Limited, Priveq.in) own research, based on primary filings, regulatory disclosures, and the companies' own audited financial statements, EGM notice, and other investor materials as detailed above. It is not investment advice, and does not allege any wrongdoing, misstatement, or violation by Sun Drops Energia Limited or KPI Green Energy Limited; the disclosure contradiction, litigation, and other findings noted in this piece are read directly from the companies' own public disclosures and are presented factually, not as an accusation. Priveq Investech Private Limited is not registered with the Securities and Exchange Board of India (SEBI) as a stock broker, investment adviser, or research analyst. This piece is independent desk research and commentary, not "research" as defined under the SEBI (Research Analysts) Regulations, 2014, and should not be construed as investment advice from a SEBI-registered entity. Priveq transacts as a named counterparty in the unlisted shares discussed here, including Sun Drops Energia Limited, and may hold or deal in these shares before, during, or after publication; our commercial interest and the views in this piece sit in the same place, and should be weighed accordingly. Desk prices are indicative, subject to change without notice, and should be confirmed directly with the desk before any transaction. Unlisted securities are illiquid, carry a high risk of loss, and may be difficult to value or sell; prices move sharply and without notice. Readers should independently verify all figures against the companies' own filings and consult qualified financial and legal advisors before transacting. Past performance and price appreciation referenced here are not indicative of future results.