

The Short Version
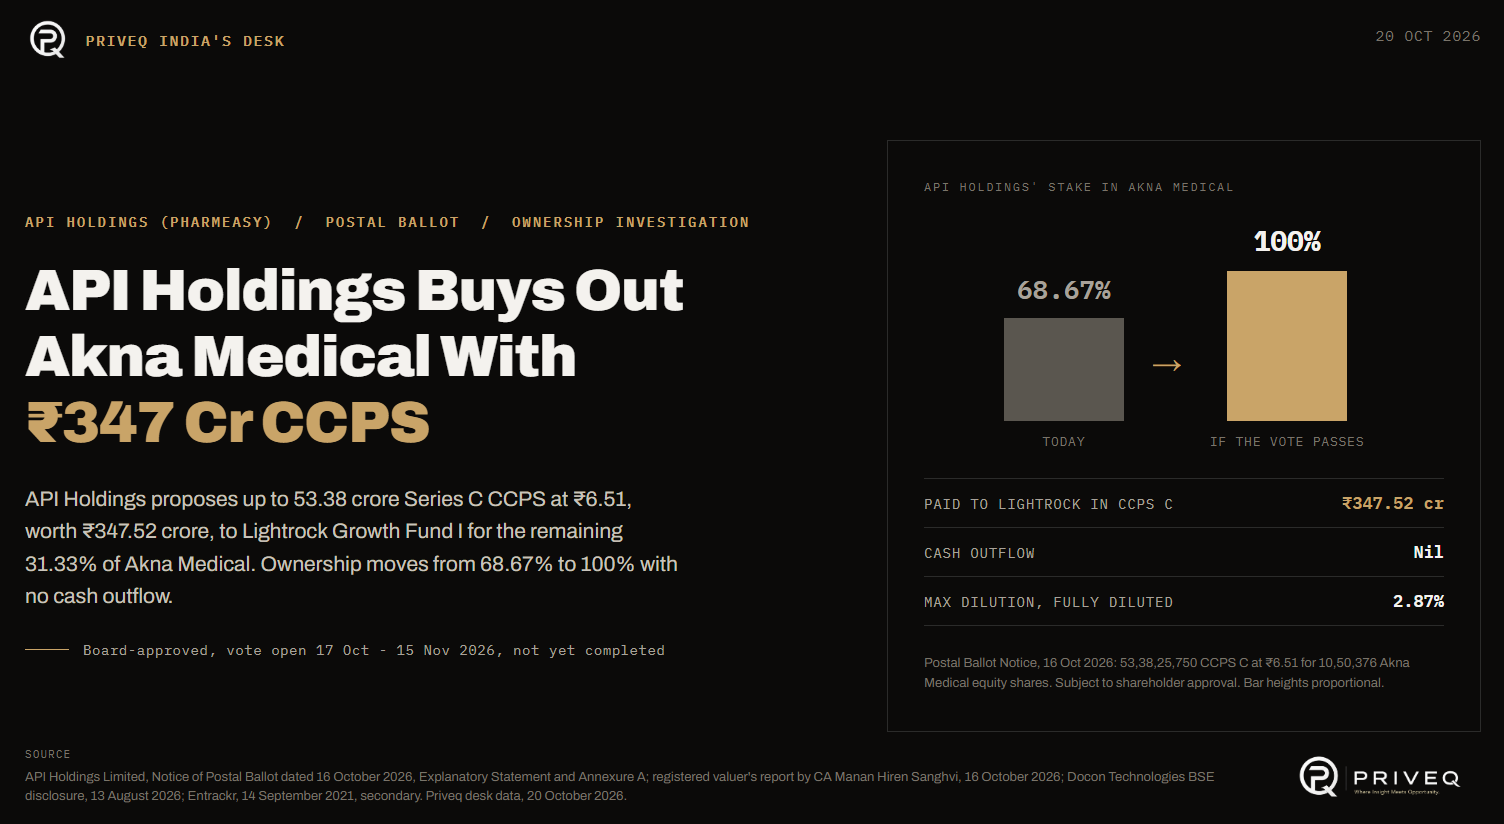
API Holdings Limited, the parent company of PharmEasy, issued a Postal Ballot Notice on October 16, 2026, seeking shareholder approval to issue up to 53.38 crore Series C CCPS worth approximately Rs. 347.52 crore to Lightrock Growth Fund I, as non-cash consideration for the remaining 31.33% stake in Akna Medical Private Limited. This takes API Holdings' ownership of Akna Medical from 68.67% to 100% without any cash outflow, instead diluting existing shareholders by roughly 2.87% on a fully diluted basis once all the Series C CCPS are converted into equity shares. It is the second time this specific stake has changed hands entirely in equity rather than cash: the original 68.67% position was itself acquired in an all-stock transaction back in 2021.
Company: API Holdings Limited (parent company of PharmEasy)
Sector: Healthcare e-commerce, digital pharmacy and diagnostics platform (Priveq category: Consumer & Healthcare)
Event: Postal Ballot Notice, Series C CCPS preferential issue to Lightrock Growth Fund I, as a share swap for Akna Medical's remaining minority stake
Event date: October 16, 2026 (Board approval April 24, 2026; Share Subscription and Purchase Agreement dated September 16, 2026)
Deal terms: Up to 53,38,25,750 CCPS C at Rs. 6.51 per share (Rs. 347.52 crore aggregate), non-cash consideration for Lightrock's 31.33% stake in Akna Medical Private Limited
Primary metric affected: Akna Medical ownership (68.67% to 100%); API Holdings' fully diluted share count (+2.87% at maximum issue); no change of control, disclosed explicitly in the notice
E-voting window: October 17, 2026 to November 15, 2026; results due on or before November 22, 2026
Desk price: Rs. 7.25 per share as of October 20, 2026 (Priveq Marketplace quote; indicative, reflects unlisted secondary market activity, not an independent Priveq valuation)
Valuation lens (derived by Priveq at the desk price): implied API Holdings equity value of ~Rs. 11,744 crore at the Rs. 6.51 CCPS valuation-report price versus ~Rs. 13,079 crore at the Rs. 7.25 desk price; roughly 1.77x to 1.98x EV/Revenue against FY26 consolidated revenue (P/E not used as the primary lens, the group remains net-loss-making at the consolidated level)
Primary source: API Holdings Limited, Notice of Postal Ballot dated October 16, 2026, issued under Sections 108 and 110 of the Companies Act, 2013
Identifiers: CIN U60100MH2019PLC323444, as stated on the notice. An ISIN of INE0DJ201029 appears on third-party unlisted-share listings for API Holdings; this has not been checked against a primary source and is not used elsewhere in this note.
Status: Board-approved, notice issued, shareholder vote open; not yet completed as of October 20, 2026.
For the live desk price and company snapshot, see API Holdings Limited (PharmEasy) Unlisted Shares on Priveq's Marketplace
What The Postal Ballot Notice Actually Says
API Holdings' Board approved the proposed transaction at its meeting on April 24, 2026, subject to shareholder approval (Item No. 1, Explanatory Statement, Postal Ballot Notice dated October 16, 2026). The transaction itself is contemplated under a Share Subscription and Purchase Agreement dated September 16, 2026, executed among API Holdings, Akna Medical and Lightrock Growth Fund I S.A., SICAV-RAIF ("LGF").
Under the special resolution (Item No. 1, read with Sections 23(1)(b), 42, 55 and 62(1)(c) of the Companies Act, 2013), API Holdings seeks consent to issue and allot up to 53,38,25,750 Series C Compulsorily Convertible Preference Shares (CCPS C) to LGF, on a preferential basis by way of private placement, for consideration other than cash, in exchange for the 10,50,376 equity shares of Akna Medical that LGF currently holds.
Key Terms Of The Proposed CCPS C Issue
Particular | Detail |
|---|---|
Issuing company | API Holdings Limited |
Proposed allottee | Lightrock Growth Fund I S.A., SICAV-RAIF |
Security | Series C Compulsorily Convertible Preference Shares (CCPS C) |
Maximum number of CCPS | 53,38,25,750 |
Face value per CCPS | Rs. 1 |
Issue price per CCPS | Rs. 6.51 (including Rs. 5.51 premium) |
Aggregate issue value | Approximately Rs. 347,52,05,632.50 |
Purpose | Acquisition of 10,50,376 Akna Medical equity shares (31.33% stake) |
Valuation basis | Report dated Oct 16, 2026 by CA Manan Hiren Sanghvi, Registered Valuer (IBBI/RV/06/2025/15846); valuation date Sep 30, 2026 |
Allottee category | Body corporate, non-resident entity (Luxembourg-domiciled SICAV-RAIF fund) |
No change of control, no promoters diluted: API Holdings states explicitly in Annexure A of the notice that no change in control occurs, and that the company has no promoters, so this dilution falls entirely on the existing non-promoter cap table.The notice is explicit on two points worth stating plainly: "No change in control shall occur consequent to the Private Placement" (Annexure A, item r), and API Holdings "does not have promoters" (Annexure A, item l), so there is no promoter-dilution angle to this transaction, only the proportionate dilution to the existing non-promoter cap table.
The Second All-Stock Swap For The Same Asset
This is not API Holdings' first time acquiring Akna Medical in equity rather than cash. Per API Holdings' own disclosures referenced in a BSE corporate filing dated March 31, 2023, Akna Medical has been a subsidiary of the group since September 2, 2021. Contemporary reporting on the original transaction (VCCircle, September 2021) described it as an all-stock deal in which PharmEasy's parent acquired the Lightrock-backed hospital supply-chain business Aknamed. Priveq could not independently verify the exact consideration structure of the 2021 transaction against a primary filing, so this detail is treated as secondary-sourced, not confirmed to the same standard as the current notice.
A separate secondary estimate (mind2markets) puts the original 2021 valuation of Akna Medical at approximately Rs. 700.7 crore. That figure is not independently confirmed and should be read as an estimate, not a disclosed fact.
What is new and directly computable from this notice: the current transaction implies a 100% equity value for Akna Medical of approximately Rs. 1,109 crore, derived by Priveq from the disclosed consideration (Rs. 347.52 crore for a 31.33% stake, so Rs. 347.52 crore / 0.3133). If the 2021 estimate is anywhere close to right, that is roughly a 58% increase in Akna Medical's implied value over five years, a Priveq-derived comparison that rests on an unverified 2021 baseline and should be read with that caveat attached.
Akna Medical's Implied Value, 2021 Versus 2026
Period | Implied 100% equity value | Source |
|---|---|---|
2021 (original acquisition, API Holdings to 67.3%) | ~Rs. 1,060 crore (named estimate) | Entrackr/Fintrackr, Sept 14, 2021, citing regulatory filings for the underlying share count and price |
2026 (this CCPS swap, API Holdings to 100%) | ~Rs. 1,109 crore | Priveq-derived from disclosed consideration, Postal Ballot Notice |
The real finding : Akna Medical's implied value has barely moved in five years. The ~4.6% difference between Entrackr's Rs. 1,060 crore 2021 estimate and this transaction's Rs. 1,109 crore implied value is within the margin of two different estimation methods, not a meaningful re-rating either way. Both figures are estimates: the 2021 number from a single named outlet's reporting, the 2026 number derived by Priveq from the postal ballot notice.
The Numbers Behind The Swap
Metric | Value | Basis |
|---|---|---|
Consideration for 31.33% Akna stake | Rs. 347.52 crore | Disclosed, Postal Ballot Notice |
Implied 100% equity value of Akna Medical | ~Rs. 1,109 crore | Derived: Rs. 347.52 cr / 0.3133 |
API Holdings fully diluted shares, pre-issue | 18,04,04,24,870 | Disclosed, Annexure A |
API Holdings fully diluted shares, post-issue (max) | 18,57,42,50,620 | Disclosed, Annexure A |
Dilution to existing shareholders | 2.87% | Disclosed and Priveq-verified |
Implied API Holdings equity value at CCPS issue price (Rs. 6.51, valuation date Sep 30, 2026) | ~Rs. 11,744 crore | Derived: 18,04,04,24,870 x Rs. 6.51 |
Implied API Holdings equity value at Priveq desk price (Rs. 7.25, as of Oct 20, 2026) | ~Rs. 13,079 crore | Derived: 18,04,04,24,870 x Rs. 7.25 |
Why the ~11.4% gap between the valuation report and the desk price is worth noting, not alarming: the registered valuer's Rs. 6.51 price is dated to a September 30, 2026 valuation date, about three weeks before Priveq's own October 20, 2026 desk quote of Rs. 7.25. The gap runs with the desk price above the swap price, not below it, which is a materially different read from a swap priced under a company's own recent reference point.
There is an approximately 11.4% gap between the Rs. 6.51 valuation-report price (dated September 30, 2026) and Priveq's own Rs. 7.25 desk quote (as of October 20, 2026). That is a real move over three weeks, not noise, but it runs in the direction of the desk price being higher than the swap price, so it does not raise the kind of concern a swap priced below a company's own recent reference point would. It is worth watching whether the gap narrows or widens as the CCPS issue moves toward a shareholder vote, rather than treating either number as stale.
API Holdings' sector fit argues for a revenue multiple over a P/E here: the group remains net-loss-making at the consolidated level (a loss of Rs. 520.3 crore in FY26, per its own annual report as cited in secondary reporting), even though EBITDA turned positive. Against FY26 consolidated revenue of Rs. 6,618.5 crore, and with the company now debt-free (see below), the implied range above works out to roughly 1.77x to 1.98x EV/Revenue. Priveq has not independently pulled the FY26 annual report to confirm these figures and flags them as secondary-sourced in the stand-behind section below.
Why A Share Swap Instead Of Cash, And What It Signals
API Holdings states its own rationale plainly in the notice: "the Company shall purchase / acquire 10,50,376 equity shares of Akna held by LGF and in consideration thereof, issue and allot up to 53,38,25,750 CCPS C to LGF... The share swap structure, instead of cash consideration, enables the Company to acquire the aforesaid shares without any immediate cash outflow, thereby preserving its cash resources for business operations and other corporate requirements" (Explanatory Statement, Item No. 1).
Read in isolation, that is boilerplate. Read alongside API Holdings' other moves through 2026, it reads differently. In August 2026, API Holdings' wholly owned subsidiary Docon Technologies sold down part of its Thyrocare Technologies stake and used the proceeds, along with internal accruals, to repay the last Rs. 1,050 crore of API Holdings' term debt, a move independently confirmed through Thyrocare's own BSE disclosures (Thyrocare is listed, so this is a regulated counterparty's own filing, not just API Holdings' account of it). Docon's post-sale Thyrocare holding stood at a controlling 51.02%, so the group gave up neither control of Thyrocare nor took on fresh debt to fund the paydown.
Separately, per an October 5, 2026 Moneycontrol report, CEO Rahul Guha has said API Holdings is weighing a standalone IPO for the PharmEasy business versus a merger into listed-subsidiary Thyrocare, with the decision contingent on the core business (excluding Thyrocare) reaching profitability by around September 2027. Both options remain open, by management's own account, and neither has been formally filed or announced as of this notice.
Priveq is treating that IPO-versus-Thyrocare-merger question as a separate story that deserves its own piece once there is a firmer signal, a fresh DRHP filing, a scheme of arrangement, or a formal management confirmation. It is noted here only as context for why a modest, non-cash, no-control-change transaction like the Akna Medical buyout is happening now: a company simplifying its cap table and cleaning up minority stakes in its own subsidiaries is a normal thing to do in the run-up to a listing decision of either kind, not necessarily a sign of continued cash strain. The CCPS rationale stated in the notice (cash preservation) stands on its own regardless of that broader context, but the context is worth having.
What Still Has To Happen
E-voting window: October 17, 2026 (9:00 AM IST) to November 15, 2026 (5:00 PM IST). Only shareholders as of the October 9, 2026 cut-off date are eligible.
Scrutiny: Bhavesh Chheda & Associates, Practising Company Secretaries, appointed as Scrutinizer.
Results: To be declared on or before November 22, 2026, on API Holdings' own website and CDSL's e-voting platform.
If passed: the resolution is deemed passed on the last day of e-voting (November 15, 2026), subject to the requisite votes in favour.
Allotment window: up to 12 months from the date the special resolution is passed (Rule 13(2)(e), Companies (Share Capital and Debentures) Rules, 2014).
Conversion: each CCPS C converts into one equity share at the holder's option at any time, or compulsorily on the earlier of the CCPS C Automatic Conversion Date or April 1, 2046, and automatically converts on a proposed IPO (Schedule I, clause 5.2).
As of this notice, the transaction is a board-approved proposal awaiting a shareholder vote, not a completed acquisition.
The Desk View
Two things are true about this transaction at once. Mechanically, it is small: a 2.87% maximum dilution, no change of control, and a consolidation of a five-year-old bolt-on business API Holdings already controlled at 68.67%. Taken purely on its own terms, this is routine cap-table housekeeping.
But the pattern matters more than any single data point here. This is the second time API Holdings has paid for the same asset entirely in equity rather than cash, and it comes within two months of the company clearing its last rupee of term debt by selling down part of a listed subsidiary stake it did not need to fully retain control of. A company doing both of those things in the same year, while its own CEO is on record weighing an IPO against a reverse merger into that same listed subsidiary, looks less like a business conserving cash out of necessity and more like one tidying its structure ahead of a decision it has not yet made public. Priveq's read: this is housekeeping with a purpose, not a distress signal, though the IPO-versus-merger choice itself remains genuinely open and unresolved as of October 2026.
FAQs
What did API Holdings just announce about Akna Medical?
API Holdings proposed issuing Rs. 347.52 crore of Series C CCPS to Lightrock Growth Fund I to buy its remaining 31.33% stake in Akna Medical. The deal would take API Holdings' ownership of Akna Medical from 68.67% to 100%, paid entirely in preference shares rather than cash, subject to shareholder approval by postal ballot.
Is the Akna Medical acquisition confirmed yet?
No, it is still subject to shareholder approval. E-voting runs from October 17 to November 15, 2026, with results due by November 22, 2026, and the resolution is deemed passed only if it clears on the last day of voting, subject to the requisite votes in favour.
Does this CCPS issue dilute existing API Holdings shareholders?
Yes, by up to approximately 2.87% on a fully diluted basis if the maximum 53.38 crore CCPS are issued and later converted into equity shares. API Holdings has disclosed this figure itself in the postal ballot notice, and Priveq has independently verified the arithmetic against the pre- and post-issue share counts in the same notice.
What is a CCPS, and why would a company pay with shares instead of cash?
A Compulsorily Convertible Preference Share is a preference share that must eventually convert into an ordinary equity share. Here, conversion happens at the holder's option, or compulsorily on the earlier of a specified automatic conversion date, an IPO, or April 1, 2046. Companies sometimes use CCPS instead of cash in an acquisition specifically to avoid an immediate cash outflow, which is the rationale API Holdings itself states in this notice.
Does this mean API Holdings is about to launch its PharmEasy IPO?
Not necessarily, and nothing in this notice says so directly. Separately, management has said it is weighing a standalone IPO against a merger with listed subsidiary Thyrocare, but has tied that decision to the core business reaching profitability by around September 2027, with no fresh DRHP filed or IPO date announced as of this notice.
Is Lightrock cashing out of Akna Medical through this deal?
No, Lightrock is not cashing out, it is converting its Akna Medical equity into API Holdings preference shares that remain unlisted and illiquid. Lightrock receives Series C CCPS that convert into API Holdings equity on the same terms as other CCPS holders, not cash, so its position moves from a minority stake in Akna Medical to a security in the larger, still-unlisted parent.
What's the risk in reading this CCPS swap as a sign of an imminent IPO?
The main risk is overreading a small, routine transaction as timing evidence for a decision management has explicitly called premature. Nothing in the postal ballot notice references an IPO or a Thyrocare merger, and the CEO has tied that broader decision to the core business reaching profitability by around September 2027, with no date, filing, or formal announcement made as of this note.
What We Can And Cannot Stand Behind
Primary-sourced and verified: every term of the CCPS C issue, the dilution math, the shareholding pattern, the e-voting timeline, and the stated rationale, all taken directly from API Holdings' Postal Ballot Notice dated October 16, 2026. Akna Medical's subsidiary-since date (September 2, 2021), corroborated via a BSE corporate filing. API Holdings' debt-free status and its retained 51.02% Thyrocare stake, corroborated through Thyrocare's own BSE disclosures, a regulated, listed counterparty's independent filing, not just API Holdings' own account.
Partially or indirectly corroborated: the 2021 Akna Medical acquisition being settled largely in API Holdings shares, independently reported by four outlets (Economic Times, KrASIA, M&A Critique, FirstWord HealthTech) rather than a primary filing Priveq could access directly; the ~Rs. 1,060 crore 2021 valuation estimate, sourced to a single named outlet (Entrackr's Fintrackr desk, citing regulatory filings for the underlying share count and price) rather than a company-disclosed figure; the identity of "Lightstone Fund" (2021) as the same investor as Lightrock Growth Fund I (2026), inferred from matching stake sizes, not independently confirmed; API Holdings' FY26 consolidated financials (revenue, EBITDA, net loss), sourced to secondary reporting that cites the company's own annual report rather than to that annual report directly; the IPO-versus-Thyrocare-merger optionality, reported as CEO Rahul Guha's comments via Moneycontrol, not a formal company filing or press release Priveq has independently read.
Could not be confirmed: whether the Rs. 6.51 CCPS issue price carries any deliberate relationship to IPO-prep valuation positioning, nothing in the notice suggests this and Priveq is not implying it; any timeline for an actual IPO filing or Thyrocare merger announcement; the precise FY26 cash and investment balances needed to state API Holdings' net cash position (and therefore a fully precise enterprise value) beyond the fact that it has no term debt outstanding.
Have a question about this note, or want to flag something we should verify further? Reach out to us on: +918287466698 or support@priveq.in
Disclaimer: This note is for informational purposes only and does not constitute investment advice. Unlisted and pre-IPO securities carry significant liquidity, valuation and regulatory risk. The proposed transaction described here is subject to shareholder approval and has not been completed as of the date of this note. Readers should conduct independent due diligence and consult a qualified financial advisor before making any investment decision.