

The Short Version
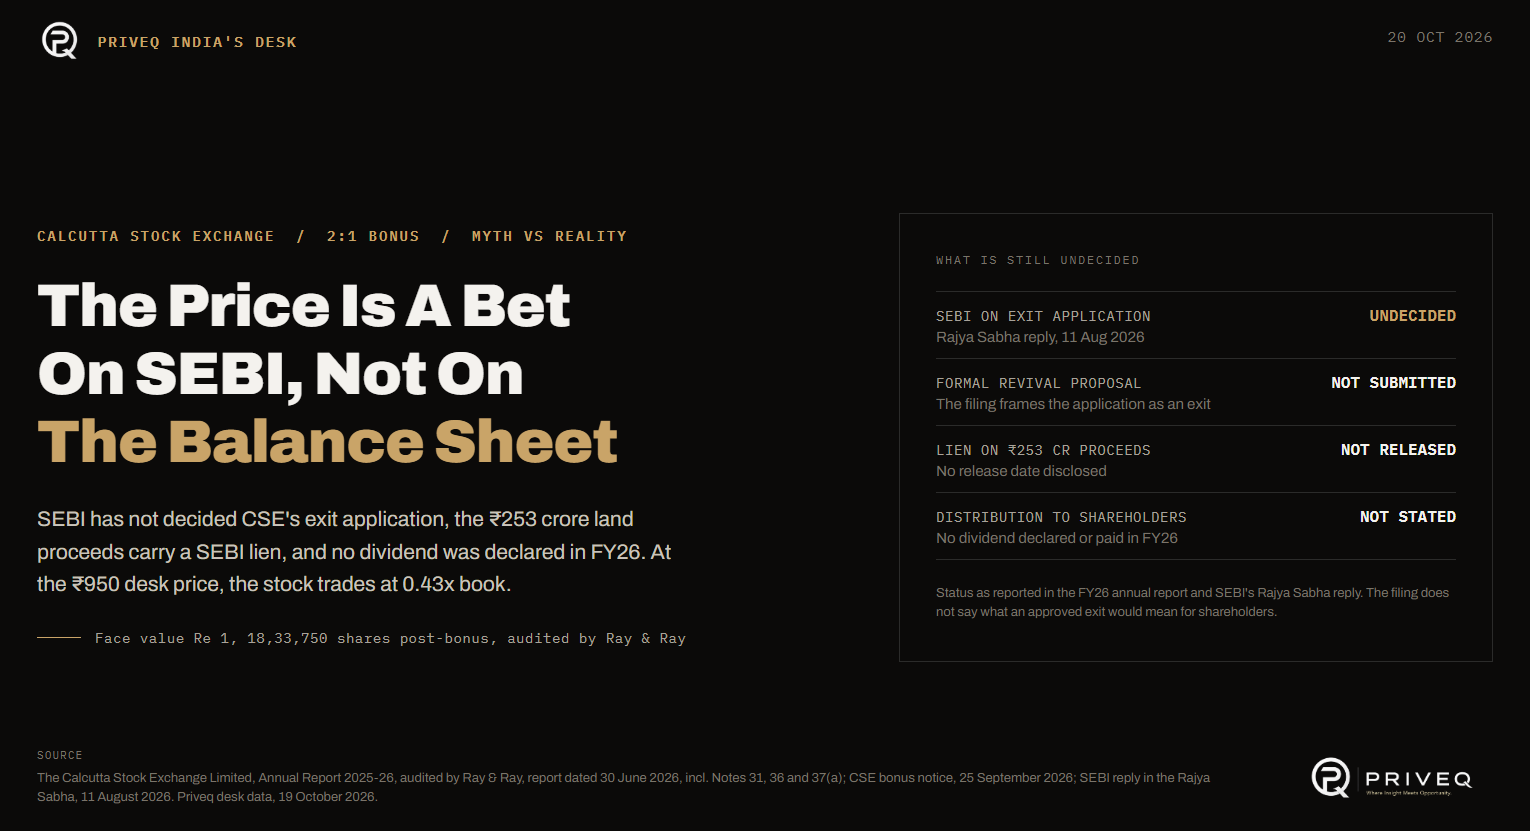
The Calcutta Stock Exchange's audited FY26 accounts (year ended March 31, 2026, auditor's report dated June 30, 2026) show net worth of Rs 402.10 crore, up from Rs 181.68 crore a year earlier, after a one-time Rs 249.28 crore profit on the sub-lease of land at E.M. Bypass. Excluding the land sub-lease, CSE's operations brought in Rs 5.13 crore against Rs 8.85 crore of expenses in FY26, so the book value behind the stock's rally rests on one asset sale rather than on the exchange running a business. CSE's 2:1 bonus (record date October 1, 2026) tripled the share count, which is why the desk price moved from about Rs 2,700 to Rs 950 (as of October 19, 2026 with no loss of value. SEBI has not decided CSE's exit application, and the sale proceeds carry a SEBI lien, so no dividend can be declared.
Event : FY26 audited financial statements and the 2:1 bonus
Date : June 30, 2026 (auditor's report); October 1, 2026 (bonus record date)
Source : The Calcutta Stock Exchange Limited, Annual Report 2025-26 (Balance Sheet, Statement of Profit and Loss, Independent Auditor's Report by Ray & Ray, UDIN 26056060ZGJFSD4871); CSE bonus notice dated September 25, 2026
Primary Metric Affected : Net worth, Rs 181.68 crore to Rs 402.10 crore (derived from disclosed share capital plus reserves and surplus)
What The FY26 Balance Sheet Actually Says?
CSE's Balance Sheet as at March 31, 2026 shows share capital of Rs 619 thousand and reserves and surplus of Rs 40,20,428 thousand. Added together, that is net worth of Rs 40,21,047 thousand, or Rs 402.10 crore, against Rs 181.68 crore at March 31, 2025. Total equity and liabilities, which equal total assets, stand at Rs 600.26 crore against Rs 401.31 crore a year earlier.
CSE Balance Sheet Snapshot, March 31, 2026 vs March 31, 2025
Rs crore | March 31, 2026 | March 31, 2025 |
|---|---|---|
Share capital | 0.06 | 0.06 |
Reserves and surplus | 402.04 | 181.62 |
Net worth (derived: share capital + reserves) | 402.10 | 181.68 |
Other long-term liabilities (Note 5) | 94.20 | 94.20 |
Other current liabilities | 97.08 | 101.88 |
Short-term provisions | 6.31 | 22.79 |
Total equity and liabilities | 600.26 | 401.31 |
Cash and bank balances | 250.52 | 66.74 |
Investments (current + non-current) | 94.39 | 102.14 |
Long-term loans and advances (Note 11) | 94.91 | 96.01 |
Property, plant and equipment | 27.73 | 27.83 |
Source : The Calcutta Stock Exchange Limited, Annual Report 2025-26, Balance Sheet as at March 31, 2026 (filed in INR thousand, converted to Rs crore by Priveq). Net worth is derived by Priveq as share capital plus reserves and surplus. Investments combine current (Rs 3,45,072 thousand) and non-current (Rs 5,98,870 thousand) investments for FY26.
The increase in reserves between the two year-ends is Rs 22,04,230 thousand, which matches to the rupee the FY26 profit before contributions to the Settlement Guarantee Fund and Investors' Service Fund. The whole rise in net worth is therefore FY26 profit, with no dividend deducted.
Where The FY26 Profit Came From?
CSE's Statement of Profit and Loss for FY26 reports total income of Rs 270.11 crore, of which Rs 249.28 crore is "Profit from Sub-Lease of Land (Refer Note no-36)". The auditor's report draws attention to the same item under "Other Matter": CSE sub-leased a land parcel at E.M. Bypass for a consideration of Rs 25,30,000 thousand (Rs 253.00 crore) and recognised a profit of Rs 24,92,818 thousand, which the auditor says "constitutes a significant portion of profit for the year ended 31st March 2026 and has materially influenced the Company's financial performance during the year."
CSE FY26 vs FY25 Statement of Profit and Loss, Rs Crore
Rs crore | FY26 | FY25 |
|---|---|---|
Revenue from operations | 5.13 | 11.36 |
Profit from sub-lease of land (Note 36) | 249.28 | 0.00 |
Other income | 15.70 | 14.69 |
Total income | 270.11 | 26.05 |
Total expenses | 8.85 | 40.15 |
Profit/(loss) before tax and contribution to SGF and ISF | 261.26 | (14.10) |
Total tax expense | 40.84 | 2.96 |
Profit/(loss) after tax before SGF and ISF contribution | 220.42 | (17.06) |
Contribution to SGF and ISF (net of tax) | 4.85 | 4.81 |
Profit/(loss) after tax | 215.57 | (21.87) |
EPS, basic and diluted (Rs, pre-bonus basis, as reported) | 3,526.74 | (357.85) |
EPS adjusted for the 2:1 bonus (Rs, derived) | 1,175.58 | (119.28) |
Source: Annual Report 2025-26, Statement of Profit and Loss for the year ended March 31, 2026 (INR thousand converted to Rs crore by Priveq). SGF = Settlement Guarantee Fund; ISF = Investors' Service Fund. The bonus-adjusted EPS is derived by Priveq (reported EPS divided by 3).
FY25 is a useful contrast: CSE booked a net loss of Rs 21.87 crore, with total expenses of Rs 40.15 crore that included a Rs 20.95 crore provision for voluntary retirement. FY26 expenses fell to Rs 8.85 crore, of which employee benefits are Rs 2.17 crore against Rs 11.42 crore in FY25.
What The Exchange Earns Without The Land Sale?
CSE's revenue from operations in FY26 was Rs 5.13 crore, against total expenses of Rs 8.85 crore. That is a Rs 3.72 crore shortfall before any other income, derived by Priveq from the two disclosed lines. Other income of Rs 15.70 crore covers it; the Cash Flow Statement lists interest on fixed deposits (Rs 10.56 crore), interest on bonds (Rs 2.99 crore) and dividend income from investments (Rs 0.64 crore) among the non-operating items.
Taking the land profit out of the pre-tax figure gives Rs 11.98 crore (Rs 261.26 crore less Rs 249.28 crore), derived by Priveq. That is what the exchange earned before tax and before the SGF and ISF contributions without the sub-lease, and it depends on interest income on the cash pile rather than on any exchange activity.
What The Rs 402 Crore Is Made Of?
CSE's Rs 600.26 crore of assets are mostly cash, investments and receivables, not operating assets. Cash and bank balances are Rs 250.52 crore, investments (current plus non-current) Rs 94.39 crore, and long-term loans and advances Rs 94.91 crore. Property, plant and equipment is Rs 27.73 crore. The Cash Flow Statement shows Rs 25,30,000 thousand received from the sub-lease of land in FY26 as an investing inflow.
Three items sit against that net worth and keep it from being freely available to shareholders:
The Settlement Guarantee Fund liability. Note 31(ii) states that "Other Long Term Liabilities" includes Rs 9,41,994 thousand (Rs 94.20 crore) of contributions received from members after earlier payment defaults, refundable only out of money recovered from the defaulters.
The matching receivable. Note 31(i) states that "Loans and Advances" includes an identical Rs 9,41,994 thousand due from members on account of earlier settlements, with recovery suits for Rs 9,31,053 thousand against 15 defaulting members, which are sub-judice. The auditor describes the recoverability as "not ascertainable" at this stage.
The SEBI lien and the dividend position. The Rs 253 crore land-sale proceeds carry a SEBI lien, and the auditor's report (clause (v) of the Report on Other Legal and Regulatory Requirements) confirms that no dividend was declared or paid during the year.
The auditor's report says that, because the Rs 94.20 crore receivable has an identical liability on the other side, "no impact on the financial position of the Exchange is foreseen." That is an accounting offset, not a recovery.
The 2:1 Bonus And The Rs 2,700 To Rs 950 Move
CSE's face value is Re 1, with 6,11,250 shares in issue before the bonus (Note 3, Share Capital). CSE's notice of September 25, 2026 fixed October 1, 2026 as the record date for a 2:1 bonus, two bonus shares for every share held, taking the count to 18,33,750 shares. There was no split; the face value stays at Re 1.
Because the share count tripled, a price must be compared on the same basis before reading any movement into it. Priveq's desk observations, restated on both bases :
Reference point | Price as observed | Basis | Pre-bonus equivalent (Rs) | Post-bonus equivalent (Rs) | Implied market cap (Rs crore) | Price to book (x) |
|---|---|---|---|---|---|---|
Before the revival news | about Rs 900 | Pre-bonus | 900 | 300 | 55.01 | 0.14 |
Days before the bonus record date | about Rs 2,700 | Pre-bonus | 2,700 | 900 | 165.04 | 0.41 |
Priveq desk price as of October 19, 2026 | Rs 950 | Post-bonus | 2,850 | 950 | 174.21 | 0.43 |
Prices are Priveq desk observations of unlisted market activity, not exchange prices, and the earlier two are approximate. Share count: 6,11,250 before the bonus, 18,33,750 after the 2:1 bonus (record date October 1, 2026), face value Re 1. Price to book uses the March 31, 2026 net worth of Rs 402.10 crore in every row for comparability; it is not the book value that stood at the time of the earlier prices.
The move from about Rs 2,700 to Rs 950 is the bonus arithmetic, not a fall: Rs 950 post-bonus equals Rs 2,850 pre-bonus, slightly above the Rs 2,700 level. Against the pre-revival price of about Rs 900 pre-bonus, the current desk price is roughly 3.2 times higher on a like-for-like basis (Rs 2,850 divided by Rs 900, derived).
Book Value Versus Price
For an exchange, a cash-heavy balance sheet with little operating income, price to book is a better lens than P/E. Priveq's arithmetic, using the March 31, 2026 net worth and the post-bonus share count:
Net worth Rs 40,21,047 thousand ÷ 18,33,750 post-bonus shares = Rs 2,192.8 per share (derived). Rs 950 desk price (as of October 19, 2026) ÷ Rs 2,192.8 = 0.43 times book (derived). On the pre-bonus count the same figures are Rs 6,578.4 per share of book value against Rs 2,850 (the equivalent price), which is the same 0.43 times.
On that basis the desk price implies a market capitalisation of Rs 174.21 crore against Rs 402.10 crore of book value. P/E is the figure most readers will reach for, and on FY26 reported EPS adjusted for the bonus (Rs 1,175.58) it works out to about 0.8 times as of October 19, 2026. Priveq does not treat that as meaningful, because the profit it divides into the price is dominated by a one-off land profit.
The gap between 0.43 times book and a full valuation is not a free discount. It sits where the balance sheet is encumbered or uncertain: proceeds under a SEBI lien, no dividend, a Rs 94.20 crore receivable matched by a refundable liability, and a regulatory path that has not been decided.
What The Auditor Flagged
Ray & Ray, Chartered Accountants, signed an unmodified opinion dated June 30, 2026 (UDIN 26056060ZGJFSD4871). The report carries two Emphasis of Matter points and one Other Matter paragraph, and does not modify the opinion on any of them.
Independent Auditor's Report, FY26: What Was Flagged
Item | Where | What it says |
|---|---|---|
Emphasis of Matter (i) | Note 31(i) | Rs 9,41,994 thousand receivable from members on account of default; recovery suits for Rs 9,31,053 thousand are sub-judice, so the extent of recoverability cannot be ascertained. An identical amount sits in the Settlement Guarantee Fund liability (Note 31(ii)), and no impact on the Exchange's financial position is foreseen. |
Emphasis of Matter (ii) | Note 37(a) | The Board applied for EXIT on February 18, 2025 and decided not to pursue court cases against SEBI regarding starting trading operations and setting up a clearing corporation. The Board is negotiating with SEBI; shareholder approval was obtained at the EGM of April 25, 2025; SEBI has appointed a valuer whose report has been submitted to SEBI, as informed by management. The accounts are prepared on a going-concern basis. |
Other Matter | Note 36 | Sub-lease of land at E.M. Bypass for Rs 25,30,000 thousand; profit of Rs 24,92,818 thousand recognised, a significant portion of FY26 profit that materially influenced financial performance. |
Source: Independent Auditor's Report, Ray & Ray, Chartered Accountants, dated June 30, 2026 (UDIN 26056060ZGJFSD4871). The opinion is unmodified in respect of all three matters.
The auditor's report adds one operational point in its audit-trail paragraph: the accounting software's audit trail records who modified a record and when the record was created, but overwrites previous information with the last modified version, and the database-level audit trail feature is not enabled.
Revival : What SEBI Has And Has Not Decided
CSE's own filing frames the pending application as an exit, not a restart. The auditor's Emphasis of Matter (ii) describes the Board's application for EXIT filed on February 18, 2025, and records that the Board decided not to pursue court cases against SEBI on restarting trading. The same note says the Company believes securities-market activities "will be undertaken either through its own Company or through Subsidiary Companies," and that the Company has sufficient resources to meet its future obligations.
On the regulator's side, SEBI's reply in the Rajya Sabha on August 11, 2026 recorded no decision on CSE's exit application, and CSE has not submitted a formal revival proposal. The filing does not say what an approved exit would mean for shareholders, how SEBI's valuer's report would be used, or when the lien on the sale proceeds would be released.
The Desk View
What's more resolved than before : CSE's net worth is now an audited, disclosed figure: Rs 402.10 crore, more than double the prior year. The bonus arithmetic is also settled: Rs 950 post-bonus is Rs 2,850 pre-bonus, so the price did not fall.
What's still open : SEBI's decision on the exit application; whether any revival proposal is formally submitted; when the Rs 253 crore sale proceeds are released from the lien; and what, if anything, can be distributed to shareholders.
Priveq's read : The book value is real, but it is one transaction deep, and the price is a bet on SEBI's decision, not on the balance sheet. At about 0.43 times book on the desk price (as of October 19, 2026), the market is already discounting how much of the Rs 402.10 crore is reachable by shareholders. The next real catalysts are a SEBI decision on the exit application, a formal revival proposal, or a release of the lien, whichever comes first. Priveq's desk price reflects unlisted market-driven activity, not an independent Priveq valuation call.
FAQs
What is the Calcutta Stock Exchange's net worth in FY26?
CSE reported a net worth of Rs 402.10 crore at March 31, 2026, up from Rs 181.68 crore a year earlier. This is share capital of Rs 619 thousand plus reserves and surplus of Rs 40,20,428 thousand from the audited Balance Sheet, and the whole increase is FY26 profit.
Is CSE's FY26 profit audited and final?
Yes, Ray & Ray signed an unmodified audit opinion on June 30, 2026, with two emphasis-of-matter points. They concern the Rs 94.20 crore receivable from defaulting members and the pending exit application to SEBI.
Should I be concerned that CSE's FY26 profit is mostly one land sale?
Yes, it is worth weighing. Of Rs 270.11 crore total income, Rs 249.28 crore is profit on sub-leasing land at E.M. Bypass, and the auditor itself says the profit "materially influenced" the year. Excluding it, CSE's pre-tax profit before SGF and ISF contributions was Rs 11.98 crore, which depended on Rs 15.70 crore of other income.
Did CSE's share price crash after the bonus?
No, the fall from about Rs 2,700 to Rs 950 reflects a 2:1 bonus tripling the share count, not lost value. Rs 950 post-bonus equals Rs 2,850 pre-bonus, slightly above the earlier level.
Is CSE trading below book value?
On Priveq's desk price of Rs 950 as of October 19, 2026, CSE trades at about 0.43 times its March 31, 2026 book value. That book value includes Rs 253 crore of sale proceeds under a SEBI lien, and no dividend was declared or paid in FY26.
Has SEBI approved CSE's exit or revival?
No decision has been reported: SEBI said in the Rajya Sabha on August 11, 2026 that CSE's exit application is undecided. CSE has also not submitted a formal revival proposal.
What We Can And Cannot Stand Behind
Primary-sourced and verified:
The Balance Sheet, Statement of Profit and Loss and Cash Flow Statement figures in this note, read from CSE's Annual Report 2025-26 (all figures in INR thousand in the filing, converted to Rs crore by Priveq).
The Independent Auditor's Report dated June 30, 2026: unmodified opinion, Emphasis of Matter points (i) and (ii), the Other Matter on Note 36, the clause (v) statement that no dividend was declared or paid, and the audit-trail disclosure.
Notes 31(i)-(iii), 36 and 37(a), as quoted from the auditor's report and notes.
CSE's face value of Re 1 and 6,11,250 shares (Note 3), and the 2:1 bonus with October 1, 2026 record date (CSE notice dated September 25, 2026).
SEBI's reply in the Rajya Sabha on August 11, 2026 on the exit application, and the SEBI lien on the sale proceeds.
Partially or indirectly corroborated:
The desk price trail (about Rs 900, about Rs 2,700, Rs 950): Priveq desk observations of unlisted trading, not exchange prices, and the two earlier figures are approximate.
Net worth, book value per share, price to book, market capitalisation, the Rs 11.98 crore pre-tax figure excluding the land sale and the Rs 3.72 crore operating shortfall: all derived by Priveq from disclosed figures, not stated by CSE.
Two reconciliation points Priveq could not close in the pages reviewed: share capital shows Rs 619 thousand against Rs 611.25 thousand from 6,11,250 shares at Re 1; and the Cash Flow Statement shows Rs 1,098 thousand of dividend paid in FY26 while the auditor states no dividend was declared or paid during the year. Both are small. The annual report's own text also labels the bonus "1:2" in one place; Priveq follows the parenthetical and the September 25, 2026 notice, which describe two bonus shares for each share held.
Could not be confirmed:
What an approved exit would mean for shareholders, or whether CSE intends a formal revival proposal.
When or whether the SEBI lien on the Rs 253 crore sale proceeds will be released.
How much of the Rs 94.20 crore receivable from defaulting members will be recovered.
The book value that stood at the time of the earlier desk prices, because the land sub-lease timing relative to those prices was not established.
Notes and pages of the annual report not reviewed by Priveq for this note.
Track CSE On Priveq
Current desk price for CSE unlisted shares is Rs 950 (post-bonus) as of October 19, 2026. For live pricing and to transact, see CSE on Priveq Marketplace.
Disclaimer
This note is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any security. Unlisted and pre-IPO shares carry risks including illiquidity, valuation uncertainty, and regulatory change. Figures are sourced as cited and are current only as of the dates stated; prices and regulatory positions can change without notice. Readers should conduct their own due diligence and consult a qualified advisor before making investment decisions.