

The Short Version
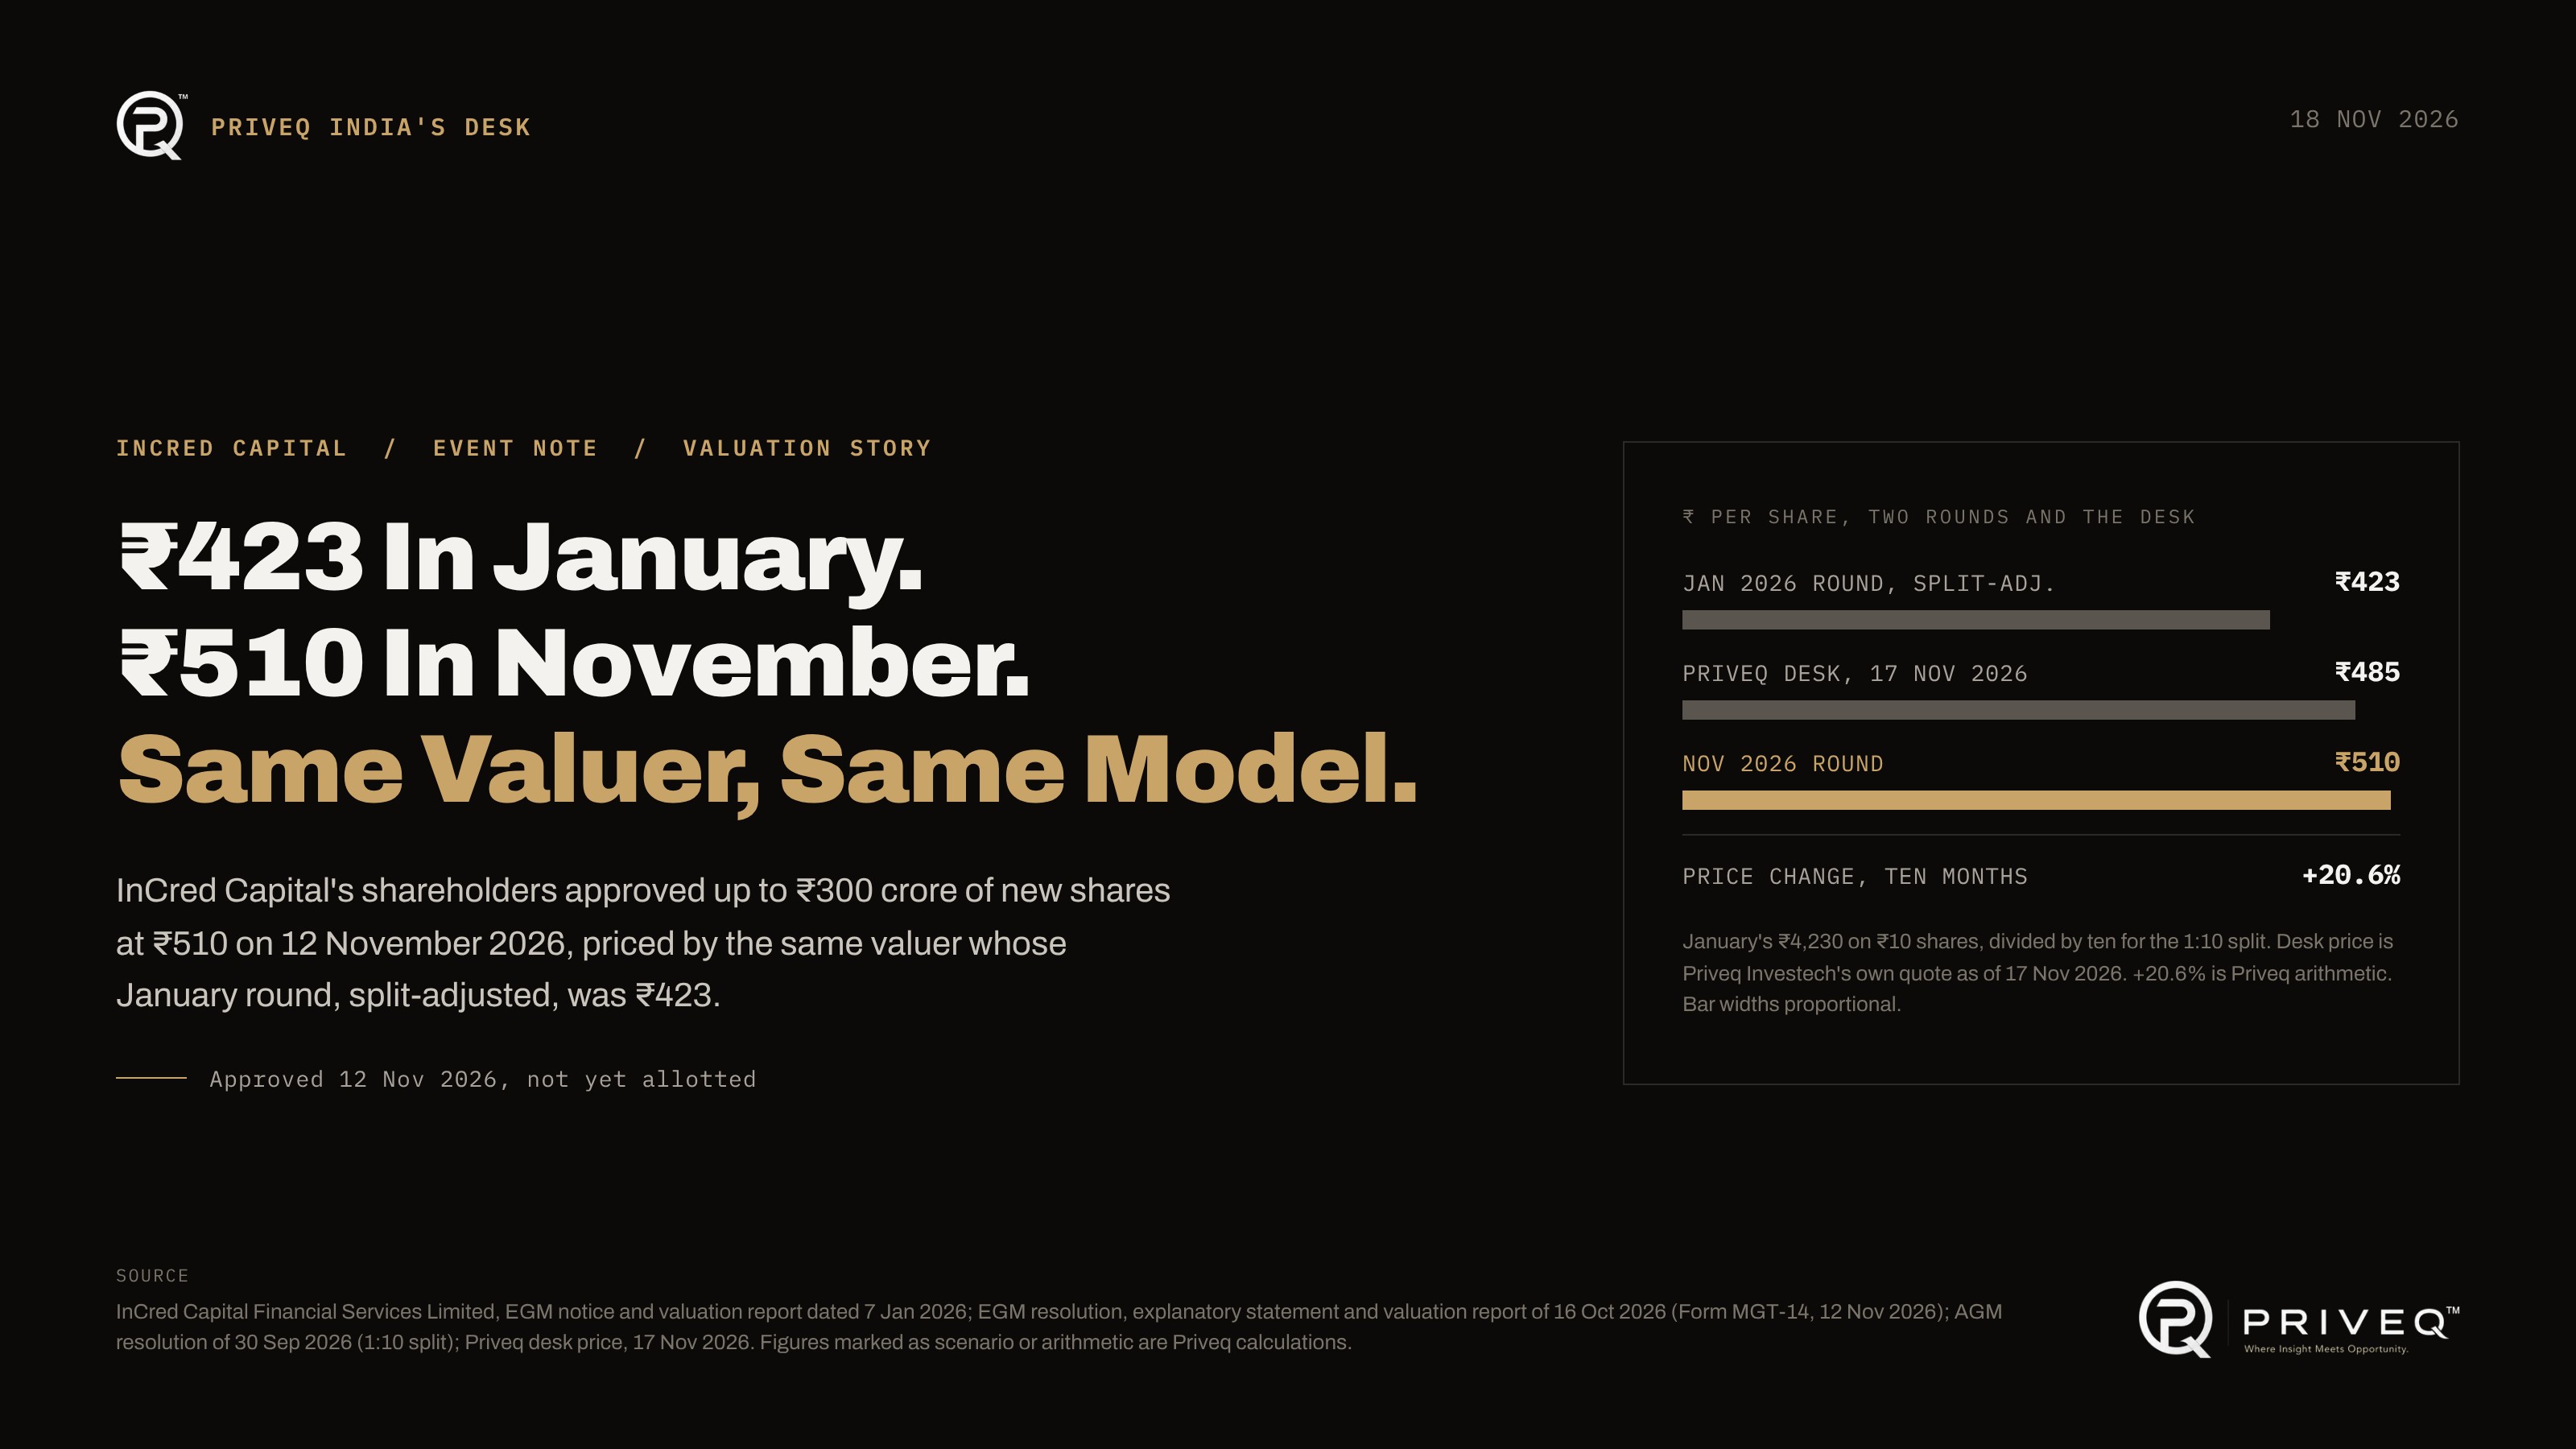
InCred Capital Financial Services Limited's shareholders approved on 12 November 2026 a private placement of up to 58,82,352 equity shares at Rs 510 each, up to Rs 300 crore, to 21 named investors, priced by a registered valuer's discounted cash flow (DCF) model as at 31 August 2026. In January 2026 the same valuer priced the company's last Rs 300 crore round at Rs 4,230 on the old Rs 10 shares, which is Rs 423 after the 1:10 split approved on 30 September 2026. The price is up 21% in ten months, and pre-money equity value up 33% to Rs 8,493 crore, while FY26 consolidated profit fell 63% to Rs 40.95 crore after a Rs 59.68 crore exceptional charge.
Event: Preferential issue of equity shares on a private placement basis
Date: Board approval 16 October 2026; special resolution at the EGM on 12 November 2026
Source: Certified special resolution, explanatory statement and valuation report, filed with Form MGT-14 on 12 November 2026
Primary Metric Affected: Valuation reference point (Rs 510 a share) and share count (+58,82,352)
This is InCred Capital, the group's investment banking, wealth and asset management company. It is not InCred Holdings Limited, the parent of the lending company InCred Financial Services, which has filed for an IPO. For the company profile, financials and the live desk price, see InCred Capital on the Priveq Marketplace.
What InCred Capital Is Issuing, and to Whom?
InCred Capital's board approved the issue on 16 October 2026, and members passed a special resolution at an extraordinary general meeting on 12 November 2026 at the registered office in Bandra Kurla Complex, Mumbai (EGM resolution and valuation report, pp. 1-5). The company filed the resolution with the Registrar the same day.
The Rs 510 private placement, as approved on 12 November 2026
Term | Detail |
|---|---|
Instrument | Equity shares of Rs 1 face value, preferential issue on private placement, for cash |
Number of shares (maximum) | 58,82,352 |
Issue price | Rs 510 (Rs 1 face value plus Rs 509 premium) |
Amount | Up to Rs 300 crore, in one or more tranches |
Proposed subscribers | 21 named investors, holding about 3.79% after the issue |
Promoter-linked subscriber | InCred Securities Services Private Limited, controlled by Bhupinder Singh; not classified as a promoter |
Objects | Business requirements, general corporate purposes and investment in subsidiaries |
Registered valuer | Aditi Mittal & Co (CA Aditi Mittal, IBBI/RV/07/2020/13690), report dated 16 October 2026 |
Valuation and relevant date | 31 August 2026 |
Approvals | Board on 16 October 2026; special resolution at the EGM on 12 November 2026 |
Source: InCred Capital Financial Services Limited, certified true copy of the special resolution passed at the EGM of 12 November 2026 and explanatory statement, items 1 to 17 and Annexure A (filed with Form MGT-14 on 12 November 2026). All disclosed.
Three details in the explanatory statement are worth stating exactly:
The founder is buying in through a separate company. InCred Securities Services Private Limited, which the statement says is controlled by Bhupinder Singh, promoter and director, intends to subscribe. It is not classified as a promoter, and no other promoter, director or key managerial person intends to subscribe (items 14 and 17).
The investor list is broad. The 21 named subscribers include a Category II alternative investment fund (Plutus Equity Investments), listed Graphite India Limited, several family trusts and individuals (Annexure A).
Nothing is allotted yet. The resolution permits allotment in one or more tranches, within 60 days of receiving each investor's money under Section 42(6), and the statement records no equity allotment in the current financial year (items 12 and 16).
The promoter's stake falls from 36.29% to 34.91% if the issue is fully subscribed, and he keeps all the warrants (Annexure C).
Shareholding before and after the Rs 510 issue (equity shares)
Holder group | Before (shares) | Before (%) | After (shares) | After (%) |
|---|---|---|---|---|
Promoter (individual) | 5,41,44,770 | 36.29 | 5,41,44,770 | 34.91 |
Private corporate bodies | 3,00,56,350 | 20.14 | 3,38,82,248 | 21.85 |
Foreign companies and body corporates | 92,49,050 | 6.20 | 92,49,050 | 5.96 |
Directors and relatives | 10,34,310 | 0.69 | 10,34,310 | 0.67 |
Indian public and HUF | 3,64,34,590 | 24.42 | 3,79,20,847 | 24.45 |
Others, including NRIs and trusts | 1,82,86,640 | 12.26 | 1,88,56,837 | 12.16 |
Total equity | 14,92,05,710 | 100.00 | 15,50,88,062 | 100.00 |
Source: EGM resolution of 12 November 2026, Annexure C. The promoter also holds all 8,33,333 warrants (83,33,330 shares after the split); 18,05,386 OCRPS sit with non-promoters. All disclosed.
Net read: a Rs 300 crore round with the founder's own vehicle in the book is a stronger price signal than a raise from strangers alone, but it is not an arm's-length price in the strict sense, because the promoter's side is on both sides of the table.
Two Rs 300 Crore Rounds, Ten Months Apart
This is InCred Capital's second Rs 300 crore placement of 2026. In January, shareholders approved up to 7,09,219 shares of Rs 10 at Rs 4,230 each (January EGM notice and valuation report, Item 1 and explanatory statement). The FY26 accounts confirm all 7,09,219 shares were issued during the year (FY26 annual report, standalone Note 17(b), PDF p. 55).
Two Rs 300 crore rounds ten months apart, same valuer (per-share figures adjusted for the 1:10 split)
Item | January 2026 round | November 2026 round |
|---|---|---|
Valuation date | 30 Nov 2025 | 31 Aug 2026 |
Report date | 7 Jan 2026 | 16 Oct 2026 |
Price per share (Rs 1 basis) | 423 (Rs 4,230 on Rs 10 face value) | 510 |
Pre-money equity value (Rs crore) | 6,363.91 | 8,493.30 |
Fully diluted shares (Rs 1 basis) | 15,04,46,850 | 16,65,65,970 |
Shares offered (Rs 1 basis) | 70,92,190 (7,09,219 on Rs 10) | 58,82,352 |
Amount | Rs 300 crore, fully allotted in FY26 | Up to Rs 300 crore, approved, not yet allotted |
Number of named subscribers | 8 | 21 |
Bhupinder Singh-controlled entity subscribing | Yes | Yes |
Source: EGM notice dated 7 January 2026 with valuation report dated 7 January 2026 (Item 1, explanatory statement, Annexures A to C and valuation report p. 10 and Annexure I); EGM resolution of 12 November 2026 with valuation report dated 16 October 2026 (Annexures A to C, report pp. 12 and 14-15); FY26 standalone Note 17(b), PDF p. 55, for the January allotment. Split-adjusted figures are Priveq arithmetic (pre-split figure x 10 shares, / 10 price).
On a like-for-like Rs 1 basis, the price has gone from Rs 423 to Rs 510, up 20.6%. The pre-money equity value has gone from Rs 6,363.91 crore to Rs 8,493.30 crore, up 33.5%. The two percentages differ because the share base also grew between the reports, through the January round itself and the OCRPS (optionally convertible redeemable preference shares) issued in the group merger, covered below.
Net read: the same valuer, using a DCF both times, the same 10% company-specific risk premium and the same 15% marketability discount, has marked InCred Capital up by a third in ten months. Over the same period, the audited FY26 numbers that sit between the two reports showed revenue doubling and profit falling sharply.
Inside the Rs 510 Valuation
Both reports value InCred Capital with a DCF on management's projections, then deduct a 15% discount for lack of marketability. The October report sets out the full bridge (valuation report, Annexure II, p. 15):
Present value of free cash flow to the firm, September 2026 to FY32: Rs 1,484.15 crore.
Terminal value at 3% growth: Rs 9,743.13 crore.
Enterprise value: Rs 11,227.28 crore, of which the terminal value is 86.8%.
Add cash of Rs 622.45 crore and Rs 2.19 crore due from ESOPs; deduct debt and debt-like items of Rs 1,859.82 crore: Rs 9,992.11 crore.
Less the 15% marketability discount of Rs 1,498.82 crore: Rs 8,493.30 crore, or Rs 509.91 on 16,65,65,970 fully diluted shares.
What changed inside the valuer's DCF between January and October 2026
Input | January 2026 report | October 2026 report |
|---|---|---|
Risk-free rate | 6.55% | 6.92% |
Beta | 0.29 | 0.60 |
Market return used | 13.55% | 12.11% |
Company-specific risk premium | 10.00% | 10.00% |
Cost of equity | 18.55% | 20.05% |
Discount rate (WACC) | 11.82% | 12.41% |
Terminal growth | 3.00% | 3.00% |
Discount for lack of marketability | 15.00% | 15.00% |
Cash treated as surplus (Rs crore) | 524.93 (30 Nov 2025) | 622.45 (31 Aug 2026) |
Debt deducted (Rs crore) | Not itemised in the report | 1,859.82 |
Terminal value as share of enterprise value | Not itemised in the report | 86.8% (Rs 9,743.13 crore of Rs 11,227.28 crore) |
Result per share (Rs 1 basis) | 423.00 | 509.91, rounded to 510 |
Source: Aditi Mittal & Co valuation reports dated 7 January 2026 (pp. 8-10) and 16 October 2026 (pp. 9-10 and Annexure II, p. 15). The terminal-value share and the split adjustment are Priveq arithmetic. Both reports rely on management projections that are not attached.
Between the two reports, the inputs moved against a higher price, not towards it: the beta used doubled from 0.29 to 0.60, the cost of equity rose from 18.55% to 20.05% and the discount rate from 11.82% to 12.41%. The value still rose by a third, so the increase must come from the projected cash flows themselves, which neither report attaches. Without the 15% discount, the October model gives Rs 599.89 a share (Priveq arithmetic).
Net read: the Rs 510 is a forecast-led number. With 86.8% of enterprise value in the terminal value and the projections not filed, the most useful check a reader can make is against the next audited year.
The Share Count, Reconciled
InCred Capital's share count has changed three ways in 2026: the January allotment, the OCRPS issued under the group merger, and the 1:10 split approved at the 30 September 2026 AGM, which turned each Rs 10 share into ten Rs 1 shares (AGM resolution). Every number below ties.
InCred Capital share count, reconciled (face value Rs 1)
Line | Shares | Basis |
|---|---|---|
Fully diluted at the January valuation (30 Nov 2025) | 15,04,46,850 | Disclosed 1,50,44,685 on Rs 10, x 10 |
Add: January round allotted in FY26 | 70,92,190 | Disclosed 7,09,219 on Rs 10 (FY26 Note 17), x 10 |
Add: equity equivalent of 18,05,386 OCRPS issued under the scheme | 90,26,930 | Disclosed by the valuer; implies 5 shares per OCRPS |
Fully diluted before the Rs 510 issue (31 Aug 2026) | 16,65,65,970 | Disclosed by the valuer |
of which equity shares outstanding | 14,92,05,710 | Disclosed (Annexure C) |
of which warrants held by the promoter | 83,33,330 | Disclosed 8,33,333, x 10 |
Add: Rs 510 issue, if fully subscribed | 58,82,352 | Disclosed (proposed) |
Fully diluted after the Rs 510 issue | 17,24,48,322 | Priveq arithmetic |
Source: valuation report dated 7 January 2026, p. 10 and Annexure I; FY26 standalone Note 17(b), PDF p. 55; valuation report dated 16 October 2026, Annexure I (p. 14); EGM resolution of 12 November 2026, Annexure C; scheme clause 15.1 and Schedule (OCRPS of Rs 100, conversion terms to be agreed). Paid-up capital of Rs 32.97 crore reconciles as 14,92,05,710 x Rs 1 plus 18,05,386 x Rs 100.
The OCRPS came out of a composite scheme approved by the NCLT, Mumbai Bench, on 24 March 2026 (NCLT order). It merged InCred Wealth Private Limited and InCred Research Services Private Limited into InCred Capital, with an appointed date of 1 April 2025, and moved the merchant banking business of InCred Capital Wealth Portfolio Managers Private Limited into InCred Capital. InCred Wealth's shareholders received Rs 100 OCRPS carrying a nominal 0.000001% dividend, a 10-year tenure and no voting rights; the scheme leaves the conversion terms to be agreed in writing (scheme, clause 15.1 and Schedule). The scheme became effective once InCred Capital received its SEBI merchant banking registration on 21 August 2026, which the company reported to the Registrar on 28 August 2026 (intimation to the Registrar, pp. 1-3).
Net read: use 14,92,05,710 shares for the equity outstanding today, 16,65,65,970 for any valuation on a fully diluted basis, which is what the valuer used, and 17,24,48,322 once the Rs 510 issue is fully allotted. At Rs 510, the OCRPS holders' 90,26,930 share equivalent is worth about Rs 460 crore, which makes the conversion ratio a material term even though it is not in the public scheme.
What Rs 510 Implies on FY26 Numbers?
FY26, the year to 31 March 2026, is the last audited year. On a consolidated basis, revenue from operations rose to Rs 1,452.83 crore from Rs 686.79 crore, while Group profit after tax fell to Rs 40.95 crore from Rs 112.18 crore. Profit before tax and exceptional items was Rs 140.64 crore, against Rs 150.92 crore in FY25, and a Rs 59.68 crore exceptional charge, booked in the investment banking segment, took it down to Rs 80.96 crore (FY26 annual report, consolidated statement of profit and loss, PDF p. 123; segment note, PDF p. 196). The wealth management segment made a pre-tax loss of Rs 152.36 crore in the same year.
What each price implies on FY26 audited consolidated figures (16,65,65,970 fully diluted shares)
Metric (FY26 base) | At Rs 423 (Jan 2026 round) | At Rs 485 (desk, 17 Nov 2026) | At Rs 510 (Nov 2026 round) |
|---|---|---|---|
Equity value (Rs crore) | 7,045.74 | 8,078.45 | 8,494.86 |
P/E on Group PAT of Rs 40.95 crore | 172.1x | 197.3x | 207.4x |
Price to pre-exceptional profit before tax (Rs 140.64 crore) | 50.1x | 57.4x | 60.4x |
P/B on total equity of Rs 1,121.18 crore | 6.28x | 7.21x | 7.58x |
Price to revenue from operations (Rs 1,452.83 crore) | 4.85x | 5.56x | 5.85x |
Source: FY26 audited consolidated balance sheet (PDF p. 122) and statement of profit and loss (PDF p. 123), Rs lakh converted to crore; Group (total) figures used. FY26 revenue includes a commodity-trading line with Rs 527.00 crore of purchases. All multiples are Priveq arithmetic on the fully diluted count used by the valuer.
For an investment bank and wealth manager, price to book and price to pre-exceptional profit are more useful than headline P/E in a year with a one-off charge. Even on those, Rs 510 asks about 7.6 times book and 60 times pre-exceptional pre-tax profit. Assets under management, the metric usually used for wealth and asset managers, is not disclosed in either valuation report or the FY26 financial statements as read.
Net read: on audited FY26 numbers, the Rs 510 price is expensive by any lens. The case for it rests entirely on the projected recovery, the merchant banking licence and the merged wealth business, none of which is in the FY26 profit line yet.
InCred Capital Is Not InCred Holdings
Two InCred companies are in the news at once, and they are easy to confuse. InCred Holdings Limited is the IPO-bound parent of the NBFC InCred Financial Services Limited, and the lending profits reported in IPO coverage belong to that group. InCred Capital Financial Services Limited is the group's institutional, investment banking, wealth and asset management company, with its own shareholders, accounts and share price. Its Rs 510 round tells you nothing directly about InCred Holdings' IPO price, and the reverse. For the parent of the lending company, see InCred Holdings on the Priveq Marketplace.
What Do The Filings Leave Out?
The projections. Both valuation reports rely on management's projected cash flows to FY32 and do not attach them.
What the exceptional item was. The FY26 accounts show Rs 59.68 crore in the investment banking segment and do not describe its nature in the pages we read.
The OCRPS conversion ratio. The scheme leaves it to agreement; the valuer's count implies five shares per OCRPS on the Rs 1 basis.
The split of the Rs 300 crore between business needs, general purposes and subsidiaries.
Assets under management, the usual yardstick for this kind of business.
A lock-in on the new shares; none is stated.
Net read: these are disclosure gaps, not red flags. The allotment return (Form PAS-3), due within 15 days of each allotment, should confirm how much of the Rs 300 crore was actually raised.
The Desk View
Priveq's desk price for InCred Capital is Rs 485 per share as of 17 November 2026, on the Rs 1 face value after the split. Three facts frame it:
A Rs 300 crore book is being built above the desk. Rs 510 is 5.2% above the desk's Rs 485 (17 November 2026), and the company's own investors, including the founder's vehicle, are subscribing at it.
The desk sits between the two rounds. Rs 485 (17 November 2026) is 14.7% above January's split-adjusted Rs 423 and 4.9% below Rs 510.
The audited numbers lag the price. FY26 Group profit was Rs 40.95 crore; every price in this note is a bet on what comes after it.
The one variable that would most change this view: the FY27 half-year or full-year profit, because it is the first audited test of the projections behind a 33% rise in value. The one event to watch: the allotment return, which shows how much of the round actually closed at Rs 510.
FAQs
What is the InCred Capital unlisted share price today?
Priveq's desk quotes InCred Capital at Rs 485 per share as of 17 November 2026, on the Rs 1 face value after the 1:10 split. The company's latest issue price is Rs 510. Talk to the desk for a live quote.
At what price is InCred Capital raising money?
InCred Capital is issuing up to 58,82,352 equity shares at Rs 510 each, up to Rs 300 crore, approved by shareholders on 12 November 2026. The price comes from a registered valuer's DCF report dated 16 October 2026.
Is InCred Capital the same company as InCred Holdings?
No. InCred Holdings is the IPO-bound parent of the lending company InCred Financial Services. InCred Capital is the group's investment banking, wealth and asset management company, with separate shares and accounts.
What happened to InCred Capital's share price after the split?
Shareholders approved splitting each Rs 10 share into ten Rs 1 shares on 30 September 2026. Every pre-split price divides by ten, so January's Rs 4,230 round equals Rs 423 a share today.
How many shares does InCred Capital have?
InCred Capital has 14,92,05,710 equity shares of Rs 1. Counting warrants and OCRPS, the fully diluted total is 16,65,65,970, rising to 17,24,48,322 if the Rs 510 issue is fully allotted.
Why did InCred Capital's profit fall in FY26?
Consolidated profit after tax fell to Rs 40.95 crore from Rs 112.18 crore, after a Rs 59.68 crore exceptional charge. Wealth management also lost Rs 152.36 crore before tax, while revenue more than doubled.
What We Can And Cannot Stand Behind
Read directly from primary documents:
Every term of the Rs 510 issue, the subscriber list, the shareholding tables and the October 2026 valuation report, from the certified resolution filed on 12 November 2026.
The January 2026 round, its valuation report and its shareholding tables, from the January 2026 EGM notice; its allotment, from FY26 Note 17.
FY26 consolidated revenue, profit, exceptional item, segment results, equity and borrowings, from the FY26 audited financial statements (auditor M S K A & Associates LLP, signed 7 September 2026).
The split, from the AGM resolution of 30 September 2026; the merger, the OCRPS terms and the effective date, from the NCLT order, the certified scheme and the company's letter to the Registrar of 28 August 2026.
Priveq arithmetic, labelled as such: split adjustments, the share-count reconciliation's derived lines and the five-shares-per-OCRPS ratio, the terminal-value share, the no-discount price, the value of the OCRPS at Rs 510, every multiple in the multiples table and every percentage gap between prices.
Could not be confirmed:
Management's projections behind either valuation.
The nature of the Rs 59.68 crore exceptional item.
The agreed OCRPS conversion terms.
How much of the Rs 300 crore will be subscribed and allotted.
Assets under management at any date.
Registry documents were read as filed up to 16 November 2026.
Primary Sources
Documents read, with locators. Where a link is shown, the document is a copy hosted by Priveq, because the MCA portal does not give the public a direct link to filings.
Certified special resolution, explanatory statement and valuation report, EGM of 12 November 2026: resolution (pp. 1-2), explanatory statement items 1 to 21 (pp. 3-5), Annexure A (p. 6), valuation report by Aditi Mittal & Co dated 16 October 2026 (pp. 7-21, including Annexure II), Annexure C shareholding (p. 22).
EGM notice of 7 January 2026 with valuation report: Item 1, explanatory statement, Annexure A, valuation report (DCF, p. 10 and Annexure I) and Annexure C shareholding.
Annual Report FY2025-26: standalone Note 17, equity share capital (PDF p. 55); consolidated balance sheet (PDF p. 122); consolidated statement of profit and loss (PDF p. 123); segment information (PDF p. 196).
AGM special resolution of 30 September 2026, sub-division of equity shares (filed with Form SH-7, 14 October 2026).
NCLT, Mumbai Bench, order of 24 March 2026 in C.P. (CAA) 222/MB/2025.
Composite scheme of arrangement, certified copy: clause 15 (consideration) and Schedule (OCRPS terms).
Letter to the Registrar of Companies on the scheme's effective date, 28 August 2026: pp. 1-3 (SEBI merchant banking registration of 21 August 2026).
Talk to the desk: WhatsApp +91 82874 66698 | support@priveq.in | View InCred Capital on the Priveq Marketplace
Disclaimer: This Event Note is written by Himanshu Singh and published by Priveq India for information only and is not investment advice, a research report or a recommendation to buy, sell or hold any security. Priveq India is not registered with SEBI as a stock exchange, investment adviser or research analyst. The analysis is independent desk research based on InCred Capital Financial Services Limited's filings and audited financial statements listed under Primary Sources; figures marked as Priveq arithmetic are our own calculations and are not company disclosures or guidance. Unlisted shares carry risks including illiquidity, valuation uncertainty and limited regulatory disclosure, and the desk price shown is indicative as of the date stated. Priveq India (Priveq Investech Private Limited, Priveq.in) is the named counterparty on transactions executed through the platform. Investors should do their own due diligence and consult a qualified adviser.