

The Short Version
INOX Air Products Limited, India's largest industrial gases company by FY26 revenue according to a CRISIL report it commissioned, filed a DRHP dated 30 September 2026 for a pure offer for sale of up to 77,156,663 shares, and as of 18 November 2026 SEBI has issued no observations. At the desk price of Rs 1,600 (18 November 2026) the company is worth about Rs 82,726 crore, roughly 58 times FY26 operating EBITDA of Rs 1,421 crore, because the DRHP's EBITDA of Rs 1,648 crore includes other income and a one-time joint venture gain.
Our stated position, a Priveq scenario and not a price call: the filings support roughly Rs 1,250 to Rs 1,670 a share at 45x to 60x operating EBITDA, the band between Ellenbarrie and Linde India, which puts Rs 1,600 (18 November 2026) near the top. The variable that would change it is whether the Rs 1,415 crore of plants under construction lifts operating EBITDA by about 15%, the increase the desk price needs at 50x.
INOX Air Products: company data
Company: INOX Air Products Limited (legal name; formerly INOX Air Products Private Limited, and Industrial Oxygen Company until 1999). Not INOX Clean Energy, INOX Green Energy or Inox Wind, which belong to the INOXGFL group, and not INOX India Limited, a listed related party
Sector: Industrial, medical, electronic and specialty gases: on-site plants, merchant liquid gases and cylinders
Filing status: DRHP dated 30 September 2026, on the SEBI listing from 5 October 2026; no addendum, SEBI observations or RHP as of 18 November 2026
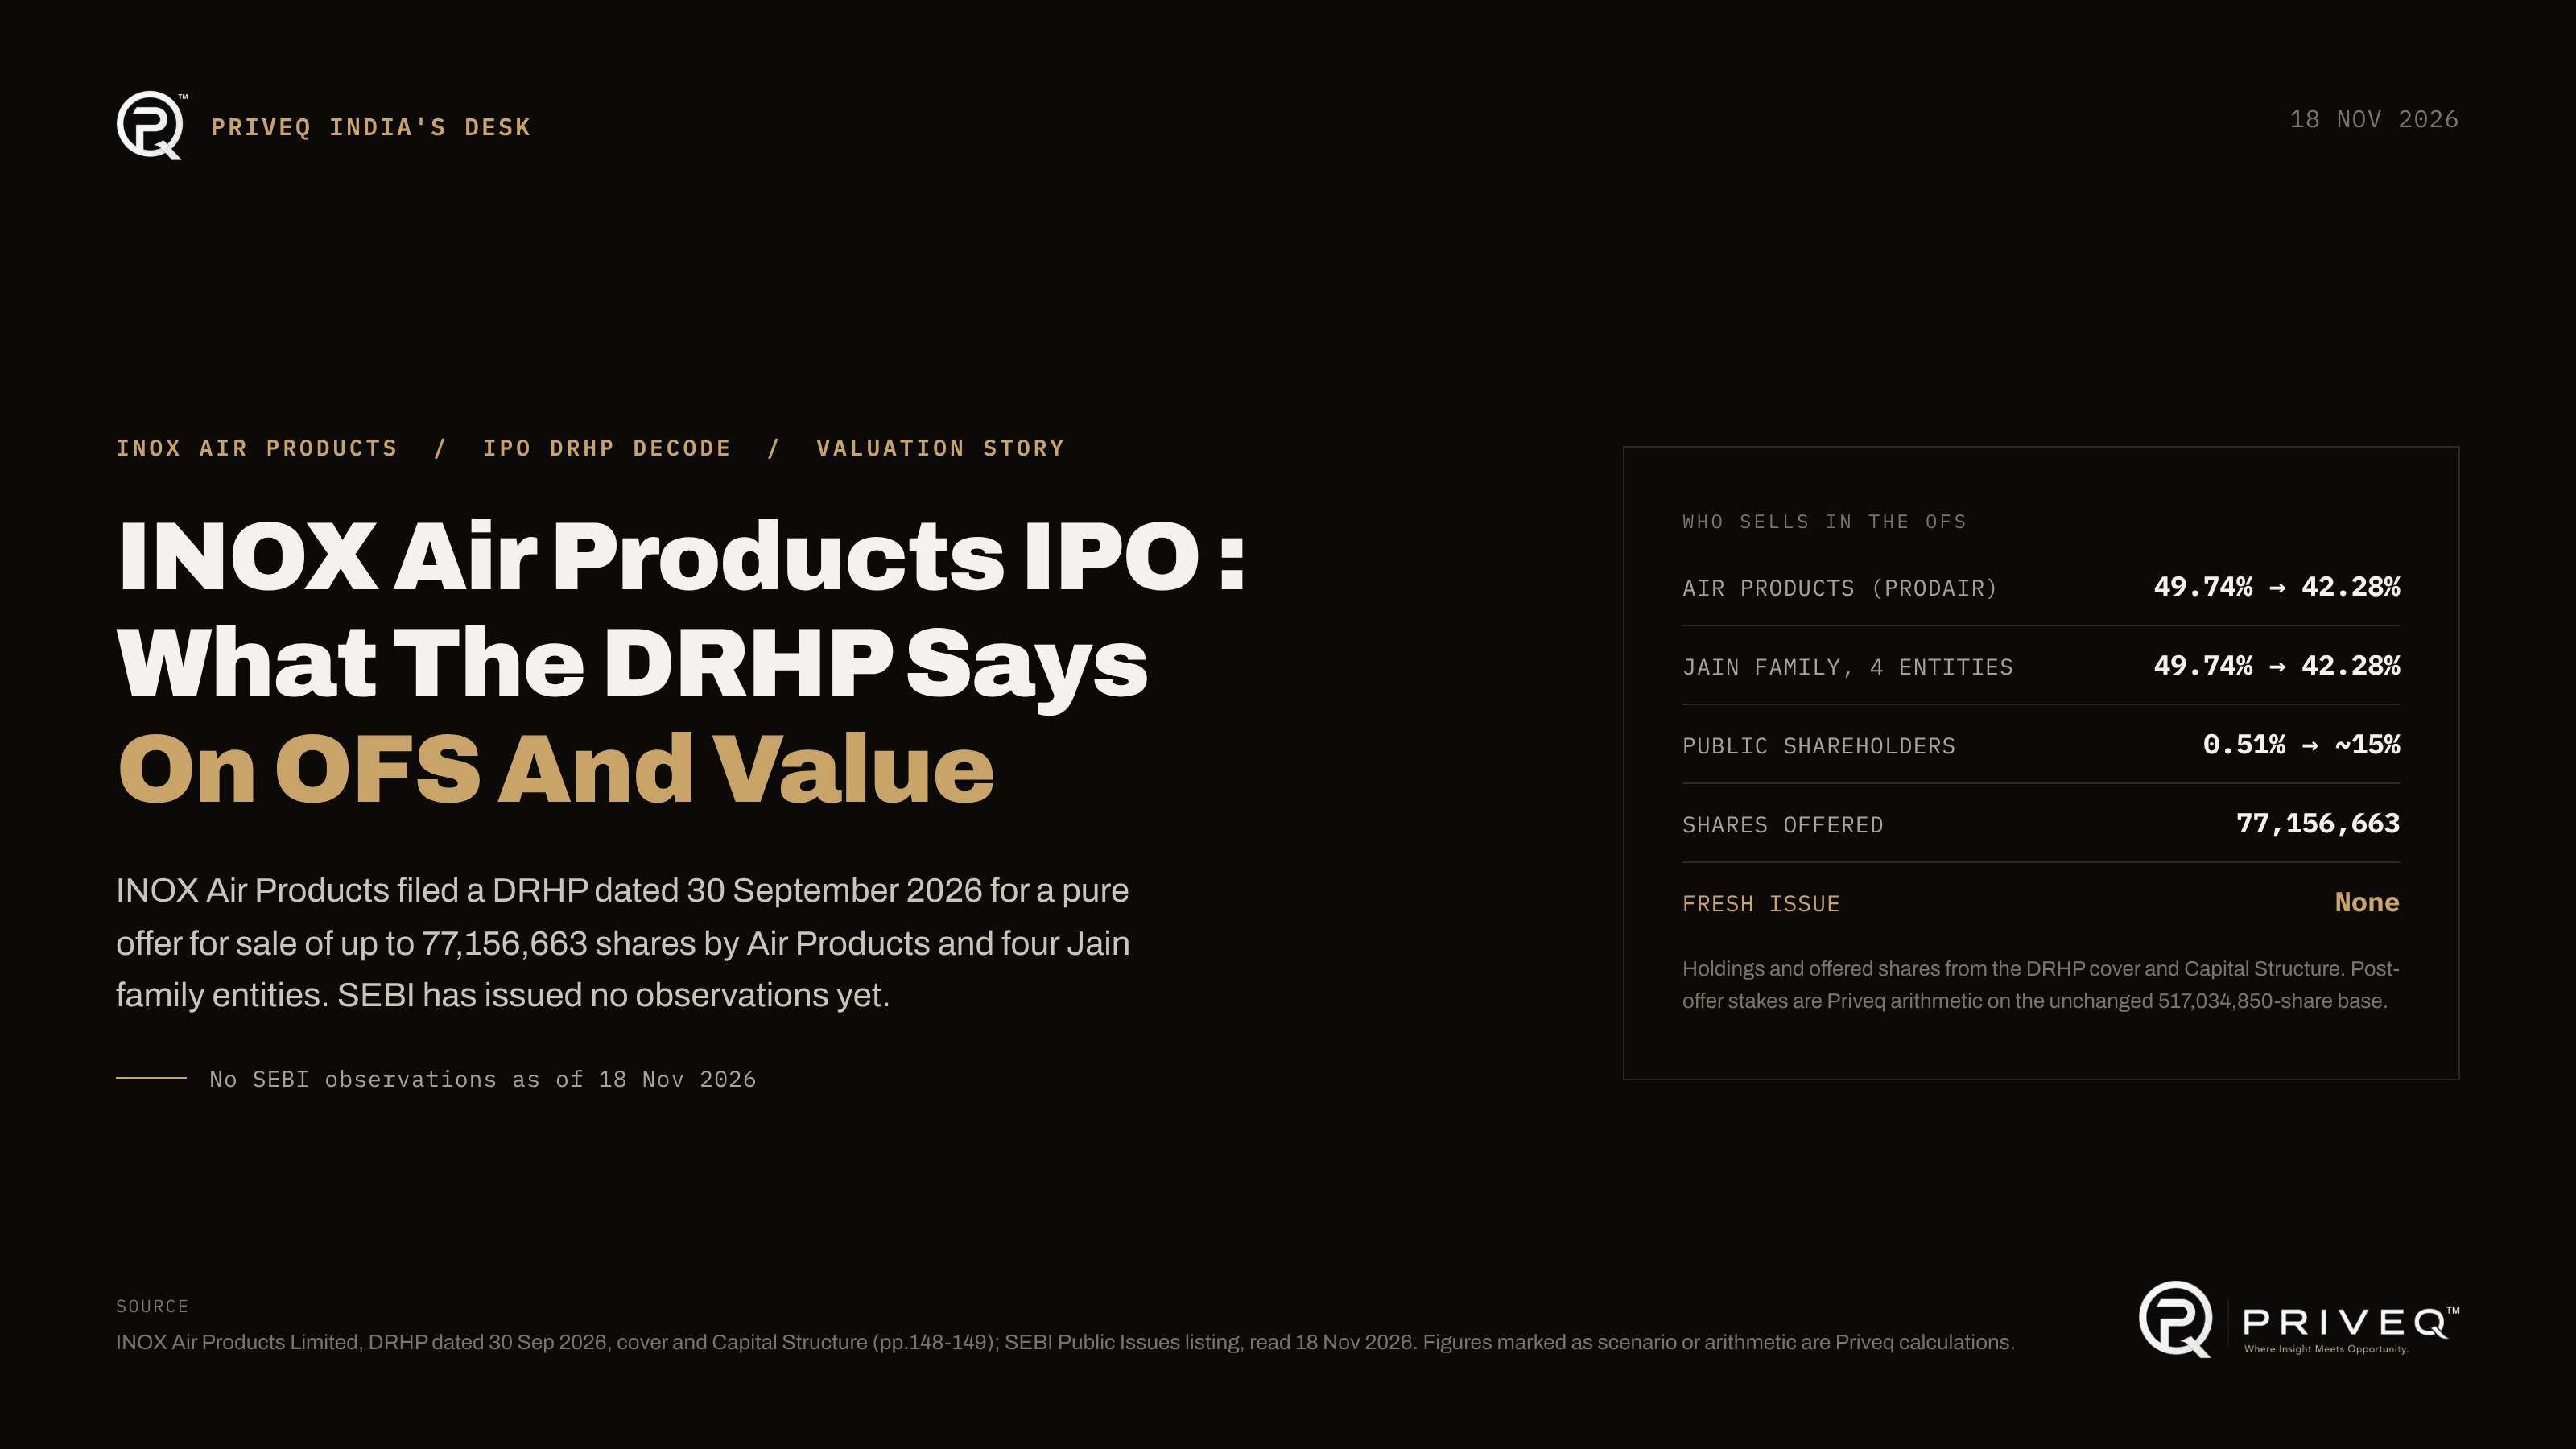
Issue: 100% offer for sale of up to 77,156,663 Re 1 shares (14.92% of the company) by Air Products' Prodair Corporation and four Jain family entities; no fresh issue, so the company receives nothing
Latest financials: Restated consolidated FY26 (year to 31 March 2026): revenue from operations Rs 3,033.93 crore, operating EBITDA Rs 1,421.36 crore (derived), EBITDA as the DRHP defines it Rs 1,647.79 crore, profit after tax Rs 913.87 crore, EPS Rs 17.68, net cash Rs 849.75 crore (DRHP definition)
Desk price: Rs 1,600 per Re 1 share, as of 18 November 2026, indicative;
Share basis: Re 1 face value after the 1-into-10 split (June 2026) and the 4-for-1 bonus (4 September 2026); 517,034,850 shares; no options granted
Valuation lens (Priveq-derived): EV/EBITDA on operating EBITDA, cross-checked with P/E and P/B against Linde India and Ellenbarrie
Identifiers: CIN U24999MH1963PLC012625 (DRHP cover); ISIN INE321A01020 (NSDL record: "EQ NEW FV RE. 1/-", equity shares, active, face value Re 1; registrar MUFG Intime India; checked 18 November 2026)
Primary sources: DRHP dated 30 September 2026 and the SEBI Public Issues listing; full list below
Last verified: 18 November 2026
For the live desk snapshot, see INOX Air Products on Priveq Marketplace.
Where does the INOX Air Products IPO stand today?
INOX Air Products filed a DRHP dated 30 September 2026, listed by SEBI on 5 October 2026, and as of 18 November 2026 there is no SEBI observation, addendum or RHP on the SEBI listing, so the next step is SEBI's clearance. The draft leaves price, issue value and dates blank.
IPO status tracker for INOX Air Products Limited, as of 18 November 2026
Each row is tagged disclosed (in a filing), reported (press, not confirmed by a filing) or expected.
Stage | Date | Status | Source |
|---|---|---|---|
Conversion to a public company; name back to INOX Air Products Limited | 1 Jul 2026 | Disclosed | DRHP cover page |
Share split, Rs 10 to Re 1 face value (board and EGM) | 3 Jun 2026; 9 Jun 2026 | Disclosed | DRHP Capital Structure (p.120) |
Bonus issue, 4 shares for every 1 held | 4 Sep 2026 | Disclosed | DRHP Capital Structure (p.120) |
SEBI exemption application on promoter-group disclosure | 7 May 2026; not granted at DRHP date | Disclosed | DRHP risk factor 42 (p.60) |
Waiver cum amendment agreement to the 1999 joint venture contract | 30 Sep 2026 | Disclosed | DRHP History (p.353) |
DRHP dated; filed on SEBI listing | 30 Sep 2026; 5 Oct 2026 | Disclosed | DRHP cover; SEBI Public Issues listing |
Reported issue size Rs 10,000 to 11,000 crore | 1 Oct 2026 | Reported | PTI via CNBC-TV18, unnamed sources |
SEBI observations | None found | Expected | SEBI listing read 18 Nov 2026; no addendum or RHP |
RHP, price band, anchor book, listing | Not announced | Expected | DRHP leaves price and dates blank |
Long-stop: joint venture contract revives if not listed | 30 Jun 2027 | Disclosed | DRHP History (p.353) |
The SEBI listing for the company was searched on 18 November 2026 and shows only the DRHP and the draft abridged prospectus
Three dates carry most of the weight. SEBI usually takes one to three months after filing, so observations could come at any time. A separate SEBI decision is pending on the company's 7 May 2026 request not to treat Vivek Kumar Jain's businesses as part of the promoter group, which the DRHP says may not be granted (risk factor 42, p.60). And the reshaped joint venture terms lapse if the shares do not list by 30 June 2027 (p.353).
Net read: this is an early-stage draft. Nothing about price is fixed, and the live questions are whether SEBI clears the draft and whether it grants the promoter-group exemption.
What does the INOX Air Products IPO offer, and who is selling?
INOX Air Products' IPO is entirely an offer for sale of up to 77,156,663 Re 1 shares, 14.92% of the company, split almost exactly in half between Air Products' Prodair Corporation (38,578,328) and four Jain family entities (38,578,335), according to the DRHP cover. The company raises no money; all proceeds go to the sellers.
Who sells in the INOX Air Products OFS, and what they paid
Re 1 face value shares. Holdings and offered shares from the DRHP cover and Capital Structure (p.148 to 149). Weighted average cost of acquisition (WACA) as certified by N B T and Co, 30 September 2026.
Shareholder | Shares held | Pre-offer | Shares offered | Post-offer (derived) | WACA, Rs per share |
|---|---|---|---|---|---|
Prodair Corporation | 257,188,850 | 49.74% | 38,578,328 | 42.28% | 7.49 |
INOX Chemicals LLP | 78,435,200 | 15.17% | 11,765,280 | 12.89% | 0.64 |
Siddho Mal Trading LLP | 77,663,000 | 15.02% | 11,649,450 | 12.77% | 0.26 |
Siddhomal Air Products Pvt Ltd | 97,820,000 | 18.92% | 14,673,000 | 16.08% | 0.06 |
Sitashri Trading and Finance Pvt Ltd | 3,270,700 | 0.63% | 490,605 | 0.54% | 3.22 |
Promoters and promoter group | 514,377,750 | 99.49% | 77,156,663 | 84.56% | n/a |
Public shareholders (all others) | 2,657,100 | 0.51% | 0 | n/a | n/a |
Post-offer percentages are Priveq arithmetic on the unchanged 517,034,850-share base (no fresh issue). Public shareholders' post-offer share depends on allotment and is not shown.
Three things stand out in the seller table:
Promoters own almost everything. Promoters and the promoter group hold 99.49% before the offer; public shareholders hold 2,657,100 shares, or 0.51% (p.148 to 149). That 0.51% is the stock that changes hands in the unlisted market today, worth about Rs 425.14 crore at Rs 1,600 (18 November 2026).
Cost bases are tiny on today's share. The certified weighted average cost of acquisition runs from Rs 0.06 a share for Siddhomal Air Products to Rs 7.49 for Prodair, set mostly by share purchases at Rs 375 per old Rs 10 share in 1999 (Rs 7.50 today).
The balance of power does not move. Both sides sell the same number of shares, so Air Products and the Jain family group each hold 42.28% after the offer (derived), which keeps the board-sharing terms in place.
At Rs 1,600 (18 November 2026), the offered shares are worth about Rs 12,345.07 crore (derived), close to the Rs 10,000 to 11,000 crore size reported by PTI on 1 October 2026.
Net read: this IPO is a part-exit for two founding groups at a 50:50 split, not a capital raise, and it lifts public ownership from 0.51% to about 15%.
How did the 2026 split and bonus change INOX Air Products per-share numbers?
INOX Air Products split each Rs 10 share into ten Re 1 shares in June 2026 and issued 4 bonus shares for every 1 held on 4 September 2026 (DRHP Capital Structure, p.120). Any price quoted per old Rs 10 share must therefore be divided by 50 to compare with today's Re 1 share.
INOX Air Products corporate actions that change per-share numbers
DRHP Capital Structure, equity share capital history (p.102 to 120). Divide-by factors are Priveq arithmetic.
Date | Action | Ratio | Shares after | Divide a pre-action price by |
|---|---|---|---|---|
3 Jun 2026 (board); 9 Jun 2026 (EGM) | Split of Rs 10 shares into Re 1 shares | 1 into 10 | 103,406,970 | 10 |
4 Sep 2026 | Bonus issue | 4 for every 1 held | 517,034,850 | 5 |
Combined | Any price per Rs 10 share before June 2026 | 50 |
Worked example: the 1999 share sale price of Rs 375 per Rs 10 share is Rs 7.50 on today's Re 1 share. The DRHP's EPS, NAV and RoNW figures are already adjusted (Basis for Offer Price, p.161 to 162).
The company's own price history is long, because INOX Air Products has been public before. It listed through a public issue at Rs 140 a share in July 1994 and voluntarily delisted from BSE, NSE and four regional exchanges between 1999 and 2000, after Air Products bought in (DRHP cover and p.91).
INOX Air Products share-price history, restated to today's Re 1 share
Prices per Rs 10 share from the DRHP Capital Structure (p.102 to 143) and History (p.353); Re 1 column divides by 50 (Priveq arithmetic).
Date | Event | Rs per Rs 10 share | Rs per Re 1 share today |
|---|---|---|---|
21 Jul 1994 | Public issue (IPO) at Rs 140 per Rs 10 share | 140.00 | 2.80 |
1 Feb 1997 | Re-issue of forfeited shares at Rs 90 | 90.00 | 1.80 |
25 Jan 1999 (SSA) | Air Products buys 2,942,196 shares at Rs 375 under the share sale agreement | 375.00 | 7.50 |
1999 to 2000 | Delisting public offer price paid to tendering shareholders | 375.00 | 7.50 |
2002 to 2004 | Later escrow transfers to Prodair at Rs 250 | 250.00 | 5.00 |
5 Jan 2004 | Buy-back at Rs 215 | 215.00 | 4.30 |
9 Jun 2005 | Capital reduction: Rs 300 preference share per Rs 10 share cancelled | 300.00 | 6.00 |
Desk price Rs 1,600 per Re 1 share as of 18 November 2026 equals Rs 80,000 on the old Rs 10 basis. The bonus issues of 1988 to 1994 sit before most of these rows and are not adjusted separately because the prices shown were paid on the then-current share.
Two practical points follow:
Old annual-report numbers need converting. The DRHP's restated profit and loss statement shows FY26 EPS of Rs 883.76 on a Rs 10 share (p.84); on today's Re 1 share that is Rs 17.68, the figure the DRHP uses.
Old marketplace quotes need converting too. A price quoted per Rs 10 share before June 2026 compares with the desk price of Rs 1,600 (18 November 2026) only after dividing by 50.
Net read: the split and bonus changed the share count by 50 times and nothing else; market value, profit and book value are unchanged.
Which INOX Air Products share count should you use?
INOX Air Products has 517,034,850 Re 1 shares, and that is the right base for every per-share figure, because the OFS issues no new shares and the DRHP records no options granted under the ESOP Plan 2026 (Capital Structure p.148; risk factor 46, p.63).
INOX Air Products share base for per-share maths
DRHP Capital Structure (p.120, p.148 to 149); risk factor 46 (p.63).
Measure | Shares | Use |
|---|---|---|
Equity shares today (Re 1) | 517,034,850 | Priveq headline base |
Options granted under ESOP Plan 2026 | 0 | No options granted at DRHP date |
Cautious base (headline plus options in force) | 517,034,850 | Same as headline |
Shares offered in the OFS | 77,156,663 | 14.92% of the base (derived) |
Shares held by public shareholders today | 2,657,100 | 0.51% of the base |
Shareholders of record, 29 Sep 2026 | 58 | 5 promoter entities and 53 public holders (p.154) |
Old Rs 10 shares in demat form, 31 Mar 2026 | 44,664 of 10,340,697 | 0.43% (derived); FY26 annual return, Form MGT-7 |
Shares in demat form, 29 Sep 2026 | 99.93% | All promoter shares; public demat 0.45% of the company (p.154) |
No fresh issue, no convertibles and no options: the share count before and after the IPO is the same. Demat percentages for 29 September 2026 are the DRHP's own, rounded to two decimals; the public holding in paper form is about 0.07% of the company (derived from those rounded figures).
Unlike most pre-IPO companies Priveq covers, there is no gap between today's count and a fully diluted count: no preference shares, no convertible debentures and no options in force. Future grants under the ESOP Plan would dilute holders, and the DRHP says such grants may be made at a discount to market price.
INOX Air Products' shares were almost all on paper until this year. The FY26 annual return (Form MGT-7) shows only 44,664 of 10,340,697 old Rs 10 shares in demat form at 31 March 2026, about 0.43%. By 29 September 2026 the DRHP's shareholding table shows 99.93% in demat, including every promoter share, after tripartite agreements with NSDL (15 September 2016) and CDSL (30 April 2026) (p.154 and p.575). What is left on paper sits with public holders: about 0.07% of the company (derived).
For a buyer of the public float that matters in practice. Shares still held in paper form must be dematerialised before they can move to a demat account, and on listing only demat shares can trade (p.596).
Net read: market value at any price is that price times 517,034,850, before and after listing. At Rs 1,600 (18 November 2026) that is Rs 82,725.58 crore.
How does INOX Air Products make money?
INOX Air Products earned Rs 3,033.93 crore of revenue from operations in FY26, of which 58.55% came from merchant liquid gases delivered by tanker, 28.69% from on-site plants at customer premises and 12.76% from packaged and specialty gases in cylinders (DRHP MD&A, p.521). It served more than 3,000 customers at 31 March 2026.
How the three models work, from the DRHP:
On-site. The company builds and runs an air separation plant inside a customer's site, typically on a 15 to 20-year contract with take-or-pay protection, meaning the customer pays for a minimum volume whether or not it takes it. The customer supplies the power at no cost to the company. About 76% of production capacity sits in on-site plants (risk factor 1, p.30 to 31).
Merchant. The company runs its own plants, buys its own power and sells liquid oxygen, nitrogen and argon by tanker under contracts and purchase orders, recovering power in its prices. It owned 739 transport tankers at 31 March 2026 (KPIs, p.165).
Packaged and specialty. Cylinders of industrial, medical, electronic and specialty gases, sold on purchase orders.
INOX Air Products revenue by business vertical, Rs crore
DRHP Management's Discussion and Analysis, relationships with key customers (p.521); converted from Rs million. Shares and growth are Priveq arithmetic.
Vertical | FY26 | FY25 | FY24 | Share FY26 | Growth FY26 |
|---|---|---|---|---|---|
Merchant (liquid gases by tanker) | 1,776.43 | 1,784.12 | 1,603.73 | 58.55% | -0.4% |
On-site (plants at customer sites) | 870.30 | 678.47 | 639.04 | 28.69% | +28.3% |
Packaged and specialty gases (cylinders) | 387.20 | 327.19 | 347.16 | 12.76% | +18.3% |
Revenue from operations | 3,033.93 | 2,789.78 | 2,589.93 | 100.00% | +8.8% |
1 crore = 10 million. On-site plants run on power the customer supplies at no cost to the company, so their revenue is low relative to capacity (risk factor 1, p.30).
The company's own annual return gives a second cut of the same revenue. Form MGT-7 for FY26 classifies 71% of turnover as manufacture of chemicals and chemical products and 29% as rental and leasing activities (FY26 MGT-7, principal business activities). The 29% is close to the 28.69% that on-site plants contributed in the DRHP, which fits on-site plants being run under plant-lease contracts; that link is Priveq's reading, and neither filing states it.
Customers and concentration, from the filing:
Steel is the largest end market: 40.59% of FY26 revenue (p.521).
The top 10 customers took 31.60% of FY26 revenue, up from 27.41% in FY25, and the largest single customer 12.23% (p.30 and p.521 to 522).
One on-site contract was lost in 2021, when the customer acquired the plant on expiry (risk factor 1, p.31).
Net read: FY26 growth came from on-site plants and cylinders, while merchant revenue, still the largest line, was flat. That mix matters for valuation because on-site revenue is contracted and power-free, while merchant revenue carries the power bill and spot pricing.
How much of INOX Air Products' profit is operating profit?
INOX Air Products' FY26 profit after tax of Rs 913.87 crore rose 3.74%, while operating EBITDA, revenue less operating costs, rose 12.92% to Rs 1,421.36 crore (Priveq arithmetic on DRHP p.84). The gap is other income and a one-time joint venture gain that fell or will not repeat.
INOX Air Products restated consolidated financials, Rs crore
DRHP Summary of Financial Information (p.82 to 86) and Basis for Offer Price KPIs (p.164); converted from Rs million. Operating EBITDA and margins are Priveq arithmetic.
Rs crore | FY26 | FY25 | FY24 |
|---|---|---|---|
Revenue from operations | 3,033.93 | 2,789.78 | 2,589.93 |
Operating EBITDA (revenue less operating costs) | 1,421.36 | 1,258.75 | 1,146.31 |
Operating EBITDA margin | 46.85% | 45.12% | 44.26% |
Other income | 178.94 | 258.86 | 183.81 |
Share in profit of joint venture | 47.49 | 2.04 | 1.00 |
EBITDA as the DRHP defines it | 1,647.79 | 1,519.65 | 1,331.12 |
Depreciation and amortisation | 346.49 | 264.06 | 231.40 |
Finance costs | 97.05 | 100.09 | 80.95 |
Profit before tax | 1,204.25 | 1,155.50 | 1,018.77 |
Profit after tax | 913.87 | 880.95 | 765.69 |
Basic EPS, Rs per Re 1 share (adjusted) | 17.68 | 17.04 | 14.81 |
Net cash from operating activities | 1,264.24 | 861.49 | 893.72 |
Total equity | 7,268.51 | 6,368.18 | 5,500.09 |
Borrowings (current and non-current) | 1,365.65 | 1,667.30 | 1,448.47 |
Restated consolidated, as the DRHP presents it. The FY26 annual report on the company's site covers the same year, so no later audited year exists to rebase on. The DRHP's EBITDA is profit plus tax, depreciation and finance cost, which keeps other income and the joint venture share inside it (KPI note 3, p.164).
The DRHP's own EBITDA, Rs 1,647.79 crore, is built from profit up, so it keeps other income and the joint venture share inside it. For a valuation built on operating earnings, the narrower figure is the one to use.
What sits between INOX Air Products' operating EBITDA and the DRHP's EBITDA, FY26
Rs crore. DRHP p.84 to 85 and MD&A (p.527 to 529). Bridge is Priveq arithmetic and ties to the DRHP KPI to the rupee.
Rs crore | FY26 | What it is |
|---|---|---|
Operating EBITDA (derived) | 1,421.36 | Revenue Rs 3,033.93 cr less materials, purchases, inventory change, power, employees and other expenses |
Add: other income | 178.94 | Includes Rs 78.47 cr non-cash gain on investments at fair value and Rs 61.81 cr interest income |
Add: share in profit of joint venture | 47.49 | Bellary Oxygen Company, a JV with Linde India; one-time gain on sale of investments (MD&A p.529) |
EBITDA as the DRHP defines it | 1,647.79 | KPI table, p.164 |
Gap between the two | 226.43 | 15.9% of the DRHP figure (derived) |
Interest income of Rs 61.81 crore is the DRHP's FY26 cash flow adjustment line (p.85). Other income also fell from Rs 258.86 crore in FY25, which held a Rs 45.63 crore land-sale profit and a Rs 20.22 crore prior-year power tariff incentive (MD&A p.527).
What the bridge shows:
Operating profit is growing faster than profit after tax. Operating EBITDA rose 12.92% in FY26 and 9.81% in FY25; margin rose to 46.85% from 44.26% in FY24.
FY25 profit was flattered by one-offs that did not recur. A Rs 45.63 crore land-sale profit and a Rs 20.22 crore prior-year power tariff incentive sat in FY25 other income (MD&A p.527).
FY26 profit was flattered by a one-off that will not recur. Rs 47.49 crore came from the Bellary Oxygen joint venture, against Rs 2.04 crore a year earlier, because of a one-time gain on investments that the joint venture sold (MD&A p.529).
Depreciation is rising fast. It grew 31.22% in FY26 as new on-site plants were commissioned (MD&A p.528), which is why operating profit growth did not reach profit after tax.
Reconciling profit before tax to the cash flow start line, the non-cash items in FY26 profit are the Rs 78.47 crore fair-value gain on investments, the Rs 47.49 crore joint venture share, Rs 15.90 crore of government grants released and Rs 5.62 crore of gains on asset sales (cash flow statement, p.85).
Net read: the business earns more each year from operations, but reported profit growth understates that in FY26 and overstated it in FY25. Valuing on EBITDA as the DRHP defines it would understate the multiple the market is paying by about 8 turns (derived).
Where does INOX Air Products' cash go?
INOX Air Products generated Rs 1,264.24 crore of operating cash in FY26 and spent Rs 1,161.94 crore on capex (cash flow statement, p.85 to 86). After interest and leases about negative Rs 5.64 crore was left, and across FY24 to FY26 the total was negative Rs 761.26 crore (Priveq arithmetic).
Where INOX Air Products' operating cash went, Rs crore
DRHP Summary of Cash Flow Statement (p.85 to 86). Cash after obligations is Priveq arithmetic: operating cash less capex (property, plant, right-of-use and intangibles), interest paid and lease payments.
Rs crore | FY26 | FY25 | FY24 |
|---|---|---|---|
Net cash from operating activities | 1,264.24 | 861.49 | 893.72 |
Less: capex | 1,161.94 | 1,293.46 | 1,021.60 |
Less: finance costs paid | 106.86 | 104.92 | 89.11 |
Less: lease payments | 1.08 | 0.93 | 0.82 |
Cash after obligations (derived) | -5.64 | -537.82 | -217.81 |
Dividend paid | 20.68 | 10.34 | 10.34 |
Capital work-in-progress at year end | 1,414.74 | 804.21 | 773.31 |
Three years together: operating cash Rs 3,019.45 crore, capex Rs 3,477.00 crore, cash after obligations negative Rs 761.26 crore (derived). Capex is shown positive because the row is labelled Less.
This is a company converting profit into plants:
Capex roughly equals operating cash. Rs 3,477.00 crore of capex against Rs 3,019.45 crore of operating cash over three years (derived).
More is under construction, and most of it is contracted. Capital work-in-progress rose to Rs 1,414.74 crore at 31 March 2026 from Rs 804.21 crore. The capacity being built is 10 signed on-site contracts of 4,314 TPD plus four merchant liquid plants of 921 TPD due by March 2027 (p.316 to 318), so about 82% of the tonnes under construction sit under signed on-site contracts (derived). The DRHP does not split the rupee CWIP by project; Rs 424.47 crore of capital contracts remained to be executed (MD&A, p.532), and no project is reported as delayed or over budget (note 6, p.438).
Dividends are small. Rs 20.68 crore paid in FY26, 2.26% of profit after tax (derived).
Some of the capex is bought from promoter-linked companies. The DRHP's related-party note shows asset purchases of Rs 279.68 crore from Prodair Air Products India and Rs 122.47 crore from INOX India Limited in FY26, and Rs 385.41 crore from Air Products and Chemicals Inc. in FY25 (p.88). Related-party transactions in total were 18.36% of FY26 revenue, down from 32.69% in FY25 (risk factor 43, p.61). The DRHP states these were at arm's length.
The balance sheet still has room: borrowings of Rs 1,365.65 crore against total equity of Rs 7,268.51 crore, and the company reports net cash of Rs 849.75 crore at 31 March 2026 after counting mutual funds, deposits and debentures it holds (KPI note 7, p.165).
Net read: free cash has been absorbed by growth capex for three years. The equity case rests on that capex producing contracted on-site EBITDA, not on cash returned to shareholders.
How would the INOX Air Products IPO be valued, and what does the price need?
INOX Air Products at Rs 1,600 (18 November 2026) trades at 57.6x FY26 operating EBITDA and 90.5x FY26 EPS. The DRHP leaves the price band blank and names only two listed peers, Linde India and Ellenbarrie Industrial Gases (Basis for Offer Price, p.161 to 163).
Priveq's lead lens is EV/EBITDA on operating EBITDA, because the business is capital-heavy and the company holds net cash, and because the DRHP's EBITDA mixes in treasury income and a one-off. P/E is shown as a cross-check, since readers search for it.
INOX Air Products at a desk price of Rs 1,600: the valuation lenses side by side
All Priveq arithmetic as of 18 November 2026, on 517,034,850 Re 1 shares. Net cash Rs 849.75 crore is the DRHP's own net debt at 31 March 2026 (p.164), which includes leases.
Lens | Value at Rs 1,600 | Comment |
|---|---|---|
Market value | Rs 82,725.58 cr | Same before and after the IPO (no fresh issue) |
Enterprise value | Rs 81,864.17 cr | Market value less net cash of Rs 861.41 cr excluding leases |
EV / FY26 operating EBITDA | 57.6x | 57.6x with leases in EV; 57.64x on EBITDA after lease costs |
EV / FY26 EBITDA as the DRHP defines it | 49.68x | Includes other income and the JV gain |
EV / FY26 revenue | 26.98x | |
Price / FY26 basic EPS | 90.5x | EPS Rs 17.68 (p.161) |
Price / FY26 EPS excluding the JV gain | 94.24x | Scenario: EPS Rs 16.98, tax at the FY26 rate of 24.11% |
Price / FY26 EPS excluding JV gain and fair-value gains | 101.1x | Scenario: EPS Rs 15.83 |
Price / NAV per share | 11.4x | NAV Rs 140.41 at 31 March 2026 (p.162) |
Dividend paid FY26 / market value | 0.02% | Rs 20.68 cr paid in FY26 |
Lease liabilities are Rs 11.66 crore, so the three EV/EBITDA views barely differ; leases are not a factor in this company's valuation.
What each EV/EBITDA multiple supports for INOX Air Products equity
Priveq arithmetic, scenario. Equity = multiple x FY26 operating EBITDA (Rs 1,421.36 cr) plus net cash excluding leases (Rs 861.41 cr). Per share on 517,034,850 shares.
EV / operating EBITDA | Equity value, Rs cr | Rs per share | vs desk Rs 1,600 |
|---|---|---|---|
35x | 50,608.90 | 978.83 | -38.8% |
40x | 57,715.69 | 1,116.28 | -30.2% |
45x | 64,822.48 | 1,253.74 | -21.6% |
50x | 71,929.26 | 1,391.19 | -13.1% |
55x | 79,036.04 | 1,528.64 | -4.5% |
60x | 86,142.83 | 1,666.09 | +4.1% |
65x | 93,249.62 | 1,803.55 | +12.7% |
At Rs 1,600 (18 November 2026) the implied multiple is 57.6x. Each turn of multiple is worth about Rs 27.5 a share (derived).
What operating EBITDA the Rs 1,600 desk price needs at different multiples
Priveq arithmetic, scenario. EV of Rs 81,864.17 cr held fixed; compared with FY26 operating EBITDA of Rs 1,421.36 cr.
Multiple | Operating EBITDA needed, Rs cr | vs FY26 |
|---|---|---|
45x | 1,819.20 | +28.0% |
50x | 1,637.28 | +15.2% |
55x | 1,488.44 | +4.7% |
60x | 1,364.40 | -4.0% |
Read: the nearer the market's multiple is to Ellenbarrie's, the more EBITDA growth the desk price is already paying for.
The reported issue size gives a second, unconfirmed reference point:
What the reported Rs 10,000 to 11,000 crore issue size would imply
Priveq arithmetic, scenario. Reported size is from a PTI report carried by CNBC-TV18 on 1 October 2026, citing unnamed people; the DRHP gives no rupee size. Divided by the 77,156,663 shares offered.
Reported OFS size | Rs per share | Market value, Rs cr | vs desk Rs 1,600 | P/E on FY26 EPS | EV / operating EBITDA |
|---|---|---|---|---|---|
Rs 10,000 cr | 1,296.06 | 67,011.04 | -19.0% | 73.31x | 46.54x |
Rs 11,000 cr | 1,425.67 | 73,712.15 | -10.9% | 80.64x | 51.25x |
If the reported size and the share count both hold, the implied price sits below the desk price. Neither the size nor its basis is confirmed by a filing.
Net read: Rs 1,600 (18 November 2026) prices INOX Air Products close to Linde India's multiple. At a midpoint between the two listed peers it needs operating EBITDA about 15% above FY26, which the capex in progress could deliver but has not yet. The reported issue size, if it is right, points about 11% to 19% below the desk price.
How does INOX Air Products compare with Linde India and Ellenbarrie?
INOX Air Products at Rs 1,600 is valued at 57.6x FY26 operating EBITDA, between Ellenbarrie at 34.5x and Linde India at 64.39x, on Priveq-derived figures from Screener read on 18 November 2026. INOX Air Products is about 1.2 times Linde India's revenue and nine times Ellenbarrie's.
INOX Air Products against the two listed peers the DRHP names
Filing column from DRHP Basis for Offer Price (p.163), closing prices of 29 September 2026. Later columns: Priveq-derived from Screener, prices read 18 November 2026 at 4:01 pm, on FY26 EPS and FY26 operating profit.
Company | Basis | FY26 revenue, Rs cr | P/E in DRHP (29 Sep 2026) | P/E (18 Nov 2026) | EV / FY26 EBITDA | P/B |
|---|---|---|---|---|---|---|
Linde India | Consolidated | 2,530.64 | 96.31x | 106.73x | 64.39x | 13.73x |
Ellenbarrie Industrial Gases | Standalone | 341.58 | 48.99x | 36.87x | 34.5x | 4.01x |
INOX Air Products at Rs 1,600 | Consolidated | 3,033.93 | [ ] in DRHP | 90.5x | 57.6x | 11.4x |
Peer EV uses market value plus borrowings less cash equivalents as Screener reports them; bank deposits and investments are not deducted, so peer multiples may be slightly overstated. Peer EBITDA is operating profit before other income, the same convention as INOX Air Products' operating EBITDA. The DRHP's industry P/E average is 72.65x.
The two peers bracket the range for different reasons:
Linde India is the closest match in model and scale, part of the Linde group, and trades at a premium: 106.73x FY26 EPS on 18 November 2026, up from 96.31x in the DRHP's table.
Ellenbarrie is about one-ninth the size and trades at 36.87x FY26 EPS, down from 48.99x in the DRHP table.
The DRHP's own industry P/E averages 72.65x across the two (p.162), but with two peers an average says little; Priveq relies on the range, not the average.
Net read: the desk price assumes INOX Air Products will be priced like Linde India, not like Ellenbarrie. Its operating margin of 46.85% is higher than both peers' FY26 operating margins on Screener (Linde India about 36%, Ellenbarrie about 34%), which is the strongest argument for a Linde-like multiple.
How big is the industrial gases market, according to the CRISIL report?
The CRISIL report INOX Air Products paid for sizes India's non-captive industrial gases market at Rs 13,516 crore in FY26, growing 10% to 12% a year to Rs 24,000 to 26,000 crore by FY32 (DRHP p.205 to 206). The report is dated 2 April 2026 and was commissioned under an engagement letter of 12 November 2025.
The report is titled "Assessment of Industrial Gas Industry" and has a June 2026 addendum; the DRHP says it was commissioned and paid for by the company exclusively for the offer (p.18).
Industrial gases market in India, according to the CRISIL report the company paid for
Excerpts reproduced in DRHP Industry Overview (p.205 to 206), where the charts carry the label "Source: Nexdigm". Rs crore converted from Rs million. Share is Priveq arithmetic.
Measure | FY26 | FY32 projected | CAGR stated |
|---|---|---|---|
Total market including captive (value) | 16,090.80 | 26,800 to 31,000 | 9% to 12% |
Non-captive market (value) | 13,516.08 | 24,000 to 26,000 | 10% to 12% |
Non-captive market (volume, million tonnes) | 28.4 | 42 to 47 | 7% to 9% |
INOX Air Products revenue as a share of the non-captive market | 22.45% (derived) |
The DRHP's 22.4% market-share claim matches FY26 revenue divided by the non-captive market. Market figures are a single commissioned source, not independent data.
What to take from it:
The 22.4% share claim is arithmetic, not a survey. It equals the company's FY26 revenue over the non-captive market size (derived 22.45%).
The market sizing rests on Nexdigm, not CRISIL's own estimates. Priveq read the full 158-page report on the company's site: 20 charts, including every India market-size chart, are labelled "Source: Nexdigm", and neither the report nor the DRHP explains Nexdigm's role or method. CRISIL's own label, "Crisil Intelligence", sits on the macro and end-user chapters.
The "largest by revenue" ranking compares against partial data. The report's peer table puts INOX Air Products' FY26 revenue of Rs 3,033.93 crore above Linde India's Rs 2,530.64 crore, but Air Water India and Air Liquide India show "NA" for FY26 (their FY25 figures are from MCA filings, standalone). The FY25 ranking covers all four peers.
Company growth is below the market's projected growth. Revenue grew 8.75% in FY26 against a 10% to 12% projected market CAGR, while on-site revenue grew 28.27%.
Net read: treat the market figures and the "largest company" claim as the company's commissioned view. The growth that matters for valuation is on-site capacity, which the market projection does not size separately.
What drives INOX Air Products' growth, and what could cut it?
INOX Air Products' growth in FY26 came from on-site plants, where revenue rose 28.27%, while merchant revenue fell 0.43%, and the DRHP itself warns that new capacity from rivals can oversupply merchant markets (MD&A, p.521). Power, at 22.22% of revenue, is the largest cost the company bears in merchant and packaged gases.
INOX Air Products growth and de-growth drivers: scorecard from the filing
Direction is Priveq judgement on disclosed numbers. Sources are DRHP page references.
Driver | Disclosed evidence | Direction |
|---|---|---|
On-site contracts | On-site revenue up 28.27% in FY26; 15 to 20-year contracts with take-or-pay protection (risk factor 1, p.31) | Growth |
Capex already in progress | Capital work-in-progress Rs 1,414.74 cr at 31 March 2026, up from Rs 804.21 cr | Growth if commissioned on time |
Merchant pricing | Merchant revenue down 0.43% in FY26; DRHP warns of oversupply in merchant markets (MD&A p.521) | Flat to soft |
Steel demand | Steel customers 40.59% of FY26 revenue, up from 37.06% in FY24 (p.521) | Concentration |
Customer concentration | Top 10 customers 31.60% of FY26 revenue; largest single customer 12.23% (p.30 to 31, p.522) | Concentration |
Power cost | Power and fuel Rs 674.15 cr, 22.22% of FY26 revenue; on-site power is the customer's cost | Margin risk on merchant |
Electronics and solar | CRISIL excerpts give 22.4% and 23.1% shares in these segments (p.216); Dholera semiconductor investment announced 6 Oct 2025 (company site) | Growth, company view |
Related-party capex | Assets bought from Air Products and INOX entities: Rs 445.76 cr in FY26, Rs 855.46 cr in FY25 (p.88) | Governance check |
The CRISIL segment shares are the company's commissioned view.
Sensitivity: INOX Air Products Rs per share for a change in operating EBITDA and the multiple
Scenario, not guidance. Base FY26 operating EBITDA Rs 1,421.36 cr; net cash excluding leases Rs 861.41 cr; 517,034,850 shares.
Change in operating EBITDA | 45x | 55x | 65x |
|---|---|---|---|
-10.0% | 1,130.03 | 1,377.44 | 1,624.86 |
-5.0% | 1,191.88 | 1,453.04 | 1,714.20 |
0% | 1,253.74 | 1,528.64 | 1,803.55 |
+5.0% | 1,315.59 | 1,604.24 | 1,892.89 |
+10.0% | 1,377.44 | 1,679.84 | 1,982.23 |
Read across for the multiple, down for how far EBITDA lands from FY26. Net cash is held fixed.
One sizing that does not depend on the price: a 5% rise in power and fuel cost that the company could not pass on would cut FY26 profit after tax by about Rs 25.58 crore, or 2.8% (scenario at the FY26 tax rate). How exposed is the company? On-site plants, about 76% of production capacity, get their power from the customer at no cost to INOX Air Products (risk factor 1, p.30). Merchant contracts run three to seven years at a fixed price adjusted only through cost escalation and power and transport pass-through clauses (Our Business, p.327), and the DRHP warns these may carry fixed-price periods, exclusions or time lags (p.32). It does not quantify the lag or the share of merchant volume sold on purchase orders rather than contracts.
Net read: the swing factors are the timing of new on-site plants and merchant pricing; a 10% EBITDA miss at 55x takes value to about Rs 1,377 a share, 14% below the desk price.
What governance, litigation and family-structure risks sit around INOX Air Products?
INOX Air Products is run under a 1999 joint venture contract between Air Products and the Jain family that terminates on listing, while a 30 June 2027 long-stop revives it if the IPO does not happen (DRHP History, p.353). The DRHP discloses no material civil case against the company.
Governance terms that change at listing
DRHP History and Certain Corporate Matters, shareholders' agreements (p.353 to 354).
Term | Before listing (waiver cum amendment agreement) | At listing |
|---|---|---|
Joint venture contract of 25 January 1999 | Amended and partly waived from 30 Sep 2026 | Terminates on listing, except governing law, disputes and confidentiality |
Board | Up to 8: 4 independent, 2 Jain family nominees, 2 Air Products nominees, while the two groups are within 20 percentage points of each other | Nomination rights go to shareholders for a special resolution within three months of listing |
Chair and managing director | Pavan Kumar Jain chairs; Siddharth Jain is MD to 31 March 2033, then the MD role rotates in five-year terms | Same terms, subject to shareholder approval |
If not listed by 30 June 2027 | The waiver ends and the original contract, including transfer restrictions, is reinstated | n/a |
Each group after the OFS (derived) | Air Products 42.28%; Jain family group 42.28% | Equal; the two sell almost the same number of shares |
Air Products sells 38,578,328 shares and the Jain family group 38,578,335 (DRHP cover); Priveq arithmetic gives both 42.28% after the OFS.
Disclosed matters, each with its latest dated step:
Narmadapuram accident. A fire during depressurisation of a liquid oxygen tanker in FY26 burned an employee. A show cause notice of 9 January 2026 was answered on 21 January 2026, and the state filed a criminal complaint on 9 February 2026 against Pavan Kumar Jain as occupier and a plant manager. It is pending; the DRHP says no summons has been received, and Priveq found no later hearing date (p.556 and p.559).
Cyber fraud. Unauthorised transfers of Rs 10.35 crore were made through impersonation of the managing director; an FIR was filed on 16 June 2026 and an application for release of held funds on 4 July 2026 is pending (p.557 to 558). No later step was found.
Indirect tax. 60 proceedings involving Rs 22.15 crore, excluding interest and penalty (p.558).
Contingent liabilities. Rs 25.52 crore at 31 March 2026, mostly excise and service tax (Rs 18.83 crore) (p.87, derived total).
Promoter-group exemption. The company has asked SEBI, on 7 May 2026, not to classify Vivek Kumar Jain and his businesses as promoter group, based on a 22 May 2021 family settlement. Gujarat Fluorochemicals and GFCL EV Products are not treated as related parties from 27 October 2021 (risk factors 42 and 43, p.60 to 61).
The family settlement point matters for readers who confuse INOX names. INOX Clean Energy, whose IPO observations SEBI has kept in abeyance according to press reports of its 1 October 2026 processing status, belongs to Vivek Kumar Jain's INOXGFL group, not to the INOX Air Products promoters. The DRHP does not link the two IPOs, and Priveq makes no inference about SEBI's handling of either.
Net read: none of the disclosed matters is large against a Rs 82,726 crore market value. The items to track are SEBI's ruling on the exemption and the 30 June 2027 long-stop.
The Desk View
Our stated position is that INOX Air Products at a desk price of Rs 1,600 (18 November 2026) sits near the top of what the filings support, at 57.6x FY26 operating EBITDA against a listed-peer range of 34.5x to 64.39x. Desk prices reflect unlisted market activity in a 0.51% float and are not an independent Priveq valuation call.
The business is real and contracted. Operating EBITDA rose from Rs 1,146.31 crore (FY24) to Rs 1,421.36 crore (FY26) at a 46.85% margin, and on-site plants on 15 to 20-year take-or-pay contracts are the fastest-growing part.
The headline EBITDA flatters the multiple. The DRHP's Rs 1,647.79 crore includes Rs 226.43 crore of other income and a one-time joint venture gain, so the desk price is about 58x operating EBITDA, not 50x.
Cash is being reinvested, not returned. Three years of capex absorbed all operating cash, and the dividend is 2.26% of profit.
The range is Rs 1,250 to Rs 1,670, with an error bar. That is 45x to 60x FY26 operating EBITDA; a 10% EBITDA miss moves each end down by about Rs 124 to Rs 165 a share.
The one variable that would change this position is how fast the Rs 1,414.74 crore of capital work-in-progress turns into operating EBITDA. About 15% growth on FY26 would put Rs 1,600 (18 November 2026) at 50x, mid-range; flat EBITDA would leave it at Linde India's multiple.
What does this mean, by situation?
None of this is advice; it is what to watch in each position.
If you already hold this position: compare any price band with the Rs 1,250 to Rs 1,670 bracket, and check the RHP for FY27 half-year operating EBITDA against FY26's Rs 1,421.36 crore. The OFS does not dilute you, because no new shares are issued.
If you are evaluating a first position: convert any quoted price to today's Re 1 share first; prices from before June 2026 differ by a factor of 50. Note that the 0.51% float makes unlisted prices thin.
If you are advising a client on this: point to the operating EBITDA bridge, the three years of negative cash after capex, the related-party asset purchases and the pending SEBI exemption on promoter-group disclosure. Lock-in for pre-IPO shares is set in SEBI rules and the RHP.
What to watch, with dates:
SEBI observations: not issued as of 18 November 2026; filing listed 5 October 2026
Promoter-group exemption: applied 7 May 2026; not granted at the DRHP date
RHP and price band: not announced; the RHP will add later financials
Long-stop for the joint venture waiver: 30 June 2027
Narmadapuram complaint and cyber-fraud application: both pending, no next date found
FAQs
Why does INOX Air Products show two different EBITDA figures?
The DRHP's Rs 1,647.79 crore EBITDA includes other income and a one-time joint venture gain; operating EBITDA, revenue less operating costs, is Rs 1,421.36 crore. Valuing on the narrower figure gives about 57.6x at the desk price, against 49.68x on the DRHP figure.
What is the INOX Air Products unlisted share price today?
INOX Air Products' desk price is Rs 1,600 per Re 1 share as of 18 November 2026. Desk prices are indicative, depend on unlisted market activity and move, so confirm with the desk before any transaction.
Is the INOX Air Products IPO price band announced?
No, the price band is not announced as of 18 November 2026. The DRHP of 30 September 2026 leaves price, issue value and dates blank, and SEBI has not issued observations.
What is still unconfirmed about the INOX Air Products IPO?
→ Several items are not yet confirmed by a filing. The open items are:
SEBI's observations and the RHP date
The price band and the rupee size of the OFS
SEBI's decision on the promoter-group exemption
The basis of the reported Rs 10,000 to 11,000 crore issue size
How much of the Rs 1,414.74 crore of plants under construction is contracted
Does INOX Air Products get any money from the IPO?
No, the company receives nothing, because the IPO is entirely an offer for sale. Air Products' Prodair Corporation and four Jain family entities sell up to 77,156,663 shares between them.
Was the INOX Air Products share price adjusted for the 2026 split and bonus?
Yes, the Rs 1,600 desk price (18 November 2026) and the DRHP's per-share data are on today's Re 1 share. Divide any price per old Rs 10 share by 50; the 1999 price of Rs 375 becomes Rs 7.50.
Is INOX Air Products part of the INOXGFL group or INOX Clean Energy?
No, INOX Air Products belongs to Pavan Kumar Jain's side of the INOX family, jointly with Air Products. INOX Clean Energy is part of Vivek Kumar Jain's INOXGFL group under a 2021 family settlement.
Should I be worried that INOX Air Products pays almost no dividend?
It shows where the cash goes rather than a problem by itself. FY26 dividend was Rs 20.68 crore, 2.26% of profit, because capex absorbed nearly all operating cash for three years.
How does INOX Air Products' valuation compare with Linde India?
At the desk price, INOX Air Products is valued at 57.6x FY26 operating EBITDA against Linde India's 64.39x, on Priveq-derived figures read 18 November 2026. Ellenbarrie, the smaller peer, is at 34.5x.
How can I buy INOX Air Products unlisted shares?
You can express interest on the INOX Air Products page on Priveq Marketplace or message the desk on WhatsApp at +91 82874 66698. Pre-IPO shares are illiquid and lock-in after listing follows SEBI rules.
What We Can And Cannot Stand Behind
Primary-sourced and verified
The offer: 77,156,663 Re 1 shares, all OFS, sellers and certified acquisition costs (DRHP cover)
The share base: 517,034,850 shares after the June 2026 split and the 4 September 2026 bonus; no options granted
Restated FY24 to FY26 financials, KPIs, vertical revenue, customer concentration and related-party transactions
Shareholding: promoters and group 99.49%, public 0.51%
The joint venture contract's termination on listing and the 30 June 2027 long-stop
The litigation and the SEBI exemption application as disclosed
The equity ISIN INE321A01020, active for Re 1 shares on NSDL's securities search (18 November 2026)
Demat status: 0.43% of shares in demat at 31 March 2026 (FY26 MGT-7) and 99.93% at 29 September 2026 (DRHP); 58 shareholders of record
Indicative or derived by Priveq
Operating EBITDA (Rs 1,421.36 crore) and its bridge to the DRHP's EBITDA; cash after obligations
All multiples, the Rs 1,250 to Rs 1,670 bracket, the EBITDA the desk price needs, the sensitivity grid
Post-offer holdings of 42.28% for each group
The reading that the 29% "rental and leasing" share of turnover in the annual return reflects on-site plant leases
Peer multiples, from Screener read on 18 November 2026, which do not deduct peers' bank deposits
The desk price of Rs 1,600 and the Rs 425.14 crore value of the public float at that price
Could not be confirmed
SEBI's observation date and the RHP date; the price band
The reported Rs 10,000 to 11,000 crore issue size (PTI, unnamed sources, 1 October 2026)
SEBI's decision on the promoter-group exemption
Nexdigm's role and method behind the market-size charts; the full CRISIL report, read in full, does not explain it
The time lag in merchant power-cost pass-through, and the rupee split of capital work-in-progress between on-site and merchant projects; the DRHP gives neither
Primary Sources
Company documents (SEBI-hosted)
Draft Red Herring Prospectus, INOX Air Products Limited, 30 September 2026: cover; Summary of Financial Information (printed pp.82 to 88); Capital Structure (pp.102 to 149); Basis for Offer Price (pp.161 to 170); Industry Overview (pp.178 to 297, market size pp.205 to 206); Our Business (p.298); History and Certain Corporate Matters (pp.345 to 354); MD&A (pp.518 to 529); Outstanding Litigation (pp.554 to 559); risk factors 1, 11, 42, 43, 46
Regulator and depository records
NSDL securities search: INE321A01020, read 18 November 2026: INOX Air Products Limited equity shares, face value Re 1, status active
SEBI Public Issues, Draft Offer Documents: INOX Air Products DRHP, read 18 November 2026 to confirm no newer filing
Company website
INOX Air Products investor page: FY26 annual report and offer documents
CRISIL Intelligence, "Assessment of Industrial Gas Industry" and addendum, dated 2 April 2026, read in full (158 pages): market size charts sourced Nexdigm (pp.21 to 40); financial and operational profiling of key players (pp.147 to 155). Commissioned and paid for by the company
Form MGT-7, annual return for FY2025-26: principal business activities; share capital break-up into physical and demat at 31 March 2026. The ISIN field in this return is blank
Secondary sources
Screener pages for Linde India (consolidated) and Ellenbarrie Industrial Gases, read 18 November 2026 at 4:01 pm, for peer prices and FY26 operating profit
PTI report carried by CNBC-TV18, 1 October 2026, for the reported issue size
Talk to the desk: WhatsApp +91 82874 66698 | support@priveq.in | View INOX Air Products on the Priveq Marketplace
Disclaimer: This piece reflects Priveq India's (Priveq Investech Private Limited, Priveq.in) own research, based on primary filings, regulatory disclosures, and INOX Air Products Limited's draft red herring prospectus dated 30 September 2026 as detailed above. It is not investment advice, and does not allege any wrongdoing, misstatement, or violation by INOX Air Products Limited; the related-party transactions, litigation, cash flow trends and EBITDA definitions noted in this piece are read directly from the company's own public disclosures. Priveq Investech Private Limited is not registered with the Securities and Exchange Board of India (SEBI) as a stock broker, investment adviser, or research analyst. This piece is independent desk research and commentary, not "research" as defined under the SEBI (Research Analysts) Regulations, 2014, and should not be construed as investment advice from a SEBI-registered entity. Priveq transacts as a named counterparty in the unlisted shares discussed here, including INOX Air Products Limited, and may hold or deal in these shares before, during, or after publication; our commercial interest and the views in this piece sit in the same place, and should be weighed accordingly. Desk prices are indicative, subject to change without notice, and should be confirmed directly with the desk before any transaction. Unlisted securities are illiquid, carry a high risk of loss, and may be difficult to value or sell; prices move sharply and without notice. Readers should independently verify all figures against the company's own filings and consult qualified financial and legal advisors before transacting. Past performance and price appreciation referenced here are not indicative of future results.