

The Short Version
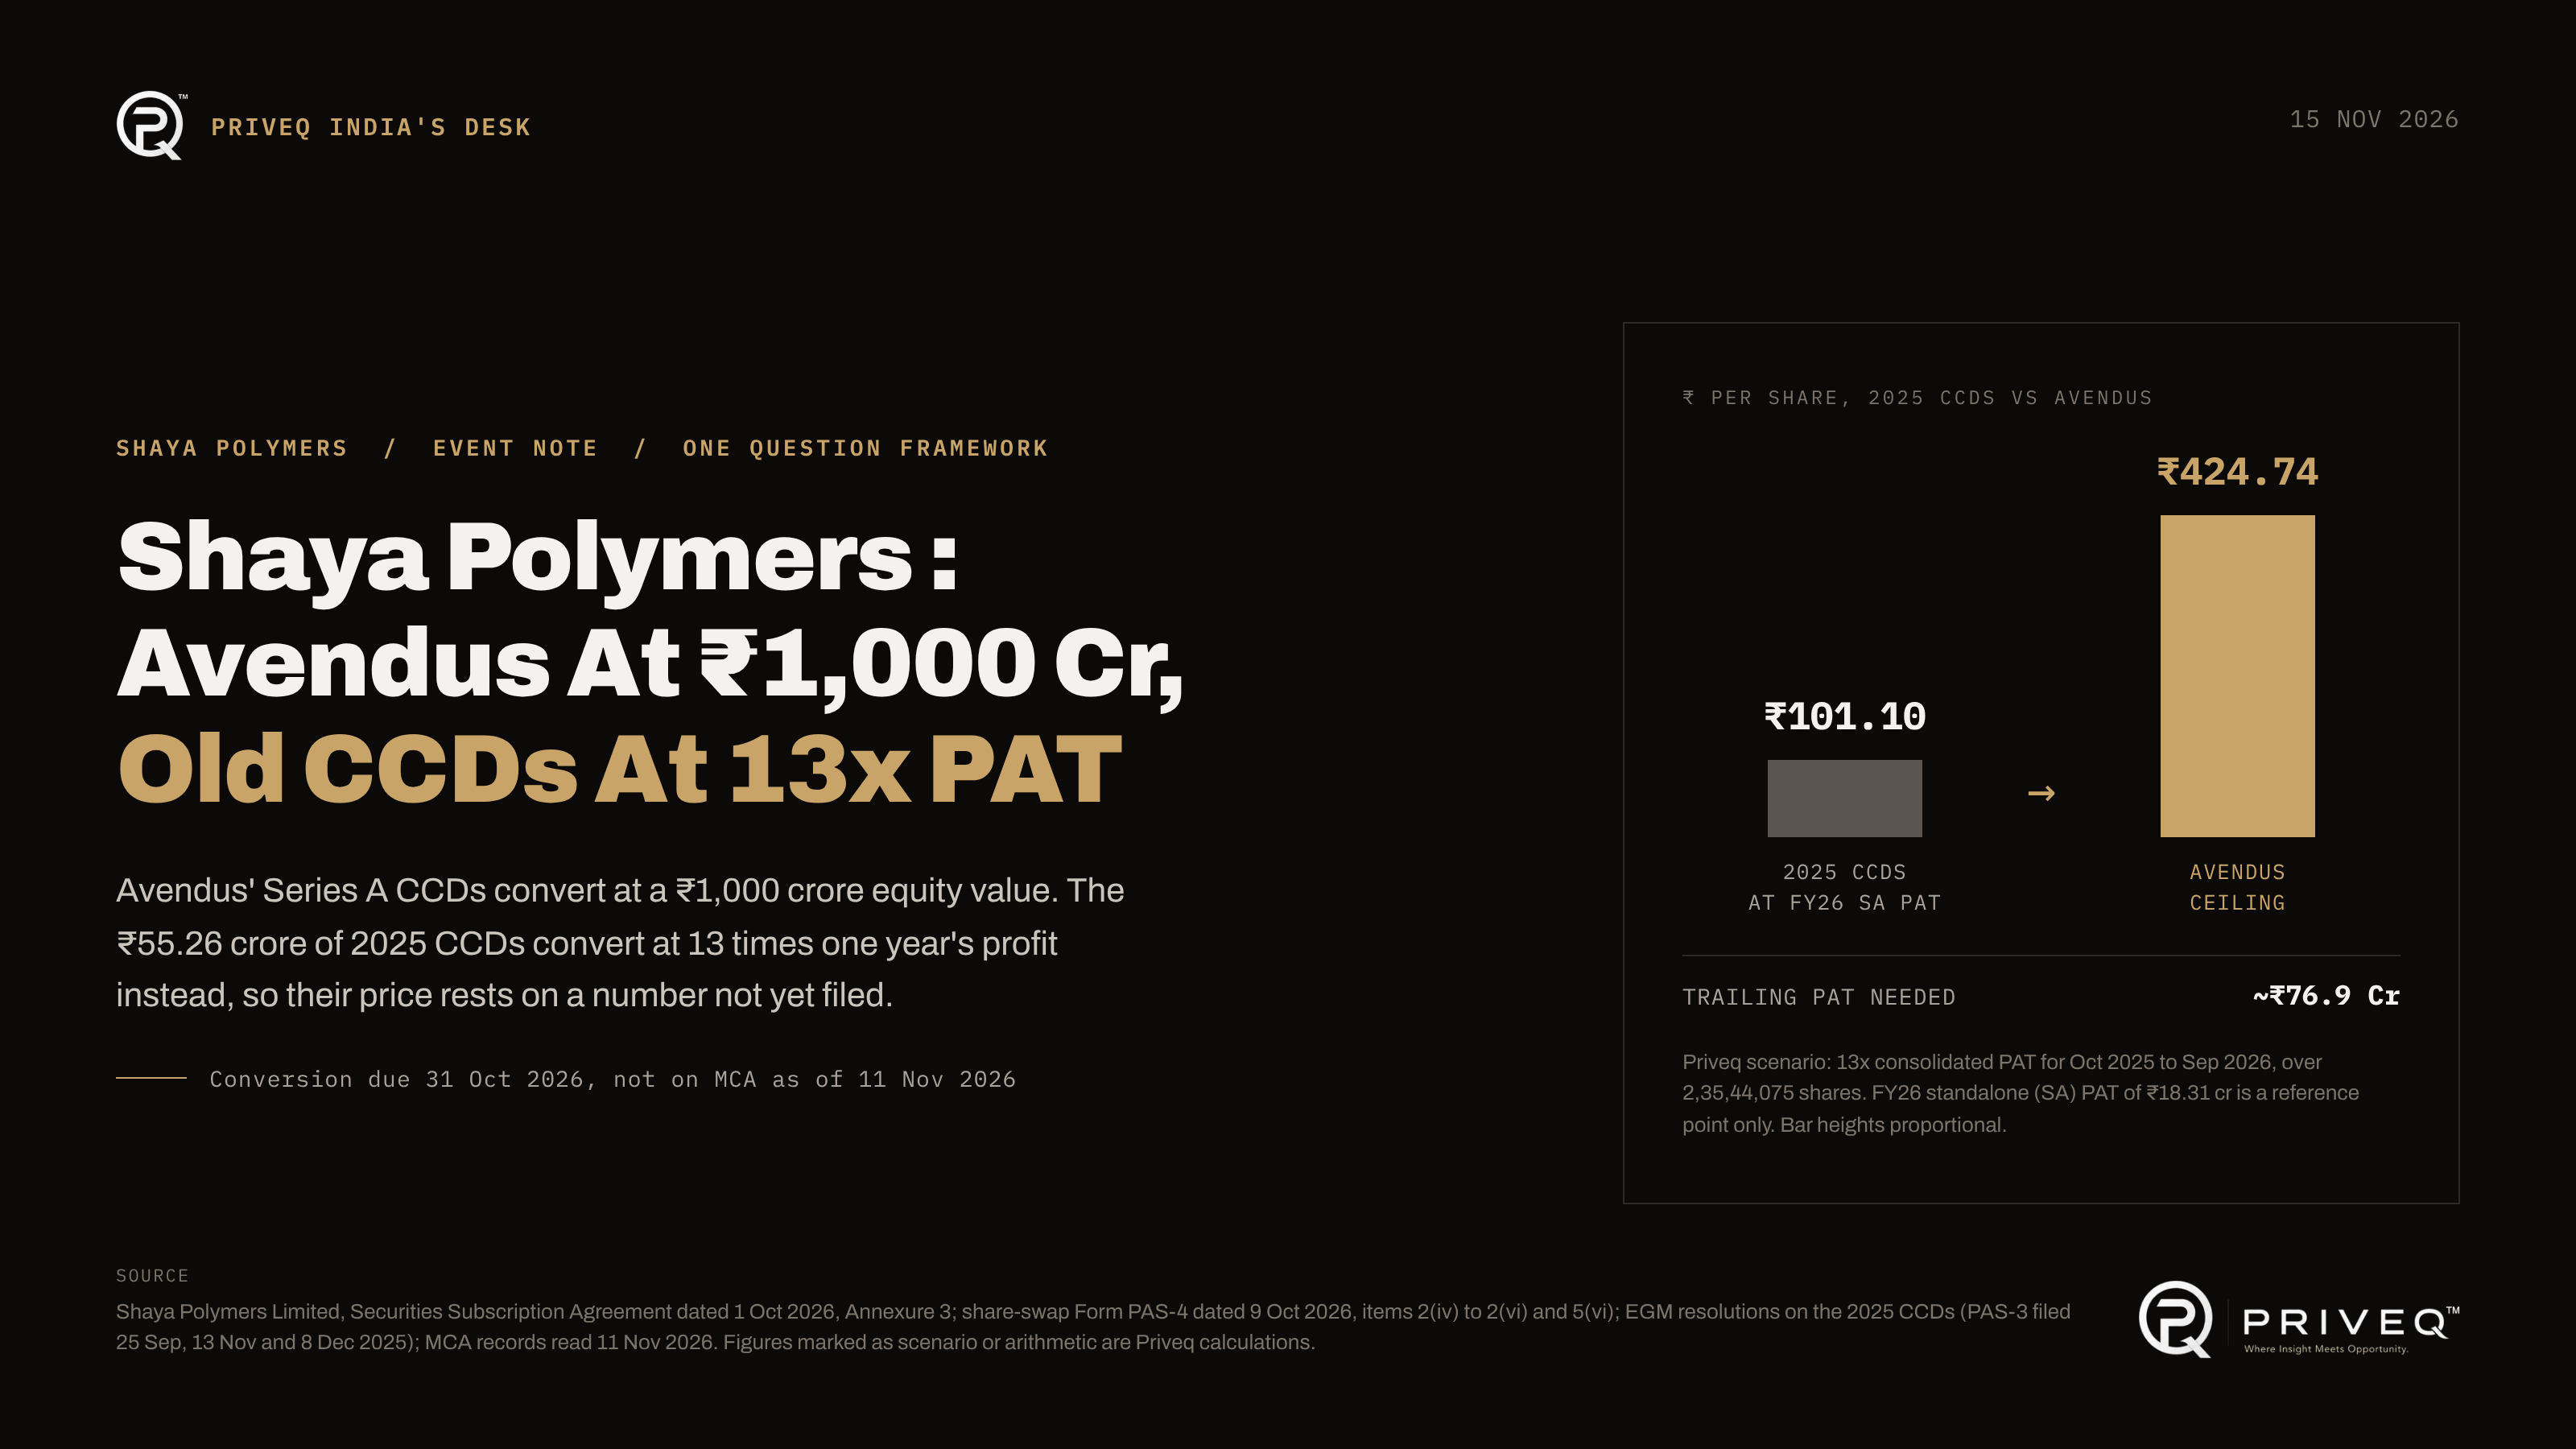
Shaya Polymers Limited allotted Rs 25 crore of Series A compulsorily convertible debentures (CCDs) and Rs 55 crore of secured non-convertible debentures to Avendus Structured Credit Fund III on 6 October 2026, fixing a Rs 1,000 crore equity value for Avendus' conversion. Shaya Polymers' older Rs 55.26 crore of 2025 CCDs convert on a different rule, 13 times consolidated profit for October 2025 to September 2026, so their holders get Avendus' price only if that year's profit reaches about Rs 77 crore. FY26 standalone profit was Rs 18.31 crore. At that level the formula would price the 2025 CCDs near Rs 101 a share against Rs 424 to Rs 425 in three October 2026 filings, and issue about 54.7 lakh new shares. The conversion was due on 31 October 2026 and had not been filed with the Ministry of Corporate Affairs (MCA) as of 11 November 2026, so the real number is still open.
Event: Private placement of Series A CCDs and Series A NCDs to Avendus Structured Credit Fund III
Date: 6 October 2026 (allotment); Securities Subscription Agreement dated 1 October 2026
Source: Form PAS-3 returns filed with MCA on 6 and 10 October 2026, with Form PAS-4 offer letters and the SSA
Primary Metric Affected: Equity value (Rs 1,000 crore entry valuation) and gross debt (+Rs 55 crore)
For the company profile, financials and the live desk price, see Shaya Polymers on the Priveq Marketplace.
What Avendus Bought, and What It Lent
Shaya Polymers filed two Form PAS-3 returns of allotment in October 2026, both for allotments made on 6 October 2026 to one investor, Avendus Structured Credit Fund III, a Category II alternative investment fund in Mumbai. The board approved the issues on 24 September 2026 and shareholders passed special resolutions at an extraordinary general meeting on 28 September 2026 (CCD PAS-4, Form PAS-5, p. 25).
The two Avendus allotments of 6 October 2026 (Rs crore unless stated)
Term | Series A CCDs | Series A NCDs |
|---|---|---|
Allottee | Avendus Structured Credit Fund III (Category II AIF) | Avendus Structured Credit Fund III (Category II AIF) |
Number x face value | 250 x Rs 10,00,000 | 550 x Rs 10,00,000 |
Amount raised | 25.00 | 55.00 |
Tenure | 60 months | 36 months (final redemption 5 Oct 2029) |
Stated rate | 9% p.a. coupon, paid quarterly | 15.25% p.a. |
One-time initial coupon | 1.5% of subscription | 1.5% of subscription |
Security | Unsecured | Charge on all assets, pledge over 51% of shares (fully diluted), Rs 3 crore DSRA |
How it ends | Converts to equity at the Rs 1,000 crore Series A entry valuation | Principal repaid in instalments from Feb 2028, with redemption premium from May 2028 to Oct 2029 |
Source: Board resolutions and lists of allottees dated 6 Oct 2026 (Form PAS-3, filed 6 Oct and 10 Oct 2026); Form PAS-4 offer letters dated 6 Oct 2026, item 2(xvi) (p. 9), item 2(xx) (p. 10) and Annexure III (pp. 20-21); Securities Subscription Agreement dated 1 Oct 2026, Annexure 3, clauses IV and V (PDF pp. 85-87). All disclosed.
Shaya Polymers' Securities Subscription Agreement (SSA) with Avendus, dated 1 October 2026, reaches beyond the October allotments:
Series B CCDs of up to Rs 20 crore (200 x Rs 10 lakh), in one or more tranches, at a valuation still to be agreed (SSA Recital C, PDF p. 7; Annexure 3 definitions, PDF p. 86).
More NCD room. Shareholders approved up to 1,000 Series A NCDs, or Rs 100 crore; 550 were issued (NCD board resolution, p. 1).
Use of the CCD money. Up to Rs 45 crore for capital expenditure, acquisitions and working capital, then up to Rs 15 crore to refinance existing debt, with the balance for transaction costs and general purposes (SSA clause 2.7.1, PDF p. 26).
A higher borrowing ceiling. Two days after the EGM, the 30 September 2026 AGM raised the board's borrowing limit from Rs 300 crore to Rs 500 crore and adopted the FY26 audited accounts (AGM resolutions, items 1 and 3).
Three Prices in One Month
Shaya Polymers' equity was priced three times between 20 September and 9 October 2026, and all three land within a rupee of each other.
Every price on Shaya Polymers equity since May 2025 (Rs; equity value in Rs crore)
Date | Event | Equity value | Per share | Basis |
|---|---|---|---|---|
22 May 2025 | Private placement, 12,13,700 shares | 549.99 (valuer basis) | 247.20 | Disclosed: valuation report dated 9 May 2025, valuation date 31 Mar 2025 |
30 Sep 2025 | Registered valuer DCF (report 1 Nov 2025) | 961.83 | 410 | Disclosed |
11 Nov and 5 Dec 2025 | Equity allotments, 48,781 and 32,929 shares | 961.83 (valuer basis) | 410 | Disclosed: EGM resolution prices the shares on the 1 Nov 2025 report |
31 Aug 2026 | Registered valuer DCF (report 20 Sep 2026) | 998.27 | 424 | Disclosed |
1 Oct 2026 | Avendus Series A CCD entry valuation | 1,000.00 | up to 424.74 | Value disclosed; per share derived |
9 Oct 2026 | Share swap offer for 20% of Climate Changers, 1,88,235 shares | 998.27 (valuer basis) | 425 | Disclosed: PAS-4 cites the 20 Sep 2026 report; allotment not yet filed |
14 Nov 2026 | Priveq desk price | 1,083.03 | 460 | Desk price as of 14 Nov 2026; value derived |
Source: Board resolution of 22 May 2025 approving the allotment and the valuation report dated 9 May 2025 (PAS-3 filed 22 May 2025; later PAS-4s give the date as 16 May 2025, which is the EGM date); Form PAS-4 dated 13 Nov 2025 and 8 Dec 2025, item 2(xiii) (p. 5); EGM notice and special resolution of Nov 2025 (item on the valuation report); valuation reports by Ramji Mahadevan, IBBI registered valuer, p. 2 of each (attached to PAS-3 filed 5 Dec 2025 and MGT-14 filed 6 Nov 2026); SSA dated 1 Oct 2026, Annexure 3, clause IV definitions (PDF p. 86); share-swap Form PAS-4 dated 9 Oct 2026, items 2(iv) to 2(vi) (pp. 6-7). Per-share figures for the Avendus entry and the desk equity value are Priveq arithmetic on 2,35,44,075 shares (PAS-4 dated 6 Oct 2026, item 2(xxii), p. 10).
Priveq arithmetic: the Avendus conversion price
The SSA sets Avendus' conversion shares as the outstanding CCD amount divided by the Series A Entry Valuation of Rs 10,000,000,000 (Rs 1,000 crore), times the fully diluted share count just before the investment (SSA Annexure 3, clause IV(b) and definitions, PDF pp. 85-86).
Rs 1,000 crore / 2,35,44,075 shares in issue = Rs 424.74 per share, a ceiling. If the 2025 CCDs are counted in the fully diluted base, the per-share price falls.
Rs 25 crore against Rs 1,000 crore gives Avendus about 2.44% fully diluted after conversion, before accrued coupon and costs, which the SSA adds to the converting amount.
Shaya Polymers' registered valuer put the whole company at Rs 998.27 crore, or Rs 424 a share, as of 31 August 2026 (valuation report, 20 Sep 2026, p. 2). Three days after the Avendus allotment, the board offered 1,88,235 new shares at Rs 425 to a director for the remaining 20% of its subsidiary Climate Changers - Technology Solutions, citing that same report (share-swap PAS-4, items 2(iv) to 2(vi), pp. 6-7). The Priveq desk price of Rs 460 as of 14 November 2026 sits about 8.3% above that cluster.
The 2025 CCDs Convert on a Different Rule
Shaya Polymers sold Rs 55.26 crore of CCDs in three tranches in 2025, on 24 September (Rs 11.305 crore), 13 November (Rs 11.00 crore) and 8 December (Rs 32.95 crore). All three carry the same conversion clause, set out in the EGM resolutions and repeated in the company's letters explaining why no valuation report was attached at issue:
Formula. Conversion price = consolidated audited profit after tax for 1 October 2025 to 30 September 2026, multiplied by a price-to-earnings multiple of 13, divided by fully diluted equity shares immediately before conversion (EGM notice, Nov 2025, p. 2; clarification letter, p. 1; Dec 2025 EGM notice, p. 2; Sep 2025 PAS-3, resolution annexure).
Date. Compulsory conversion on 31 October 2026, with a coupon of 0.001%.
Valuer. The price is to be set by a registered valuer's report dated no earlier than 30 days before conversion.
The formula ties the 2025 CCD holders' entry value to 13 times one year's profit, whatever any valuer or investor says the company is worth. That makes the conversion very sensitive to the profit number:
The Rs 55.26 crore of 2025 CCDs, and what the 13x formula does at different profit levels
Trailing consolidated PAT, Oct 2025 to Sep 2026 (Rs crore) | Equity value at 13x (Rs crore) | Conversion price (Rs) | New shares issued | Dilution of shares in issue |
|---|---|---|---|---|
18.31 (FY26 standalone PAT, used only as a reference point) | 238.0 | 101.10 | 54,65,395 | 23.2% |
25 | 325.0 | 138.04 | 40,02,855 | 17.0% |
40 | 520.0 | 220.86 | 25,01,784 | 10.6% |
60 | 780.0 | 331.29 | 16,67,856 | 7.1% |
76.92 (profit needed to match Avendus' Rs 1,000 crore) | 1,000.0 | 424.74 | 13,00,928 | 5.5% |
Source: Conversion formula from the EGM notices and special resolutions attached to the PAS-3 filed 25 Sep 2025, 13 Nov 2025 and 8 Dec 2025, and the company's clarification letters of Nov and Dec 2025: consolidated audited PAT for 1 Oct 2025 to 30 Sep 2026, multiplied by 13, divided by fully diluted shares immediately before conversion. Tranches: Rs 11.305 crore (24 Sep 2025), Rs 11.00 crore (13 Nov 2025), Rs 32.95 crore (8 Dec 2025). Every row is a Priveq scenario on 2,35,44,075 shares; the actual trailing PAT and share count are not filed. FY26 standalone PAT from share-swap Form PAS-4 dated 9 Oct 2026, item 5(vi), p. 14.
What the table says, in one line: profit of about Rs 76.9 crore for October 2025 to September 2026 puts the 2025 CCDs at the Avendus price. Every rupee short of that issues more shares to them, and dilutes everyone else, Avendus' conversion base included.
Shaya Polymers' FY26 standalone profit after tax was Rs 18.31 crore on revenue of Rs 99.70 crore (share-swap PAS-4, item 5(vi) and 5(viii), p. 14). That is a different period and a different basis from the formula's consolidated October-to-September year, so it is a reference point only. The registered valuer's FY27 projection, by contrast, is Rs 77 crore of profit, which at 13 times gives almost exactly Rs 1,000 crore.
The Debt Leg: What Rs 55 Crore at 15.25% Costs
Shaya Polymers' NCDs are the larger part of the Avendus package and the more expensive. The NCD offer letter shows a one-time 1.5% initial coupon, quarterly interest from November 2026, and principal repaid in instalments from February 2028, with a redemption premium added from May 2028 to the final date of 5 October 2029 (Annexure III, pp. 20-21).
What the Avendus package costs in cash, against the last two years (Rs crore)
Line | Amount | Provenance |
|---|---|---|
One-time initial coupons due 5 Nov 2026 (NCD 0.825 + CCD 0.375) | 1.20 | Disclosed (Annexure III cash flows) |
NCD interest, four quarterly payments Feb to Nov 2027 | 5.16 | Disclosed schedule, summed by Priveq |
CCD coupon, four quarterly payments Feb to Nov 2027 | 2.27 | Disclosed schedule, summed by Priveq |
Annual cash coupon on the package (2027) | 7.43 | Derived |
FY25 consolidated finance costs | 2.63 | Disclosed (audited) |
FY25 consolidated EBITDA | 18.91 | Derived from audited P&L |
FY26 standalone profit before tax | 24.53 | Company-disclosed (PAS-4, 9 Oct 2026) |
Total NCD payments to Avendus over three years, on Rs 55 crore | 78.35 | Disclosed schedule, summed by Priveq |
Source: Form PAS-4 (NCD) and Form PAS-4 (CCD) dated 6 Oct 2026, Annexure III (pp. 20-21); FY2024-25 consolidated statement of profit and loss (AOC-4 XBRL filed 13 Dec 2025, p. 2); share-swap Form PAS-4 dated 9 Oct 2026, item 5(vi), p. 14. EBITDA is Priveq arithmetic: profit before tax 14.56 + finance costs 2.63 + depreciation and amortisation 1.99, less other income 0.28.
Priveq scenario: the interest load, not company guidance
Cash coupons on the two Avendus instruments come to about Rs 7.43 crore in 2027, plus Rs 1.20 crore of initial coupons in November 2026.
That is almost three times FY25 consolidated finance costs of Rs 2.63 crore, about 39% of FY25 EBITDA of Rs 18.91 crore, and about 30% of FY26 standalone profit before tax of Rs 24.53 crore.
Avendus receives Rs 78.35 crore over three years on the Rs 55 crore NCD under the illustrative schedule. Priveq's XIRR on those cash flows is about 17% including the initial coupon, above the stated 15.25%, which may reflect how the issuer defines the rate.
Key assumption: FY26 consolidated EBITDA is not filed. If the business is close to the valuer's FY27 path, the load is modest; if it is closer to FY26 standalone profit, it is heavy.
Shaya Polymers' NCD security package is wide. The debenture trustee, CTL Trusteeship Limited, gets a first-ranking charge on all existing and future fixed, current and immovable assets, a Rs 3 crore debt service reserve, and an exclusive pledge over 51% of the company's shares on a fully diluted basis with a power of attorney (NCD PAS-4, item 2(xx), p. 10). The same filing shows promoters at 44.50% and directors and relatives at 6.79%, 51.29% together (item 2(xxii), p. 10). It does not say whose shares make up the pledged 51%.
The Conditions Attached
Shaya Polymers and its promoters accepted these protections for Avendus in the SSA:
Exit deadline. The company must give Avendus an exit through a Qualified IPO or a strategic sale within 60 months of the first closing, so by about October 2031 (SSA Annexure 10, clause 1, PDF p. 122).
Put option. Avendus can require the company and/or the promoters to buy or redeem its securities at fair market value set by an independent valuer, including accrued coupon, but not within 12 months of allotment (SSA clauses 1.1.124 to 1.1.126, PDF pp. 19-20; Annexure 3, put option clause, PDF pp. 92-93).
Anti-dilution. If equity is issued below Avendus' effective conversion price, Avendus gets broad-based weighted-average protection (Annexure 3, clause XI, PDF p. 92). The filings do not say whether a 2025 CCD conversion below that price would count as such an issue.
Payout block. No payment to shareholders in any form while any CCD coupon is unpaid (Annexure 3, clause V, PDF p. 87).
For unlisted shareholders, the exit clause is the closest thing to a stated IPO timeline in any Shaya Polymers filing. The PAS-4 records no change in control from the issue (item 2(xii), p. 8).
Multiples on Reported and Projected Profit
Multiples at the Avendus entry value and the desk price, on the last two reported years
Metric | Base figure (Rs crore) | At Avendus entry (Rs 1,000 cr) | At desk price (Rs 1,083.03 cr, 14 Nov 2026) |
|---|---|---|---|
P/E on FY25 consolidated Group PAT | 9.98 | 100.2x | 108.5x |
P/E on FY26 standalone PAT | 18.31 | 54.6x | 59.1x |
P/E on the valuer's FY27 projected PAT | 77 (projection) | 13.0x | 14.1x |
EV/EBITDA on FY25 consolidated | 18.91 EBITDA; 81.74 net debt | 57.2x | 61.6x |
P/B on FY26 standalone net worth | 170.11 | 5.9x | 6.4x |
Price to sales on FY26 standalone revenue | 99.70 | 10.0x | 10.9x |
Source: FY2024-25 consolidated statements (AOC-4 XBRL filed 13 Dec 2025, pp. 1-2); FY2025-26 standalone figures from share-swap Form PAS-4 dated 9 Oct 2026, items 5(vi) to 5(viii), pp. 14-15 (FY26 consolidated accounts not on MCA as of 11 Nov 2026); FY27 projection from the valuation report dated 20 Sep 2026, p. 2. All multiples are Priveq arithmetic. The FY27 row is built on a management projection, not a result.
For a manufacturer funding acquisitions and capacity with debt, EV/EBITDA is the more honest lens than P/E, because it counts the Rs 81.74 crore of FY25 net debt that P/E ignores; FY26 consolidated EBITDA is not yet filed, so it can only be run on FY25. Read across the rows, the prices look stretched on what Shaya Polymers has reported and modest on what its valuer projects. The gap between those two rows is the investment question.
What Is Still Open
The 2025 CCD conversion. Due 31 October 2026; no PAS-3 on MCA as of 11 November 2026. A return of allotment is due within 30 days of allotment, so it should appear by early December 2026 if conversion happened on time.
FY26 consolidated accounts. Adopted at the 30 September 2026 AGM, but the AOC-4 was not on MCA as of 11 November 2026. These give the profit the 13x formula needs, though the formula's year runs October to September.
The share swap. 1,88,235 shares at Rs 425 offered on 9 October 2026; no PAS-3 yet.
Series B CCDs. Up to Rs 20 crore more, at a valuation not yet agreed.
Existing debt schedule. The SSA's Annexure 9 lists existing financial indebtedness, but the scan was too poor to read reliably, so how much costlier debt the Rs 15 crore refinancing allowance retires is not confirmed here.
The Desk View
Shaya Polymers now has an institutional price on its equity, and a clause that may issue shares well below it.
The anchor is real. A credit fund with full diligence, a valuer and a share-swap counterparty all priced the company at Rs 998 crore to Rs 1,000 crore within three weeks. That is a firmer reference than any single report.
The 2025 CCDs are the swing factor. Their conversion price is set by one year's profit at 13 times. Unless that profit is close to the valuer's FY27 plan, they convert at a fraction of Rs 424, and the dilution lands on every other holder.
The debt sets the clock. Rs 55 of every Rs 80 is secured debt at 15.25%, amortising from 2028, with a five-year exit commitment behind it.
Our read: the next two filings, the 2025 CCD conversion return and the FY26 consolidated accounts, will tell readers more about the value of a Shaya Polymers share than the Rs 1,000 crore headline does.
FAQs
At what valuation did Avendus invest in Shaya Polymers?
Avendus' Series A CCDs convert at a Rs 1,000 crore equity value, set in the Securities Subscription Agreement dated 1 October 2026. On the 2,35,44,075 shares in issue that is at most Rs 424.74 a share (SSA Annexure 3, PDF p. 86).
How will Shaya Polymers' 2025 CCDs convert?
They convert at 13 times consolidated profit for October 2025 to September 2026, divided by fully diluted shares. Profit of about Rs 76.9 crore matches Avendus' price; lower profit means a lower price and more new shares.
Has the October 2026 CCD conversion been filed yet?
No conversion return was on MCA as of 11 November 2026. The conversion was due on 31 October 2026, so the PAS-3 should appear within 30 days of allotment.
Will my Shaya Polymers shares be diluted when the 2025 CCDs convert?
Yes, existing holders will be diluted, and by how much depends on the profit figure. At Rs 25 crore of trailing profit the formula issues about 40 lakh shares, roughly 17% of today's count; at Rs 76.9 crore, about 13 lakh.
What is a compulsorily convertible debenture, and how do Avendus' CCDs work?
A CCD is a debenture that must turn into equity instead of being repaid. Avendus' CCDs pay 9% a year until conversion and convert into the stake Rs 25 crore buys at a Rs 1,000 crore valuation.
How does the Avendus valuation compare with the Priveq desk price?
The Rs 460 desk price as of 14 November 2026 is about 8.3% above Avendus' Rs 1,000 crore entry value. On 2,35,44,075 shares, Rs 460 implies Rs 1,083.03 crore before any 2025 CCD conversion.
What We Can And Cannot Stand Behind
Primary-sourced and verified
Avendus allotments of Rs 25 crore CCDs and Rs 55 crore NCDs on 6 October 2026, with tenure, coupon, security and cash-flow schedules (PAS-3, PAS-4, read from the filed scans).
The Rs 1,000 crore Series A Entry Valuation, the conversion formula, Series B CCDs, exit, put option, anti-dilution and use-of-proceeds clauses (SSA, each cited clause checked against the page image).
The 2025 CCD tranches and their 13x PAT conversion formula (EGM resolutions and clarification letters).
The Rs 998.27 crore / Rs 424 valuation and its projections; the Rs 425 share-swap offer; the 30 September 2026 AGM resolutions.
FY25 consolidated revenue, profit, equity, borrowings and cash flow (audited AOC-4).
Partially or indirectly corroborated
FY26 standalone revenue, profit and net worth: company-disclosed audited figures inside a PAS-4, not yet matched to the FY26 AOC-4.
Rs 424.74 per share and the 2.44% stake: Priveq arithmetic on disclosed inputs; a ceiling, not the conversion price.
Every row of the 2025 CCD table: Priveq scenarios on the disclosed formula.
Annual cash coupons of Rs 7.43 crore and the 17% XIRR: arithmetic on illustrative schedules that may differ from final documents.
All multiples: Priveq arithmetic; the FY27 row rests on a projection.
Could not confirm
The actual trailing profit, conversion price and new share count for the 2025 CCDs.
FY26 consolidated figures.
Whose shares make up the 51% pledge.
The contents of the SSA's existing-indebtedness annexure.
Primary Sources
Documents read, with locators. Where a link is shown, the document is a copy hosted by Priveq, because the MCA portal does not give the public a direct link to filings.
Avendus transaction (October 2026)
Securities Subscription Agreement dated 1 October 2026: Recital C (PDF p. 7), clauses 1.1.124 to 1.1.126 (pp. 19-20), clause 2.7.1 (p. 26), Annexure 3 clauses IV, V, XI and put option (pp. 85-93), Annexure 10 clause 1 (p. 122).
Form PAS-4, Series A CCDs, 6 October 2026: items 2(xii), 2(xvi), 2(xviii), 2(xxii), 5(viii); Annexure III.
Form PAS-4, Series A NCDs, 6 October 2026: items 2(xvi), 2(xx); Annexure III.
Form PAS-3 filed 6 October 2026: board resolution, CCD allotment; list of allottees.
Form PAS-3 filed 10 October 2026: board resolution, NCD allotment, pp. 1-3; list of allottees.
Valuation and share swap (September and October 2026)
Valuation report, valuation date 31 August 2026, report date 20 September 2026, Ramji Mahadevan, IBBI/RV/05/2019/10894: p. 2 (attached to Form MGT-14 filed 6 November 2026).
Form PAS-4, share swap for Climate Changers, 9 October 2026: items 2(iv) to 2(vii), 5(vi) to 5(viii), pp. 6-7 and 14-15.
AGM resolutions, 30 September 2026: items 1 and 3 (attached to Form MGT-14 filed 23 October 2026).
2025 CCDs and equity rounds
Form PAS-3 filed 25 September 2025: resolution and conversion terms.
Form PAS-4, CCDs, 13 November 2025: items 2(xiii), 2(xvi); EGM notice and resolutions; clarification letter on the conversion formula.
Form PAS-4, CCDs, 8 December 2025: items 2(xiii), 2(xvi); EGM notice and resolutions.
Board resolution approving the May 2025 allotment and valuation report, valuation date 31 March 2025, report date 9 May 2025: p. 1 and p. 2 (PAS-3 filed 22 May 2025).
Valuation report, valuation date 30 September 2025, report date 1 November 2025: p. 2 (attached to PAS-3 filed 5 December 2025).
Financial statements
Consolidated financial statements FY2024-25: balance sheet p. 1, statement of profit and loss p. 2, cash flow statement p. 3 (AOC-4 XBRL filed 13 December 2025).
Directors' report FY2024-25: item 17 (subsidiaries and acquisitions).
Registry filings were read via the MCA records of Shaya Polymers Limited (CIN U24100TN2017PLC115377) as available on 11 November 2026.
Talk to the desk: WhatsApp +91 82874 66698 | support@priveq.in | View Shaya Polymers on the Priveq Marketplace
Disclaimer :
This Event Note is written by Himanshu Singh and published by Priveq India for information only and is not investment advice, a research report or a recommendation to buy, sell or hold any security. Priveq India is not registered with SEBI as a stock exchange, investment adviser or research analyst. The analysis is independent desk research based on Shaya Polymers Limited's filings with the Ministry of Corporate Affairs listed under Primary Sources; figures marked as Priveq arithmetic or scenario are our own calculations and are not company disclosures or guidance. Unlisted shares carry risks including illiquidity, valuation uncertainty and limited regulatory disclosure, and the desk price shown is indicative as of the date stated. Priveq India (Priveq Investech Private Limited, Priveq.in) is the named counterparty on transactions executed through the platform. Investors should do their own due diligence and consult a qualified adviser.