

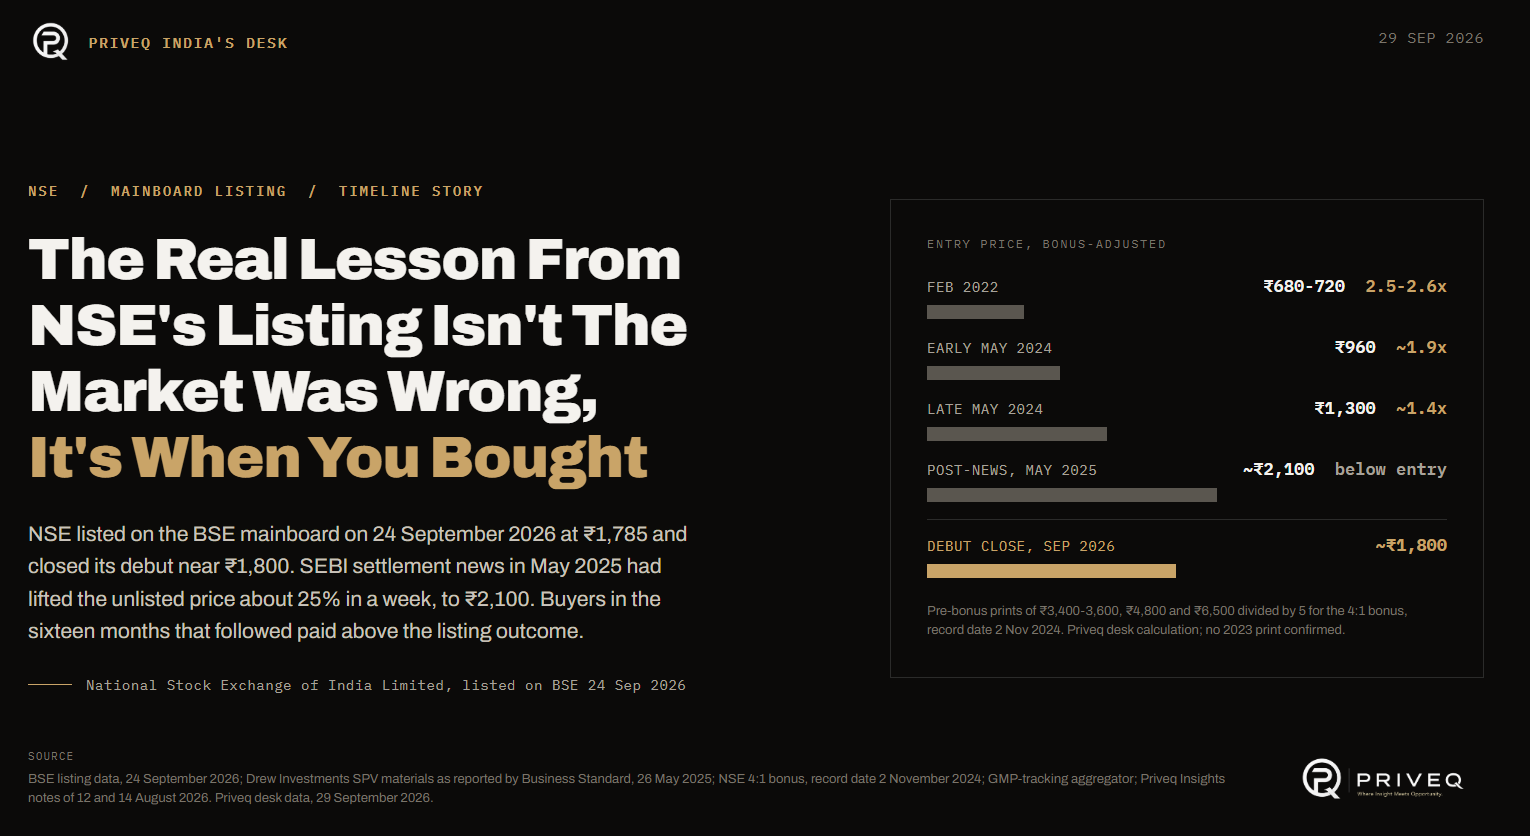
National Stock Exchange of India Limited listed on the BSE mainboard on September 24, 2026, at an issue price of Rs. 1,785 per share, closing its debut session at roughly Rs. 1,800. That closing price sits almost exactly where NSE's unlisted shares traded before May 2025, when SEBI settlement news sent the price up nearly 25% in a week and kept it elevated for the next sixteen months. The pattern holds further back too: adjusted for NSE's 4:1 bonus issue in November 2024, the stock traded near Rs. 680-960 through 2022 and into mid-2024, meaning anyone who held through the full cycle still made a strong return. The overpaying happened specifically in the sixteen months after the SEBI news broke, not before it, and not across the unlisted market's longer history.
Event : Mainboard Listing (Offer for Sale) Date : September 24, 2026 Source : BSE listing data; exchange bidding disclosures as reported across financial media Primary Metric Affected : Issue price Rs. 1,785/share; debut close approximately Rs. 1,800/share
What Actually Happened At Listing
NSE listed on the BSE mainboard on September 24, 2026, after a price band of Rs. 1,700 to Rs. 1,785 and an issue price fixed at the top of that band, Rs. 1,785. The debut session closed at roughly Rs. 1,800, a modest premium of under 1% over the issue price. The offering was structured entirely as an offer for sale of up to 12.64 crore equity shares (a total issue size of Rs. 22,561.57 crore), existing shareholders including SBI, Temasek, and CPPIB sold shares, and NSE itself raised no fresh capital. At the issue price, NSE was valued at roughly 43 times FY26 earnings, against listed peer BSE's trailing valuation of about 47 times earnings.
Subscription across investor categories, as reported across financial media compiling exchange bidding data, ran to roughly 5.7x overall: QIBs at 12.68x, non-institutional investors at 6.54x, retail at 1.37x, and the employee portion at 2.38x. We have not independently sourced these figures to a BSE or NSE circular, they are treated here as widely and consistently reported, not filed.
NSE Listing Day At A Glance
Metric | Figure |
|---|---|
Price Band | Rs. 1,700 - Rs. 1,785 |
Issue Price | Rs. 1,785 |
Listing Date | September 24, 2026 (BSE) |
Debut Close (approx.) | Rs. 1,800 |
Structure | Offer for Sale only (SBI, Temasek, CPPIB and other existing shareholders); no fresh capital raised |
OFS Size | 12.64 crore equity shares; Rs. 22,561.57 crore total issue size |
Implied Market Cap At Listing | ~Rs. 4.5 lakh crore (~$47 billion) |
P/E At Issue Price (FY26 earnings) | ~43x (vs. BSE's ~47x trailing) |
Overall Subscription | ~5.7x (QIB 12.68x | NII 6.54x | Retail 1.37x | Employee 2.38x) |
Subscription figures are as reported across financial media compiling exchange bidding data, not independently sourced to a BSE/NSE circular in this piece.
The Two Timelines: Before And After May 2025
The story of NSE's unlisted price splits cleanly into two periods, and conflating them is exactly what produced this week's criticism of the unlisted market.
Before mid-May 2025, NSE's unlisted shares traded around Rs. 1,550 to Rs. 1,700, per Drew Investments' own marketing materials for a special-purpose vehicle raising money to invest in NSE at that range, reported by Business Standard on May 26, 2025. Then, within a single week, the price jumped by Rs. 400 to Rs. 420, to around Rs. 2,100, a roughly 25% move, on news that NSE had offered to settle its long-running SEBI co-location case (an initial offer in the region of $118 million, later finalized at a reported Rs. 1,388 crore by June 2025). The same reporting cited NSE's implied private-market valuation rising from $36 billion in September 2024 to $50 billion by the time of the settlement news.
That single week reset the baseline. For roughly the next sixteen months, as the settlement was finalized, SEBI granted its in-principle no-objection certificate on January 30, 2026, and NSE formally filed its DRHP on June 17, 2026, the unlisted price held broadly in the Rs. 1,800 to Rs. 2,100 band you'd see quoted across secondary platforms through 2026. NSE's own actual listing closed at approximately Rs. 1,800, almost exactly where the pre-news price sat in early May 2025, and meaningfully below the post-news band that held for most of the following year.
Period | NSE Unlisted Price | What Changed |
|---|---|---|
Before mid-May 2025 | Rs. 1,550 - 1,700 | Baseline, years of gradual appreciation |
Within one week, by May 26, 2025 | ~Rs. 2,100 (+Rs. 400-420, ~25%) | SEBI co-location settlement news breaks |
May 2025 through September 2026 (~16 months) | Rs. 1,800 - 2,100 | Settlement finalized, SEBI NOC (Jan 2026), DRHP filed (June 2026) |
Listing, September 24, 2026 | Rs. 1,785 issue / ~Rs. 1,800 close | Actual outcome |
Pre- and post-news prices sourced to Drew Investments' own SPV marketing materials for NSE, as reported by Business Standard, May 26, 2025.
The read here is specific, not a broad indictment. Anyone who bought NSE's unlisted shares in the sixteen months after the SEBI news broke, chasing a story that was already public and already priced in, paid a premium that the actual listing did not reward within that window. Anyone who held from before that news, or who bought during the brief post-news spike and simply waited it out, ended up close to fair.
What Bonus-Adjusted History Shows : 2022 Through Mid-2024
NSE issued a 4:1 bonus (four new shares for every one held, a fivefold increase in share count), with a record date of November 2, 2024. Comparing older unlisted prices to today's without adjusting for that split is the single most common way an "it used to be cheap" recollection turns out to be wrong, or, in this case, wrong in the opposite direction: the older, pre-bonus prices actually convert to lower current-equivalent figures than casual memory tends to place them at.
Business Standard reported NSE's unlisted price around Rs. 3,400 to Rs. 3,600 in February 2022. A separate report placed it around Rs. 4,800 in early May 2024, rising roughly 35% to about Rs. 6,500 later that month on the bonus announcement itself. Adjusted for the later 4:1 bonus (dividing by five), those figures work out to roughly Rs. 680 to Rs. 720 in 2022, and Rs. 960 to Rs. 1,300 in May 2024.
Period | Pre-Bonus Price | Bonus-Adjusted Equivalent (÷5) |
|---|---|---|
February 2022 | Rs. 3,400 - 3,600 | Rs. 680 - 720 |
Early May 2024 | Rs. 4,800 | Rs. 960 |
Late May 2024 (post bonus-announcement jump) | Rs. 6,500 | Rs. 1,300 |
At listing (for comparison) | Rs. 1,785 issue / ~Rs. 1,800 close | Rs. 1,785 / Rs. 1,800 |
NSE's 4:1 bonus issue (four new shares per one held) had a record date of November 2, 2024, increasing share count fivefold. Pre-bonus prices divided by 5 to make them comparable to today's price. Implied multiple to listing close: ~2.5x-2.6x from the 2022 range, ~1.4x-1.9x from the May 2024 range.
On this basis, someone who bought NSE unlisted shares in 2022 and held to listing saw the equivalent of a roughly 2.5x to 2.6x return. Someone who bought in early-to-mid 2024, before the bonus announcement itself pushed the price up, still saw a return of roughly 1.4x to 1.9x. Both are genuinely strong outcomes for a multi-year unlisted holding. The criticism aimed at the unlisted market this week, that it "overpriced" NSE, describes the sixteen months after May 2025 specifically. It does not describe the unlisted market's longer track record on this name, which held up well.
The IPO Grey Market's Own Reversal
Separate from the years-long unlisted secondary market covered above, NSE's IPO also had its own, much shorter-lived grey market premium (GMP), the informal premium quoted specifically during the IPO application window. This is a different instrument from the unlisted secondary share price, and the two shouldn't be conflated, but it tells a compatible story.
GMP peaked at Rs. 310 over the issue price around September 4-5, 2026, implying a price near Rs. 2,095, a 17.4% premium over the Rs. 1,785 issue price. From there it fell steadily through the subscription window, and by the morning of listing, September 24, 2026, it had collapsed to just Rs. 40, implying a price near Rs. 1,825, close to where the stock actually opened.
GMP Window | Implied Premium Over Issue Price | Implied Price |
|---|---|---|
Peak, Sept 4-5, 2026 | Rs. 310 (17.4%) | ~Rs. 2,095 |
Sept 6-10, 2026 | Declining, ~Rs. 192 | ~Rs. 1,977 |
Sept 15-18, 2026 | ~Rs. 111 - 160 | ~Rs. 1,896 - 1,945 |
Morning of listing, Sept 24, 2026 | Rs. 40 | ~Rs. 1,825 |
GMP is a separate, shorter-lived instrument from the years-long unlisted secondary market above, specific to the IPO application window. Sourced to a GMP-tracking aggregator, not an exchange-published figure.
The GMP source here is a grey-market-tracking aggregator, not an exchange-published figure, and is treated accordingly in the stand-behind section below. But the shape of the move, a fast, self-correcting decline in the three weeks before listing, matches the broader pattern: pre-listing enthusiasm ran ahead of the eventual price, and the market itself corrected most of that gap before the stock ever opened.
Priveq's Desk Price, Checked Against The Outcome
Priveq's desk price is not an independent valuation call, it tracks where the unlisted market is actually trading, the same underlying activity behind the broader Rs. 1,800-2,100 range covered above, not a separately derived figure. Priveq's August 12, 2026 note reported that market-driven price at Rs. 2,000 following Q1 FY27 results and left it unchanged, a decision the piece was explicit about: "This is a clean quarter, not a re-rating event," stated alongside caveats that the quarter's profit growth came from expense discipline and other income rather than revenue (which fell 8.2% QoQ), and that the piece's own forward P/E of roughly 39.7x was "a flat run-rate assumption, not a guidance figure NSE has given." The price held at Rs. 2,000 because nothing in the quarter's disclosures moved the market, not because Rs. 2,000 was being called a comfortable or fair price.
That market-driven price then moved. A separate Priveq piece, published August 14, 2026, on SBI Capital Markets joining NSE's IPO as a co-seller, records it at Rs. 1,970, already Rs. 30 lower than two days earlier. By the time NSE's Marketplace page was last checked before this piece went to press (September 29, 2026), it stood at Rs. 1,940. Against the actual issue price of Rs. 1,785 and debut close near Rs. 1,800, the price Priveq's desk was reporting had already drifted roughly 8-9% closer to the eventual outcome in the weeks before listing.
Date | Price On Priveq's Desk | Gap To Issue Price (Rs. 1,785) |
|---|---|---|
August 12, 2026 | Rs. 2,000 | +12.0% |
August 14, 2026 | Rs. 1,970 | +10.4% |
September 29, 2026 (last checked) | Rs. 1,940 | +8.7% |
Listing, September 24, 2026 | Rs. 1,785 issue / ~Rs. 1,800 close | Actual outcome |
This price tracks actual unlisted market activity, not an independent Priveq valuation call. It is not a continuous daily series, only the checkpoints available across two prior Priveq Insights pieces and the Marketplace page. We don't have a continuous, day-by-day record of every update between these three checkpoints, so this shows the trend, not a complete series. The point isn't that Priveq called the price better than others, it's that the same unlisted market activity Priveq's desk was reflecting had already started correcting toward the eventual outcome well before listing, distinct from the more static, aggregator-quoted Rs. 1,950-2,100 range that doesn't appear to have moved as quickly.
The Desk View
The unlisted market's multi-year price discovery on NSE held up. Bonus-adjusted, anyone who held from 2022 or even from early-to-mid 2024 through to listing made a genuinely strong return, roughly 1.4x to 2.6x depending on entry point.
The window that overpaid was specific: the sixteen months after May 2025. SEBI settlement news moved the price up nearly 25% in a week, and the market held that elevated pricing through the DRHP filing and up to listing, ending close to where it started before the news broke.
The market-driven price Priveq's desk was reporting had already narrowed toward the outcome before listing, moving from Rs. 2,000 (Aug 12) to Rs. 1,970 (Aug 14) to Rs. 1,940 (late September), reflecting actual unlisted market activity, not an independent Priveq valuation call.
The closing read: NSE's debut vindicates the unlisted market's long-run price discovery. It does not vindicate buying into a story after the news that made it exciting has already broken, that's a timing problem, not evidence the unlisted market itself is broken.
FAQs
Did NSE's unlisted share price accurately predict its Rs. 1,785 IPO price?
It depends on which period you look at. The unlisted price before May 2025 (Rs. 1,550-1,700) was a close predictor of the actual outcome, while the price that held for the sixteen months after May 2025's SEBI settlement news (Rs. 1,800-2,100) ran ahead of it.
Is NSE's roughly Rs. 1,800 closing price its final settled value?
No, that's only the first trading day's close, and a single session doesn't establish a stock's longer-term trading range. NSE will continue trading on the BSE going forward, and its price will move like any newly listed stock's.
Is the exact 2022-2023 unlisted price for NSE independently confirmed?
Not precisely for that specific window. We confirmed a Rs. 3,400-3,600 print for February 2022 and a Rs. 4,800-6,500 range for May 2024, both pre-bonus, but we could not independently source a dedicated 2023 print, so the 2022-to-2024 trend is drawn from the two confirmed endpoints, not a continuous series.
What is a bonus share issue, and why does it matter for comparing NSE's old and new unlisted prices?
A bonus issue gives existing shareholders additional free shares, which mechanically lowers the per-share price without changing what any shareholder's total holding is worth. NSE's 4:1 bonus (record date November 2, 2024) increased its share count fivefold, so any pre-November 2024 price has to be divided by five before comparing it to today's price, otherwise the comparison is simply wrong.
Should I be concerned that I overpaid for NSE unlisted shares last year?
That depends on when in the last year you bought. If it was in the weeks or months after May 2025's SEBI settlement news, at prices in the Rs. 1,900-2,100 range, the listing came in below that. If it was before that news broke, or you've held for several years, the bonus-adjusted math above suggests the position has likely still worked out well.
What We Can And Cannot Stand Behind
Primary-sourced and verified:
NSE's Rs. 1,785 issue price and Rs. 1,700-1,785 price band, and its September 24, 2026 BSE listing date (widely reported, consistent across independent outlets)
The offer-for-sale size: 12.64 crore equity shares, a total issue size of Rs. 22,561.57 crore (Groww, consistent with the 126,436,650-share figure reported elsewhere)
NSE's 4:1 bonus share issue, record date November 2, 2024 (Business Standard, Moneylife, ICICI Direct, Upstox, mutually corroborating)
SEBI's in-principle no-objection certificate for NSE's IPO documents, granted January 30, 2026 (Business Standard)
NSE's DRHP filing date of June 17, 2026 (Priveq's own Marketplace research)
The market-driven price reported on Priveq's desk, Rs. 2,000 as of August 12, 2026 (held unchanged that day, not an independent fair-value call) and Rs. 1,970 as of August 14, 2026, and its stated Q1 FY27 figures including the 8.2% QoQ decline in revenue from operations (Priveq Insights, prior published pieces)
NSE's implied valuation at listing of roughly Rs. 4.5 lakh crore (~$47 billion) and its issue-price P/E of roughly 43x FY26 earnings, against BSE's 47x trailing (Reuters-sourced reporting)
Partially or indirectly corroborated:
Debut closing price of approximately Rs. 1,800, our reference point; two independent outlets report Rs. 1,817-1,818, a minor variance not material to the analysis in this piece
The pre-May-2025 unlisted price (Rs. 1,550-1,700) and the post-news jump to Rs. 2,100, sourced to Drew Investments' own SPV marketing materials as reported by Business Standard, company-disclosed-adjacent but not an audited or exchange-filed figure
The 2022 (Rs. 3,400-3,600) and May 2024 (Rs. 4,800-6,500) pre-bonus prices, both bonus-adjusted by Priveq's own calculation rather than published directly in post-bonus terms at the time
The IPO grey market premium trajectory (peak Rs. 310, closing Rs. 40), sourced to a GMP-tracking aggregator rather than an exchange-published data point
Subscription figures by investor category (5.7x overall, QIB 12.68x, and so on), as reported across financial media compiling exchange bidding data, not sourced directly to a BSE or NSE circular
Could not be confirmed:
The exact evolution of NSE's SEBI settlement amount: an initial offer reported around $118 million in May 2025 against a Rs. 1,388 crore figure reported as the finalized settlement in June 2025, we could not independently confirm these refer to the same negotiation or reconcile the two figures
A continuous, dated 2023 unlisted price print for NSE
Disclaimer
This note is for informational purposes only and does not constitute investment advice. Priveq Investech Private Limited is not a registered investment advisor. Prices, multiples, and figures cited are sourced and dated as stated throughout this piece and may have moved since publication. Readers should conduct their own due diligence or consult a licensed advisor before making investment decisions.