

The Short Version
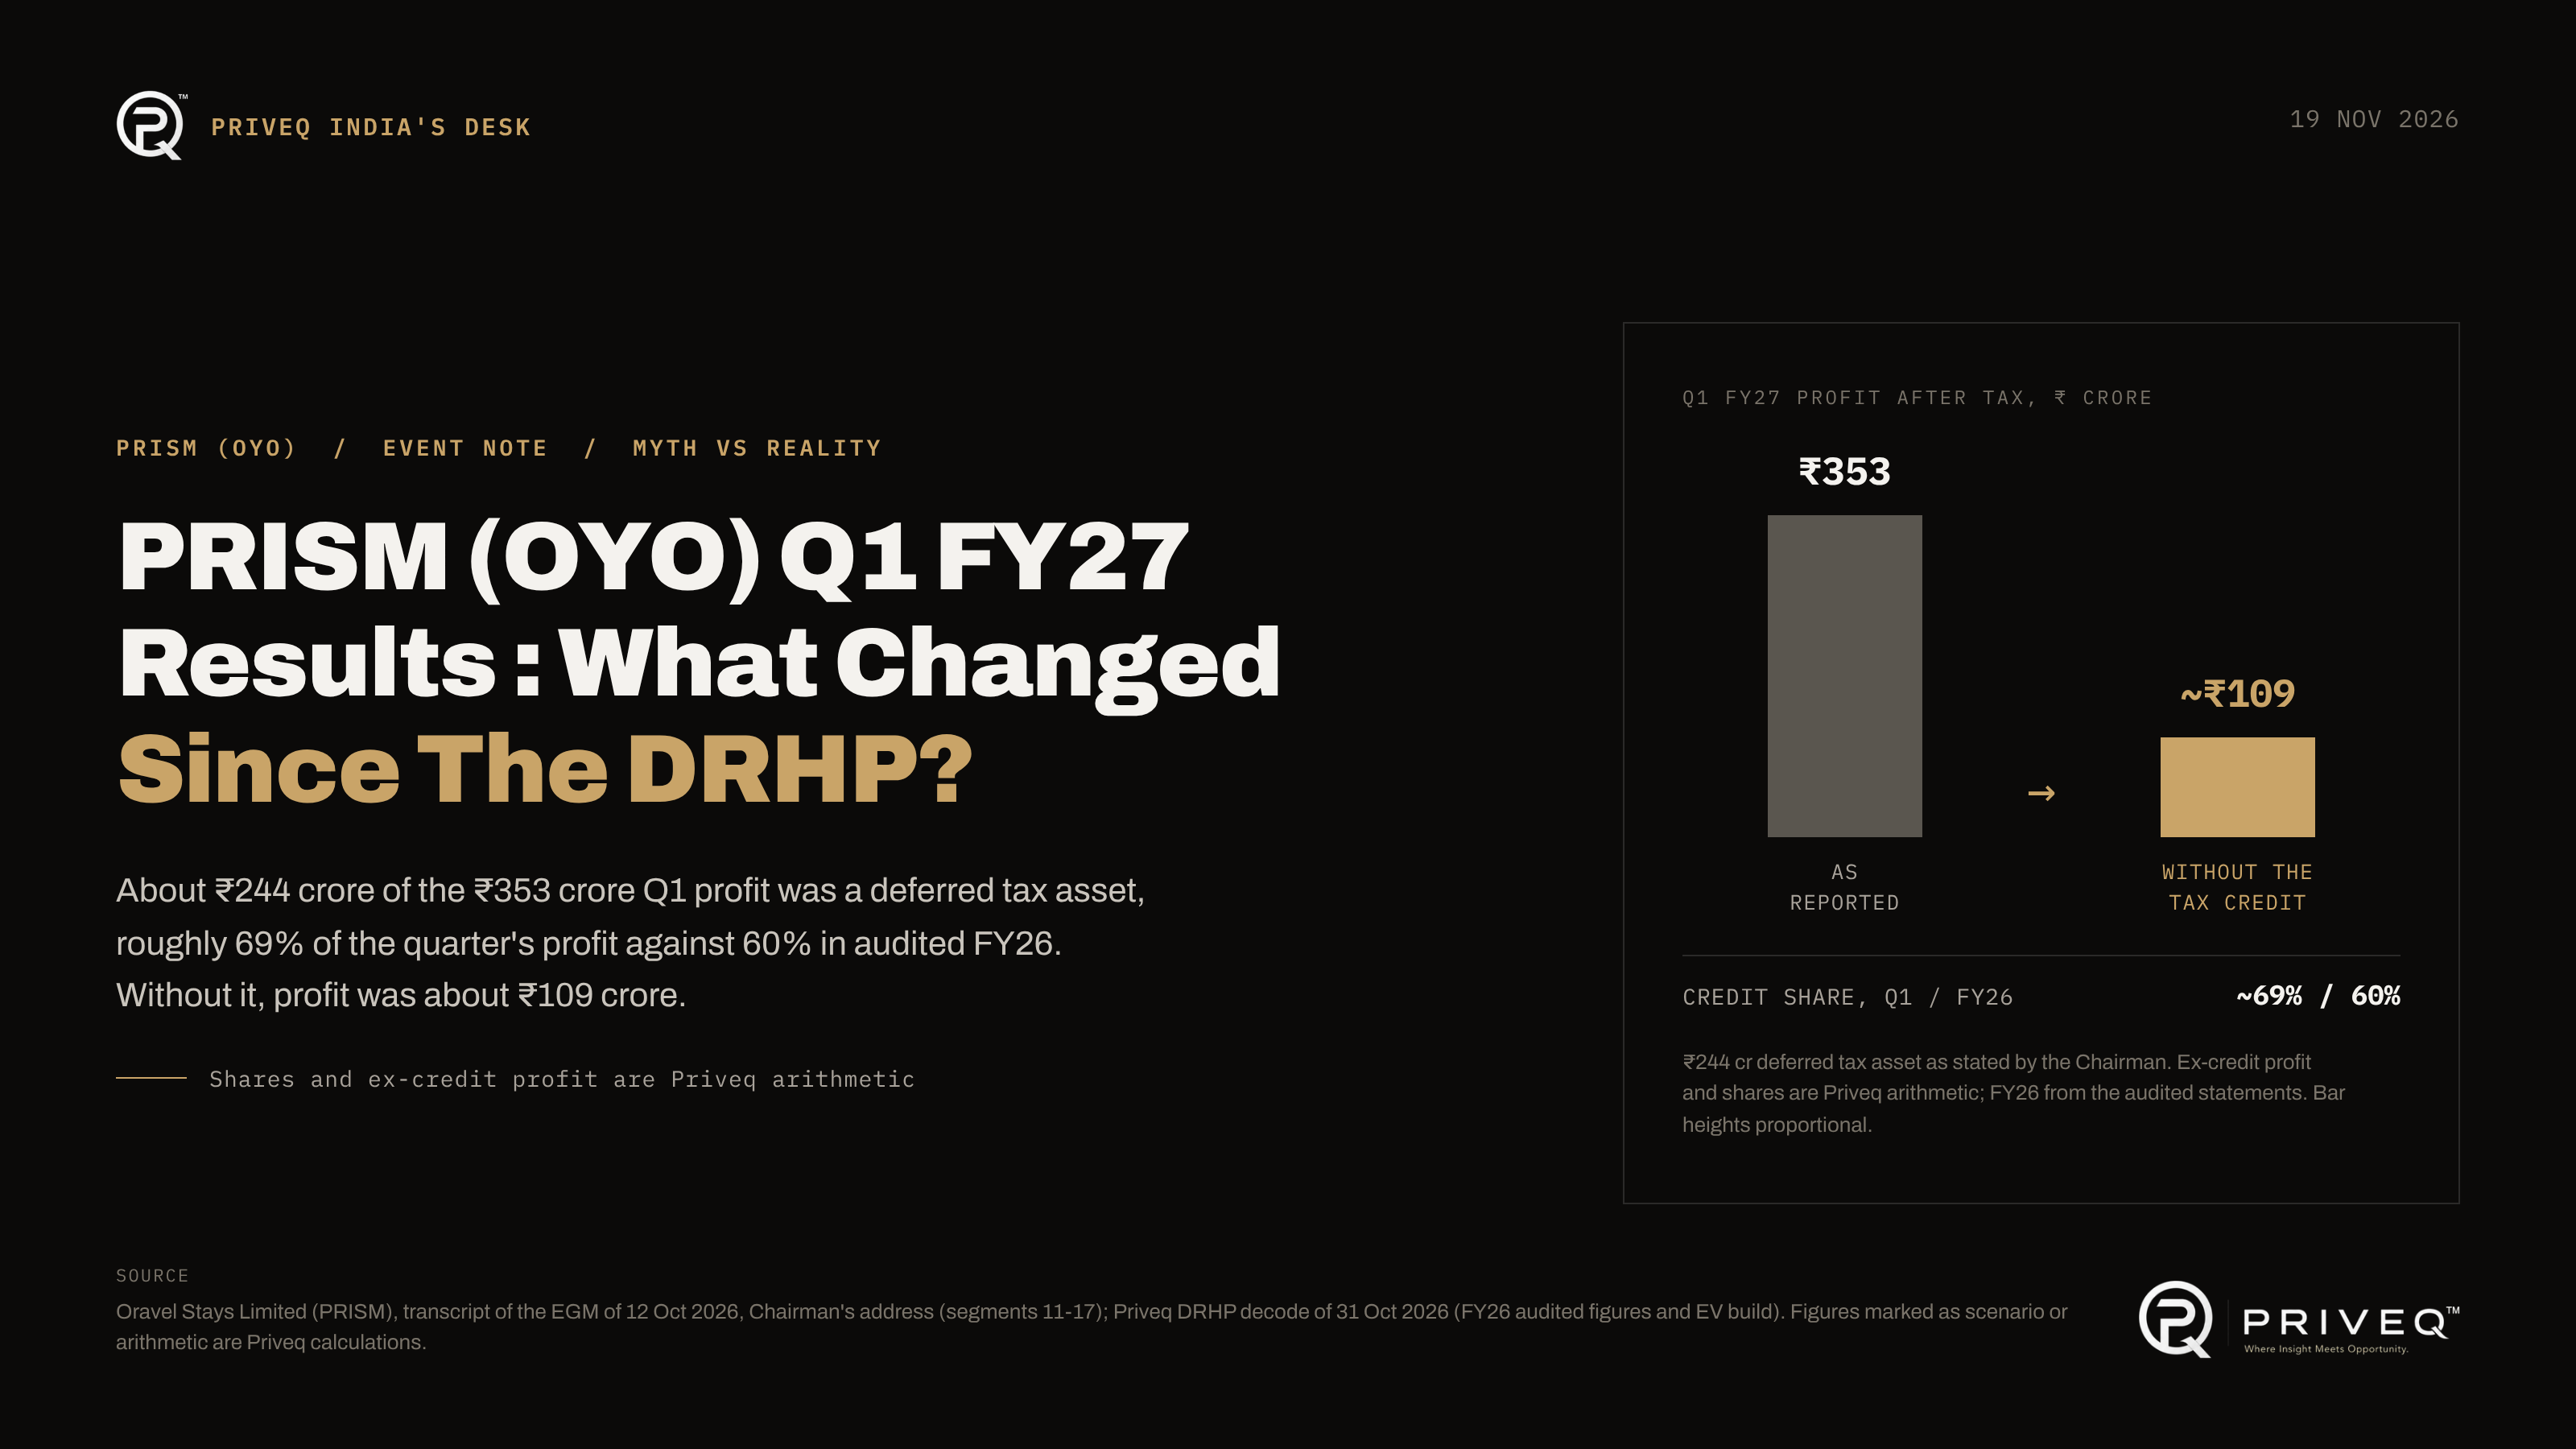
PRISM's chairman told shareholders at the 12 October 2026 EGM that Q1 FY27 (April to June 2026) consolidated profit after tax rose 17% to Rs 353 crore, and that it included a deferred tax asset of about Rs 244 crore. Without that credit the quarter's profit is about Rs 109 crore, so roughly 69% of the headline came from tax, a larger share than the 60% in audited FY26, which our DRHP decode flagged as the main profit-quality question. The operating lines are cleaner: revenue up 35% to about Rs 2,814 crore, bookings up 30% to about Rs 9,600 crore, and adjusted EBITDA net of lease expenses up 35% to Rs 589 crore.
Event: Q1 FY27 results, disclosed in the Chairman's address at the EGM of 12 October 2026; the same meeting raised the authorised equity ceiling from 17.6 billion to 50 billion shares
Date: 12 October 2026 (EGM); press reports of the audited quarterly statements followed on 2 November 2026
Source: Company-published EGM notice and EGM transcript; Annual Report FY2024-25 for the Q1 FY26 base as first stated
Primary Metric Affected: Profit quality (tax credit share of profit) and the trailing EBITDA behind the EV/EBITDA lens
This is a follow-up to our 31 October 2026 piece, PRISM (OYO) IPO DRHP Decode: Issue, Share Count and Valuation. It does not repeat the decode's issue structure, debt, peer or risk analysis; it adds what Q1 FY27 changes. For the company profile, financials and the live desk price, see PRISM (OYO) on the Priveq Marketplace.
What Has Moved Since the Decode?
The decode used audited FY26 numbers and a desk price of Rs 20.50 as of 29 October 2026. It did not cover the 12 October EGM, where the company both reported its first-quarter numbers and asked shareholders to lift its authorised share capital. Here is what has moved.
What has moved since the DRHP decode of 31 October 2026
Item | In the decode | Now | Source |
|---|---|---|---|
Priveq desk price | Rs 20.50 (29 October 2026) | Rs 22.25 (19 November 2026), up 8.5% | Priveq desk |
Latest results | Audited FY26 (year to 31 March 2026) | Q1 FY27 (April to June 2026), stated by the Chairman at the 12 October 2026 EGM | EGM transcript |
Q1 FY27 audited statements | Not covered | Reported by the press on 2 November 2026; not published by the company | Press reports |
Authorised equity shares | Not covered | Raised from 17.6 billion to 50 billion shares of Rs 1; 99.9999% of votes in favour; Form SH-7 filed 16 October 2026 | EGM notice, item 1; scrutiniser's report extract filed with SH-7 |
Equity shares issued | 3,745,994,357 (UDRHP-I) | 3,753,332,300 (19 September 2026) | EGM notice |
Preference shares outstanding | 662,589,611 (UDRHP-I) | 662,512,261 (19 September 2026) | EGM notice (sum of series) |
Paid-up capital | Rs 1,037.77 crore (19 September 2026) | Rs 1,040.17 crore in MCA company master data, last refreshed about 27 October 2026 | EGM notice; MCA master data |
Fresh issue | Up to Rs 3,350 crore (addendum, 21 October 2026) | Unchanged; no price band | Addendum to UDRHP-I |
Red herring prospectus | Not filed | Not on the company's IPO page as at 19 November 2026 | prismlife.com IPO kit |
Source: Priveq desk; Oravel Stays Limited, notice of EGM dated 19 September 2026, transcript of the EGM of 12 October 2026, and Form SH-7 with clarification and scrutiniser's report extract filed with the Registrar on 16 October 2026; MCA company master data; Addendum to UDRHP-I, 21 October 2026; prismlife.com IPO kit page, checked 19 November 2026. Percentage change is Priveq arithmetic.
Net read: two things matter for a buyer. The profit line now has a quarter attached, and the desk price has risen 8.5% in three weeks without any new document from the IPO process itself; the issue size and the missing price band are where the decode left them.
What Did PRISM Say About Q1 FY27?
Ritesh Agarwal gave the Q1 FY27 numbers in his opening address, before the single resolution was taken up (EGM transcript, segments 11 to 17). The transcript the company published is an automatic speech-to-text record, so the figures are as spoken, several with "approximately".
PRISM Q1 FY27 against Q1 FY26, as stated by the Chairman at the EGM (Rs crore)
Metric | Q1 FY27 | Q1 FY26 | Growth stated |
|---|---|---|---|
Revenue from operations | about 2,814 | about 2,000 | 35% |
Bookings (gross booking value) | about 9,600 | 7,408 | 30% (34% excluding G6, as stated) |
Gross margin | about 1,785 | not stated | 39% |
EBITDA | 741 | 603 | 23% |
Adjusted EBITDA net of lease expenses | 589 | 435 | 35% |
Consolidated profit after tax | 353 | 301 | 17% |
Of which deferred tax asset recognised | about 244 | not stated | not stated |
Hotel bookings / vacation home bookings | not stated | not stated | about 30% / 28% |
Source: Oravel Stays Limited, transcript of the EGM of 12 October 2026, Chairman's address, segments 11 to 16 (company-published, auto-transcribed speech). Company statement, not audited statements. 'About' follows the speaker's own wording.
Three points in the address are worth stating exactly:
Bookings growth was broad. Hotel bookings grew about 30% and vacation home bookings 28%. Excluding G6, the US economy-hotel business acquired in FY25, bookings grew 34%, by the Chairman's account (segments 12, 13 and 16).
G6 is now a large share of the platform. In FY26, G6 alone brought about Rs 14,000 crore of bookings, against total FY26 bookings of Rs 30,683 crore in the audited accounts (segment 17).
The profit line carries a tax credit. The Chairman said the Rs 353 crore "included a DTA of approximately 244 crore", and added that earnings beyond it were still substantial (segment 15).
Revenue grew faster than EBITDA: 35% against 23%. On the after-lease line the two moved together, both at 35%. By our arithmetic, after-lease EBITDA was 20.9% of revenue in Q1 FY27, close to the 20.6% in FY26.
Net read: on the operating lines, Q1 FY27 continues FY26 rather than accelerating it. The quarter's headline profit growth, 17%, is the weakest of the growth rates the Chairman gave, and it is also the line most affected by tax.
How Much of the Q1 Profit Is a Tax Credit?
A deferred tax asset is recognised when a company expects to use past tax losses or other deductions against future taxable profit. Booking it lowers the tax charge in the period and lifts profit after tax, but no cash comes in. PRISM carries large accumulated losses from earlier years, and the decode showed that FY26 profit after tax of Rs 994.2 crore included a net tax credit of Rs 595.3 crore.
Profit quality: how much of PRISM's profit after tax came from tax credits (Rs crore)
Line | FY26 (audited) | Q1 FY27 (stated) | Q1 FY26 (stated) |
|---|---|---|---|
Profit after tax | 994.2 | 353 | 301 |
Tax credit inside it | 595.3 (net tax credit) | about 244 (deferred tax asset) | not stated |
Profit after tax without the credit | 398.9 | about 109 | not known |
Credit as a share of profit after tax | 60% | about 69% | not known |
Source: FY26 from the audited consolidated statements in the Annual Report FY2025-26, as set out in the decode; Q1 figures from the EGM transcript of 12 October 2026, segments 14 and 15. 'Without the credit' and both percentages are Priveq arithmetic. FY26 profit before tax of Rs 398.9 crore includes a non-cash gain of about Rs 130 crore.
The Q1 share is higher than the full year's. Of Rs 353 crore, about Rs 244 crore is the deferred tax asset, which leaves about Rs 109 crore. What the Chairman did not say is whether the Q1 FY26 profit of Rs 301 crore also carried a credit, so the 17% growth may or may not compare like with like.
Net read: PRISM's profit after tax is still mostly a tax-accounting line, and that is the reason the decode used EV/EBITDA rather than P/E. Q1 does not change that; it strengthens it.
The Q1 FY26 Base Moved Too
A year ago, the Chairman's letter in the FY25 annual report gave early Q1 FY26 numbers "as per the provisional quarterly accounts": revenue of Rs 2,019 crore, EBITDA of Rs 550 crore and profit after tax of "over INR 200 crore (expected to be higher)" (Annual Report FY2024-25, Chairman's letter, PDF p. 5). At the October 2026 EGM, the same quarter was the base for this year's growth rates, and the profit figure was Rs 301 crore.
The Q1 FY26 comparative, as first flagged and as used now (Rs crore)
Q1 FY26 metric | FY25 annual report (provisional) | EGM, 12 October 2026 | Change |
|---|---|---|---|
Revenue from operations | 2,019 | about 2,000 (the stated 35% growth implies about 2,084) | Within rounding |
EBITDA | 550 | 603 | +9.6% |
Profit after tax | over 200 ('expected to be higher') | 301 | About +50% on the Rs 200 crore floor |
Source: Annual Report FY2024-25, Chairman's letter, PDF p. 5 ('as per the provisional quarterly accounts'); EGM transcript of 12 October 2026, segments 11, 13 and 14. The implied revenue and both changes are Priveq arithmetic; the two EBITDA figures may not use the same definition.
The FY25 letter did warn that profit was expected to be higher, so a revision upward is not in itself a red flag. But it does mean the 17% profit growth sits on a base about 50% above the floor the company first gave, and the 23% EBITDA growth on a base about 10% higher. The EBITDA definitions may also differ between the two documents, which neither states.
Net read: when growth rates are quoted for an unlisted company with no quarterly filing, the base deserves the same check as the current number. Here, the base rose after the fact.
What Q1 Does to the EV/EBITDA Lens
The decode valued PRISM on enterprise value to EBITDA, using audited FY26 adjusted EBITDA of Rs 2,629 crore, net borrowings of Rs 6,775 crore and the 15.05 billion-share headline base. Rolling Q1 in gives a trailing figure to June 2026: FY26 plus Q1 FY27 less Q1 FY26. We do this on the after-lease line, because both quarters' after-lease figures (Rs 589 crore and Rs 435 crore) were stated in the same breath and it is the lens that treats PRISM's leased hotels as an operating cost.
The decode's EV lens at Rs 20.50 (29 October 2026) and at Rs 22.25 (19 November 2026), with Q1 FY27 rolled in
Lens | At Rs 20.50 (29 October 2026) | At Rs 22.25 (19 November 2026) |
|---|---|---|
Market value, 15.05 billion shares (Rs crore) | 30,860 | 33,495 |
Net borrowings, 31 March 2026 (Rs crore) | 6,775 | 6,775 |
Enterprise value (Rs crore) | 37,636 | 40,270 |
EV / FY26 adjusted EBITDA (Rs 2,629 crore) | 14.3x | 15.3x |
EV / FY26 EBITDA after lease costs (Rs 1,928 crore) | 19.5x | 20.9x |
EV / trailing EBITDA after lease costs to June 2026 (Rs 2,082 crore) | 18.1x | 19.3x |
EV / FY26 gross booking value (Rs 30,683 crore) | 1.23x | 1.31x |
EV / trailing gross booking value to June 2026 (Rs 32,875 crore) | 1.14x | 1.22x |
Source: Rs 20.50 column from the decode's EV build; Rs 22.25 (19 November 2026) column is Priveq arithmetic on the same share base and net borrowings. Trailing figures are FY26 plus Q1 FY27 less Q1 FY26, using the Chairman's stated after-lease EBITDA (589 and 435) and bookings (9,600 and 7,408), and assume the same definitions as the audited FY26 lines. No Q1 balance sheet is public, so net borrowings stay at 31 March 2026.
By our arithmetic, trailing after-lease EBITDA to June 2026 is Rs 2,082 crore, 8.0% above FY26. The desk price rose 8.5% over the same comparison, from Rs 20.50 (29 October 2026) to Rs 22.25 (19 November 2026). So on a trailing basis the multiple barely moved: 19.3 times at Rs 22.25 against 19.5 times on FY26 in the decode. On the FY26 lines alone, the higher price lifts EV/EBITDA from 14.3 to 15.3 times.
Two cautions. Net borrowings stay at 31 March 2026, because no Q1 balance sheet is public; if part of the Rs 7,757 crore Term Loan B was repaid from cash, EV would be lower. And the trailing figures assume the Chairman's after-lease line uses the same definition as the audited FY26 line.
Net read: the price rise since the decode is roughly matched by one quarter of after-lease EBITDA growth. That is a statement about the multiple, not about value; the decode's point that the reported US$7 to 8 billion target needs a much higher multiple or much higher EBITDA still stands.
The Share Ceiling and the Share Count
The only resolution at the 12 October EGM raised PRISM's authorised equity capital from 17.6 billion to 50 billion equity shares of Rs 1, leaving the preference share classes unchanged; total authorised capital rose from Rs 2,491.14 crore to Rs 5,731.14 crore (EGM notice, item 1 and explanatory statement). It passed with 99.9999% of votes cast in favour, and the company filed Form SH-7 with the Registrar on 16 October 2026 (Form SH-7 clarification with the scrutiniser's report extract). The stated reason is "adequate headroom for the Company's future capital requirements" and "various potential capital transactions". Asked by a shareholder, the Chairman said the ceiling is only a ceiling and no shares are being issued or allotted now (EGM transcript, segment 51).
PRISM share count and the authorised-capital ceiling, before and after the 12 October 2026 EGM
Line | Shares (unless stated) | Basis |
|---|---|---|
Equity shares issued, 19 September 2026 | 3,753,332,300 | EGM notice, explanatory statement |
Preference shares outstanding, 19 September 2026 | 662,512,261 | Sum of Series A to G in the notice |
Paid-up capital, 19 September 2026 (Rs crore) | 1,037.77 | Equity and Series A at Rs 1 each, other series at Rs 10 each; ties to the notice |
Headline base after conversion | 15,053,791,264 | Decode, Table 4 |
Cautious base (headline plus all options) | 15,932,035,660 | Decode, Table 4 |
Authorised equity ceiling before the EGM | 17,600,000,000 | EGM notice |
Authorised equity ceiling after the EGM | 50,000,000,000 | EGM notice, item 1 |
Old ceiling less cautious base | 1,667,964,340 | Priveq arithmetic |
Shares for a Rs 3,350 crore fresh issue at Rs 22.25 (illustration only) | 1,505,617,978 | Priveq arithmetic; no price band is set |
Source: Oravel Stays Limited, notice of EGM dated 19 September 2026, item 1 and explanatory statement; share bases from the DRHP decode of 31 October 2026; fresh issue size from the Addendum to UDRHP-I, 21 October 2026. The Rs 22.25 is the Priveq desk price as of 19 November 2026, used only to size the illustration.
The arithmetic shows why the old ceiling was tight. After every preference share converts and every option is exercised, PRISM would have 15.93 billion equity shares, leaving 1.67 billion under the old 17.6 billion ceiling. A Rs 3,350 crore fresh issue needs 1.51 billion shares at Rs 22.25, the desk price as of 19 November 2026, and the old ceiling would run out at any issue price below about Rs 20.08. This is our arithmetic, not a company statement, and no price band has been set.
The notice also updates the share count. On 19 September 2026, PRISM had 3,753,332,300 equity shares and 662,512,261 preference shares, against 3,745,994,357 and 662,589,611 in the UDRHP-I: 7,337,943 more equity shares and 77,350 fewer preference shares. The notice does not say why. If preference shares converted, the 15.05 billion headline base is unchanged; if the new equity came from option exercises or another allotment, the base rises by about 0.05%. Equity plus preference shares ties exactly to the paid-up capital of Rs 1,037.77 crore stated in the notice. The Registrar's company master data, last refreshed around 27 October 2026, shows paid-up capital of Rs 1,040.17 crore, Rs 2.40 crore higher, so the share count moved again after 19 September. No allotment return for 2026 appears in the documents filed up to 27 October, so we cannot yet say whether this was a new allotment or a conversion of preference shares.
Net read: the ceiling increase is housekeeping for the IPO rather than a new issue, on the company's own account. For per-share maths, the decode's 15.05 billion and 15.93 billion bases still hold.
What Do the Q1 Numbers Not Settle?
The audited quarterly statements. Press reports on 2 November 2026 cited audited Q1 FY27 statements that the company has not published. They give EBITDA of Rs 760 crore against Rs 611 crore, and Q1 FY26 revenue of Rs 2,078 crore, where the Chairman said Rs 741 crore, Rs 603 crore and about Rs 2,000 crore. The likely cause is a definition or rounding difference, but neither document says so.
Whether Q1 FY26 profit carried a tax credit, which decides whether the 17% growth is like for like.
Net debt at 30 June 2026. No Q1 balance sheet is public.
Q1 profit before tax. Not stated, so the operating profit behind the Rs 109 crore cannot be checked.
Why 7,337,943 equity shares were added between the UDRHP-I and 19 September 2026, and what lies behind the further Rs 2.40 crore rise in paid-up capital since then.
FY26 accounts on the Registrar's record. The FY26 annual report is on the company's website, but the FY26 financial statements filing (Form AOC-4) was not among the documents filed up to 27 October 2026.
A red herring prospectus or price band. Neither is on the company's IPO page as at 19 November 2026.
Net read: these are disclosure gaps, not red flags. The RHP, when it comes, should carry restated financials for a recent period, which would settle most of this list.
The Desk View
Priveq's desk price for PRISM is Rs 22.25 per share as of 19 November 2026, on the Rs 1 face value. Three facts frame it:
The price has kept pace with one quarter of operating growth. At Rs 22.25 (19 November 2026), EV is about 19.3 times trailing after-lease EBITDA to June 2026, close to the decode's 19.5 times on FY26.
Profit after tax is still not the anchor. About 69% of Q1 profit was a deferred tax asset, against 60% for FY26.
The IPO terms have not moved. The fresh issue is up to Rs 3,350 crore and the price band is not set.
The one variable that would most change this view: EBITDA as restated in the RHP for a recent period, against the Chairman's Rs 741 crore for Q1 and the press's Rs 760 crore, because the multiple a buyer is paying depends on which is right. The one event to watch: the RHP itself, with its price band.
FAQs
What is the PRISM (OYO) unlisted share price today?
Priveq's desk quotes PRISM at Rs 22.25 per share as of 19 November 2026, on the Rs 1 face value. That is 8.5% above the Rs 20.50 used in our DRHP decode. Talk to the desk for a live quote.
What were PRISM's Q1 FY27 results?
Revenue rose 35% to about Rs 2,814 crore and profit after tax 17% to Rs 353 crore, the Chairman told the 12 October EGM. Adjusted EBITDA net of lease expenses rose 35% to Rs 589 crore.
How much of PRISM's Q1 FY27 profit came from a tax credit?
About Rs 244 crore of the Rs 353 crore was a deferred tax asset, roughly 69% of the quarter's profit by our arithmetic. Without it, profit after tax was about Rs 109 crore.
Are PRISM's Q1 FY27 numbers audited?
The figures in this note are the Chairman's, from the company-published EGM transcript. Press reports cite audited quarterly statements, which the company has not published, and show EBITDA of Rs 760 crore against the Chairman's Rs 741 crore.
Why did PRISM increase its authorised share capital?
The notice cites headroom for future capital requirements and capital transactions. The Chairman said no shares are being issued now. By our arithmetic, the old 17.6 billion ceiling was close to full on a fully diluted basis with an IPO.
Has the OYO IPO price band been announced?
No. As at 19 November 2026, no red herring prospectus or price band is on the company's IPO page. The latest filing is the 21 October 2026 addendum, which cut the fresh issue to up to Rs 3,350 crore.
What We Can And Cannot Stand Behind
Read directly from primary documents:
Every Q1 FY27 and Q1 FY26 figure in the Q1 table, from the company-published transcript of the EGM of 12 October 2026, as spoken.
The Q1 FY26 figures first given, from the Chairman's letter in the Annual Report FY2024-25.
The authorised capital before and after, and the issued, subscribed and paid-up capital at 19 September 2026, from the EGM notice.
The vote on the authorised capital resolution, from the scrutiniser's report extract filed with Form SH-7 on 16 October 2026; paid-up capital after 19 September, from the Registrar's company master data.
FY26 audited figures, net borrowings and share bases, as set out and sourced in the DRHP decode of 31 October 2026.
Priveq arithmetic, labelled as such: profit without the tax credit and both credit shares, the implied Q1 FY26 revenue, the changes in the Q1 FY26 base, the preference share total, the ceiling headroom and the Rs 20.08 break-even, trailing EBITDA and bookings, every multiple in the EV lens table, and the percentage change in the desk price.
Could not be confirmed:
The audited Q1 FY27 statements, which the company has not published.
Whether Q1 FY26 profit included a tax credit.
Net borrowings at 30 June 2026.
The definition behind each EBITDA figure the Chairman gave.
The reason for the 7,337,943 additional equity shares, and for the Rs 2.40 crore rise in paid-up capital after 19 September 2026.
Company documents were read as published on prismlife.com up to 19 November 2026, and Registrar filings as available up to 27 October 2026.
Primary Sources
Transcript of the EGM of 12 October 2026, Oravel Stays Limited: Chairman's address on Q1 FY27 (segments 11 to 17); shareholder question and reply on authorised capital (segments 48 to 52); resolution (segments 53 and 54).
Notice of the EGM of 12 October 2026, dated 19 September 2026: item 1 (alteration of authorised share capital) and the explanatory statement under Section 102, including issued, subscribed and paid-up capital at the date of the notice.
Form SH-7 clarification, filed 16 October 2026: extract of the scrutiniser's report of 14 October 2026 on the authorised capital resolution (66 voters; 99.9999% in favour).
Annual Report FY2024-25, Oravel Stays Limited: Chairman's letter, Q1 FY2026 provisional figures (PDF p. 5).
Annual Report FY2025-26, Oravel Stays Limited: audited consolidated statements, as used in the decode.
Addendum to the UDRHP-I, 21 October 2026, SEBI listing: fresh issue of up to Rs 3,350 crore.
PRISM (OYO) IPO DRHP Decode, Priveq, 31 October 2026: FY26 figures, share bases and the EV build at Rs 20.50.
Talk to the desk: WhatsApp +91 82874 66698 | support@priveq.in | View PRISM (OYO) on the Priveq Marketplace
Disclaimer: This Event Note is written by Himanshu Singh and published by Priveq India for information only and is not investment advice, a research report or a recommendation to buy, sell or hold any security. Priveq India is not registered with SEBI as a stock exchange, investment adviser or research analyst. The analysis is independent desk research based on Oravel Stays Limited's published documents and audited financial statements listed under Primary Sources; figures marked as Priveq arithmetic are our own calculations and are not company disclosures or guidance. Unlisted shares carry risks including illiquidity, valuation uncertainty and limited regulatory disclosure, and the desk price shown is indicative as of the date stated. Priveq India (Priveq Investech Private Limited, Priveq.in) is the named counterparty on transactions executed through the platform. Investors should do their own due diligence and consult a qualified adviser.